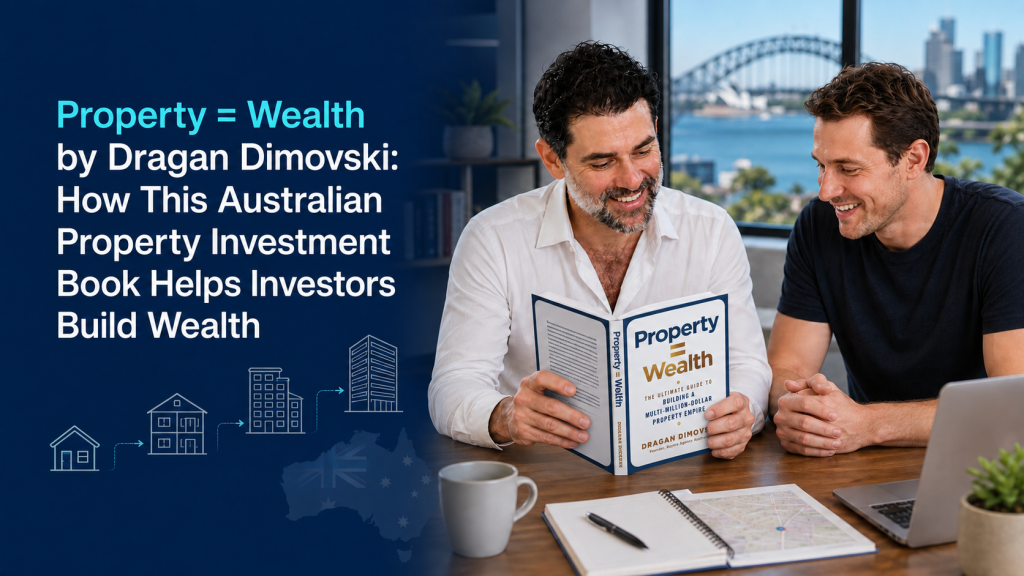
Property = Wealth is a 2026 Australian property investment guide by Dragan Dimovski, published by Wiley (ISBN: 978-1-394-38942-1). It covers team building, the transaction process, mindset, property selection, portfolio design, leverage, ATO awareness, negotiation, and risk management. Its value is educational: investors still need current finance, tax, legal, market, and property-level evidence before acting on any strategy.
This article is published by Buyers Agency Australia, founded by Dragan Dimovski. It explains the published themes and practical relevance of Property = Wealth. It is not an independent book review or personal financial advice.
Many Australians know that property can build wealth, but knowing where to start is a different problem entirely. A book, a podcast, or a promising suburb headline is not the same as a defensible investment decision.
The useful question is not only whether the book is worth reading. It is what the book covers, who it suits, and what an investor still needs to verify before making a purchase. Those distinctions matter more than a summary.
Wiley's published contents provide the factual foundation for this article. The practical application section connects those themes to the strategy-led property investing support that Buyers Agency Australia provides. To go directly to the book's details, you can learn more about Property = Wealth on the official brand page.
What Is Property = Wealth by Dragan Dimovski?
Property = Wealth is a 2026 Australian property investment guide, published by John Wiley & Sons. According to Wiley's official product listing, it is designed to help readers understand how to build a property strategy, assemble the right professional team, navigate the transaction process, and manage risk across a portfolio. The subtitle, as confirmed by Wiley, is The Ultimate Guide to Building a Multi-Million-Dollar Property Empire – a publisher-given title, not a prediction of outcomes.
The book is positioned for both first-time investors and people already building a portfolio. Its primary argument is that property investment works best as a structured, deliberate process rather than a reactive one driven by market noise or conflicting agent advice.
What the publisher confirms about the book
The table below records only details confirmed by Wiley's official product page. All book facts should be attributed to Wiley.
| Fact |
Verified detail |
| Author |
Dragan Dimovski |
| Publisher |
John Wiley & Sons |
| Edition |
1st edition, 2026 |
| Format |
Paperback, approximately 240 pages |
| ISBN-13 |
978-1-394-38942-1 |
| Core themes |
Team building, transaction process, mindset, property selection, portfolio design, leverage, ATO awareness, negotiation, risk management |
Order here: https://dev.buyersagencyaustralia.com.au/property-is-wealth-book/
Who is Dragan Dimovski?
Dragan Dimovski is identified by Wiley as a Qualified Property Investment Advisor and the founder of Buyers Agency Australia. According to both the publisher and official brand material, he brings more than 20 years of experience in the Australian property market. Property = Wealth draws on that background to provide a framework investors can use when evaluating their next property decision.
No transaction totals, portfolio valuations, or performance outcomes have been independently verified for the purposes of this article. Claims about results should be assessed against current, documented evidence.
What Property = Wealth does not promise
No property investment book can guarantee capital growth, rental income, borrowing capacity, tax savings, or a specific investment outcome. Property investment carries real risks including vacancy, interest rate changes, maintenance costs, and liquidity constraints, as Moneysmart outlines for Australian investors.
The book's value is its framework: it can help an investor ask better questions before committing to a purchase, not answer every question on their behalf.
Who Is Property = Wealth For?
The book is most relevant to Australian readers who want a structured introduction to property investing or a framework for reviewing a growing portfolio. It is not a substitute for personal financial, tax, legal, lending, or SMSF advice.
Is Property = Wealth suitable for first-time investors?
Wiley positions the book for people buying their first investment property as well as those expanding an existing portfolio. For first-time investors, the team-building and transaction-process chapters can help demystify what professional support is needed and when. The property-selection and risk-management themes offer a starting point for understanding what to assess before making an offer.
First-time investors still need to confirm their borrowing capacity with a qualified broker, understand their tax position with a registered accountant, and review contracts with a solicitor or conveyancer. The book informs that process; it does not replace it.
How can portfolio builders use the book?
Investors who already own one or more properties can use the portfolio design and leverage chapters to review whether their current holdings are sequenced with a clear goal in mind. The book's risk management theme is particularly relevant here: as a portfolio grows, so does the complexity of managing cash flow, serviceability, and concentration across markets.
Avoiding concentrated exposure to a single suburb, state, or asset type is one of the investment-plan principles that Moneysmart highlights for Australian investors.
What can business owners and SMSF trustees take from it?
Business owners and SMSF trustees can use the book's strategy and team-building themes as a starting point for structuring the right professional group around a potential property purchase. Ownership structure, finance eligibility, and tax treatment inside an SMSF all require specialist advice before any decision is made. The book provides general education, not SMSF-specific guidance.
When is the book not the right starting point?
Readers who need urgent personal financial advice, loan pre-approval, a legal opinion on a contract, a building condition report, a property valuation, or a tax ruling need a licensed professional first. A book cannot provide that level of specific, timely, and situation-dependent guidance.
What Can Australian Investors Actually Learn From Property = Wealth?
Wiley's confirmed chapter themes map directly onto the decisions most Australian investors face before, during, and after a purchase. The table below translates those themes into investor questions and the evidence that still needs to be gathered independently.
| Published theme |
Investor question it raises |
Evidence still needed |
| Assembling an A-team |
Who should review finance, tax, legal, building, and property decisions? |
Current professional credentials and advice for the specific transaction |
| Property selection |
What type of asset fits the strategy? |
Comparable sales, rental evidence, supply, condition, and risk checks |
| Portfolio design |
What role should this purchase play? |
Borrowing capacity, cash flow, existing exposure, and hold period |
| Leverage |
Can the investor hold through stress? |
Broker modelling, cash buffer, rate and vacancy scenarios |
| Negotiation |
What is the maximum price and acceptable terms? |
Comparable sales, contract review, seller evidence, and negotiation strategy |
| Risk management |
What could invalidate the investment case? |
Due diligence, insurance, title, planning, building, and lease evidence |

Assembling a trustworthy property investment team
One of the book's core themes, as confirmed by Wiley, is building what it calls an A-team. In practice, this means identifying a mortgage broker, accountant, solicitor or conveyancer, buyers agent, property manager, valuer, and building and pest inspector whose interests are aligned with the buyer, not the vendor.
Not every transaction requires every professional. A new apartment purchase has different professional requirements than a commercial industrial asset. The key question from this chapter is: which professionals does this transaction actually need?
Understanding the property transaction process
For investors who have never bought an investment property, the sequence from strategy through to settlement can feel opaque. The book's transaction-process theme covers the general flow from research and engagement through to exchange, finance confirmation, and settlement.
Understanding the process before entering it reduces the likelihood of time pressure forcing poor decisions at exchange or finance approval stages.
Choosing an investment property without chasing headlines
The property-selection theme connects asset type, location, tenant demand, holding costs, resale depth, and risk into a single evaluation frame. Choosing a property based on a headline suburb ranking or a vendor's projected rental income is a common source of investor regret.
Property-specific evidence – including comparable sales, independent rental appraisals, vacancy data, and building condition – must be current and independently sourced before a price is set. To understand buying an investment property step by step, the buying an investment property step by step guide from Buyers Agency Australia covers the sequence in practical detail.
Using portfolio design, leverage, and tax knowledge carefully
Borrowing to buy property can increase both gains and losses. The leverage theme in the book is useful because it prompts investors to model their position under unfavourable conditions – higher interest rates, extended vacancy, or a fall in estimated value – not only under optimistic ones.
Tax treatment for rental property, including deductions, negative gearing, and depreciation claims, depends on individual circumstances. The ATO's rental property guidance is the primary source for Australian investors checking what is and is not deductible, and a registered tax professional should be consulted before structuring any purchase.
Negotiating and managing risk
The book's negotiation and risk-management chapters connect directly to two of the most consequential moments in an acquisition: setting a maximum price based on evidence, and confirming that the due diligence process has identified the asset's real risks.
Risk management before settlement includes contract review, building and pest inspection, title search, planning checks, insurance confirmation, and a clear understanding of vacancy and exit risk. None of these can be skipped simply because a property looks attractive on paper.
How Does Property = Wealth Help Investors Think Beyond a Single Property?
A portfolio perspective asks what job the next property must perform and whether the investor can hold it under conservative assumptions. This is a more structured question than simply asking whether the property looks good or the yield appears sufficient.
From one property to a portfolio role
The book's portfolio design theme encourages investors to assess each purchase by its strategic role: is the asset intended to support cash flow, capital growth, geographic diversification, or a future acquisition by releasing equity? Answering that question before searching for a property narrows the field and reduces the risk of a purchase that solves no clear problem.
To build a long-term property strategy, investors need to understand how each asset connects to the next, not evaluate properties in isolation.
Cash flow, capital growth, and holding capacity
No single property is likely to deliver maximum cash flow and maximum capital growth simultaneously. Accepting that tradeoff is part of portfolio design. The more important question is whether the investor can hold the asset through a vacancy period, a rate increase, or a period of flat capital values without being forced to sell.
Holding costs include mortgage repayments, property management fees, maintenance, insurance, land tax, body corporate fees where applicable, and acquisition costs that must be recouped before the investment is profitable. These should be modelled conservatively, not optimistically.
How should an investor test the next purchase?
Before committing to a property, Moneysmart recommends that Australian investors confirm their investment goals, time horizon, and risk tolerance before selecting an asset. In practical terms, that means working through a sequence:
- Confirm goals and financial position with a broker and accountant.
- Assess whether the cash buffer is sufficient to absorb 2 to 3 months of vacancy.
- Define the portfolio role the property must fill.
- Model the holding position under a conservative rate and vacancy scenario.
- Assess the effect on serviceability for future acquisitions.
- Proceed only when the investment case holds under those conservative assumptions.
Can the Book's Principles Apply to Residential and Commercial Property?
The strategy, risk, team, research, and negotiation principles in Property = Wealth can be applied as a thinking framework across different asset types. However, Wiley's publicly listed contents do not explicitly confirm dedicated chapters on office, retail, or industrial property. Commercial application should be treated as an additional investor lens informed by specialist knowledge, not as confirmed book content.

Applying the framework to residential investment property
Residential property is where most Australian investors begin. The framework's application here covers tenant demand in the target area, comparable sales, vacancy history, maintenance obligations, strata or body corporate requirements, land tax exposure, insurance, rental evidence, and resale depth.
Concentration risk is worth noting: holding multiple residential assets in the same suburb or state increases exposure to a single market cycle, as Moneysmart's investment planning guidance makes clear.
Applying the framework to office, retail, and industrial assets
Commercial investors applying general strategy principles to office, retail, or industrial assets need to add a second layer of due diligence that residential buyers typically do not face. The income stream in commercial property is driven by a lease rather than market rent, and the quality of that income depends on the tenant covenant, lease terms, rent review mechanism, outgoings structure, and remaining lease length.
For practical commercial property buying support, Buyers Agency Australia's commercial service covers the additional evidence requirements that distinguish these assets from residential investment property. Investors considering industrial assets specifically can also refer to industrial property investment guidance for a sector-specific overview.

Why commercial property requires a different evidence pack
The table below contrasts what residential and commercial investors must assess before making an offer.
| Strategy question |
Residential application |
Commercial application |
| What creates income? |
Residential rent and tenant demand |
Lease income, tenant covenant, rent reviews, and outgoings |
| What creates risk? |
Vacancy, repairs, strata, insurance, supply |
Lease expiry, tenant default, vacancy, capital works, permitted use |
| What evidence is needed? |
Comparable sales, rental evidence, building and pest, title |
Executed lease, rent ledger, outgoings, title, zoning, valuation, building report |
| Who should review it? |
Broker, accountant, solicitor, inspector, property manager |
Commercial broker, accountant, solicitor, valuer, building consultant, town planner |
A detailed commercial property due diligence checklist is available through Buyers Agency Australia for investors preparing the evidence pack for an office, retail, or industrial acquisition.
What Should Investors Do After Reading Property = Wealth?
After reading the book, investors should convert the ideas into a written strategy, finance check, property brief, evidence checklist, and professional-advice plan. Moving from education to action without that translation step tends to produce reactive purchases.

A post-reading property investment checklist
- Define the financial and non-financial investment goal clearly.
- Confirm borrowing capacity with a qualified mortgage broker.
- Set a cash buffer covering at least 2 to 3 months of vacancy, rate changes, and unexpected maintenance.
- Decide whether the purchase is growth-focused, cash-flow-focused, balanced, or value-add.
- Define the portfolio role and intended holding period before searching.
- Choose the asset type and target markets to research.
- Identify which professional reviews the transaction requires.
- Set a maximum price using comparable evidence, not agent guidance or emotional attachment.
- Confirm tax, legal, insurance, planning, and building questions with the relevant licensed professionals.
- Proceed only when the investment case survives conservative assumptions.
If you want support translating this checklist into a structured property brief, book a free strategy session with Buyers Agency Australia before starting a market search.
When should an investor pause or walk away?
Some situations call for pausing, not progressing. These include:
- Finance has not been confirmed with a qualified broker.
- Rental assumptions are based on the vendor's projection rather than independent rental evidence.
- Title, lease, or planning information is incomplete or unresolved.
- Building or pest concerns have not been professionally assessed.
- Insurance is not confirmed for the asset type and location.
- The portfolio concentration created by the purchase is too high for the investor's risk tolerance.
- The investment case depends on a best-case scenario rather than a conservative one.
Order here: [https://dev.buyersagencyaustralia.com.au/property-is-wealth-book/](https://Order here: https://dev.buyersagencyaustralia.com.au/property-is-wealth-book/)
How Can Buyers Agency Australia Help Turn Strategy Into Action?
Buyers Agency Australia is the brand discussed in this section and is founded by Dragan Dimovski. This is a description of the brand's stated approach, not an independent ranking or guarantee of investment performance.
Understanding a framework is not the same as executing a research process, negotiating a purchase, or coordinating due diligence and settlement. The gap between reading a property investment book and completing a well-structured acquisition is where professional support becomes relevant.
From strategy and research to settlement
Buyers Agency Australia's stated process covers strategy definition, market research, property sourcing including off-market access, assessment coordination, negotiation, due diligence coordination, and settlement support. For investors considering commercial assets, the brand's Buyers Agency Australia investment guidance extends to office, retail, and industrial acquisitions, with the additional lease, tenant, and outgoings assessment that those assets require.
The brand's process begins with a clear investment brief before any property is identified. That brief defines the goal, finance position, target asset type, portfolio role, and risk parameters. No property is put forward until it is assessed against those criteria.
When Buyers Agency Australia may not be the right fit
A buyers agency is not a substitute for a mortgage broker, accountant, solicitor, conveyancer, valuer, building consultant, insurance adviser, financial planner, or SMSF specialist. Investors who need those services first should engage them before considering acquisition support.
The service may also not suit buyers who prefer to conduct their own research, negotiation, and settlement management independently. No buyers agent can guarantee capital growth, rental income, a specific purchase price, or a particular investment outcome.
Frequently Asked Questions About Property = Wealth
What is Property = Wealth by Dragan Dimovski?
It is a 2026 Australian property investment guide by Dragan Dimovski, published by Wiley (ISBN: 978-1-394-38942-1). The publisher describes it as covering strategy, team building, portfolio design, leverage, negotiation, and risk management for Australian investors.
Who is Dragan Dimovski?
Dragan Dimovski is identified by Wiley as a Qualified Property Investment Advisor and the founder of Buyers Agency Australia, with more than 20 years of experience in the Australian property market.
What topics does Property = Wealth cover?
According to Wiley's published contents, the book covers assembling a professional team, the transaction process, investor mindset, property selection, portfolio design, leverage, ATO awareness, negotiation tactics, and risk management.
Is Property = Wealth suitable for first-time investors?
Wiley positions the book for readers buying their first investment property as well as those expanding an existing portfolio. It provides general education, not personal financial, tax, legal, or lending advice.
Does Property = Wealth guarantee property investment success?
No. A book cannot guarantee capital growth, rental income, borrowing capacity, or tax outcomes. Property investment carries risks including vacancy, interest rate changes, and reduced liquidity, as outlined by Moneysmart.
Does the book cover commercial property investment?
Wiley's publicly listed contents do not explicitly identify dedicated chapters on office, retail, or industrial property. The book's general strategy and risk principles can be considered alongside commercial-specific lease, tenant, outgoings, valuation, planning, finance, and building checks.
What should I verify before applying the book's ideas?
Verify finance, cash flow, property evidence, legal position, tax treatment, insurance, building condition, and market assumptions with the relevant licensed professionals. The ATO's rental guidance and Moneysmart are useful starting points for tax and risk questions.
Can a buyers agent help after reading Property = Wealth?
A buyers agent may help translate an investment strategy into research, sourcing, assessment, negotiation, and settlement support. However, this service does not replace specialist financial, tax, legal, lending, valuation, or SMSF advice. The service description above refers to Buyers Agency Australia's stated approach, not an independent performance guarantee.
Is property acquisition support the same as financial advice?
No. Property acquisition support from a buyers agency does not replace personal financial advice, tax advice, lending advice, legal advice, or SMSF advice. Each of those services requires a licensed professional in the relevant field.
What is the best next step after reading the book?
Write down the investment goal, finance position, target asset, risk limits, evidence requirements, and professional-advice needs before searching for a property. Once that brief is clear, consider whether specialist acquisition support makes sense for your situation.
The Practical Takeaway for Australian Property Investors
Property = Wealth can help Australian investors organise the way they think about strategy, portfolio design, negotiation, and risk. The next step is not to buy immediately. It is to test that framework against your goals, finance position, risk tolerance, and the specific evidence for any asset you are considering.
If the book raises more questions than it answers – about finance, tax, legal structure, or which market to research first – that is a healthy sign. It means the framework is doing its job: prompting better questions before a commitment is made.
- If the reader needs foundational education, the book combined with a written investment brief is a useful starting point.
- If the reader has a defined strategy but lacks time, market access, or acquisition experience, a strategy conversation with Buyers Agency Australia may be the natural next step.
- If the reader needs personal finance, tax, legal, lending, valuation, building, insurance, or SMSF advice, the right specialist comes first.
- If the reader cannot clearly explain the asset's income, costs, risks, and exit assumptions, that is a reason to pause, not proceed.
To map out your next property move, book a free strategy session with Buyers Agency Australia. If you want to discuss fit and next steps directly, contact the Buyers Agency Australia team.
 General
Discover what Property = Wealth by Dragan Dimovski covers, who it suits, and how Australian investors can apply...
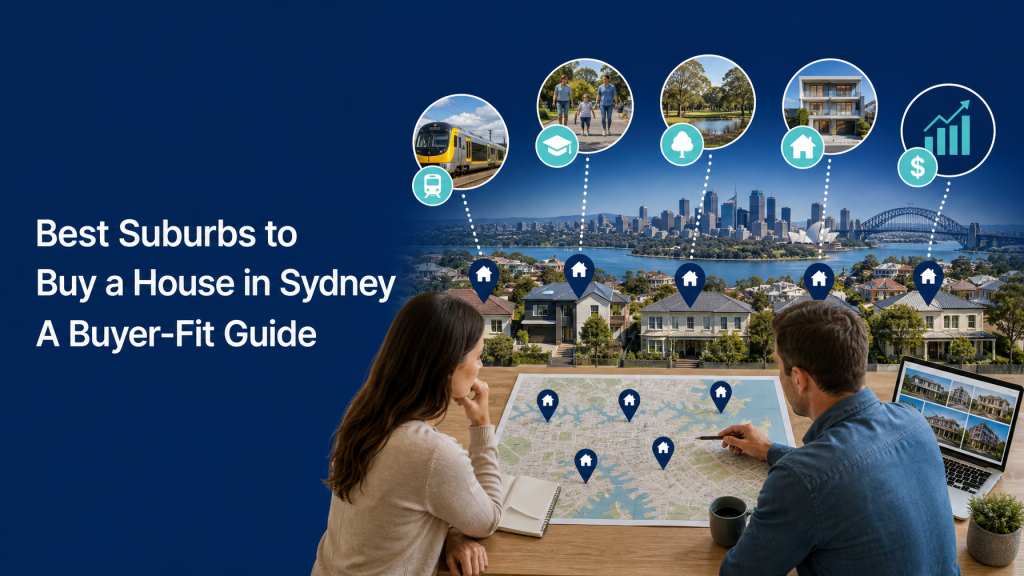
The best suburb to buy a house in Sydney depends on your budget, commute, school needs, lifestyle, property type, and whether you are buying to live in or invest. A defensible shortlist compares current house sales, transport, schools, amenities, housing supply, and property-level risks rather than ranking suburbs on popularity alone. Domain reported a Sydney median house price of $1,733,891 for the June 2026 quarter, down 3.3% from the March peak, but suburb and property-level differences are substantial and must be checked before making an offer. (domain.com.au)
Most buyers arrive at suburb research after receiving a borrowing-capacity figure from their broker. Then the gap between what they can spend and where they want to live becomes very clear, very quickly. House size, location, lifestyle, and budget rarely all point to the same postcode.
"Best suburb" is an incomplete question until you define whether the priority is a family home in a quality school catchment, fast access to the CBD, land size, or rental demand. The answer changes significantly depending on the buyer.
This guide uses consistent criteria and dated evidence to separate suburb screening from the assessment of the individual property. If you want strategy-led property buying support from the outset, that foundation makes the process far more focused.
What makes a suburb one of the best places to buy a house in Sydney?
No suburb is objectively best. What makes a location suitable is whether it matches the buyer's budget, daily requirements, property-type needs, and long-term risk tolerance after current evidence is applied.
For Sydney property buying guidance, the evidence framework should cover at least seven criteria before a suburb is shortlisted:
| Criterion |
What to assess |
Key sources |
| House prices and recent sales |
Dated median for houses (not units or mixed) |
NSW Valuer General, Domain (June 2026) |
| Budget fit and borrowing capacity |
Total cash required including stamp duty and costs |
Lender or broker confirmation |
| Transport and employment access |
Rail, metro, bus, ferry frequency and interchange needs |
Transport for NSW |
| Schools and catchments |
Exact-address enrolment eligibility, not proximity alone |
NSW School Finder |
| Parks, retail and daily amenities |
Walkability, local centres, childcare and health services |
Council pages |
| Housing stock and land component |
Supply of detached houses versus units in the suburb |
NSW Valuer General sales data |
| Planning, flood and bushfire risk |
Zoning, development pipeline, Section 10.7 certificate |
NSW Planning Portal, NSW RFS |
A suburb can pass this screen while an individual house fails due diligence. The suburb and the specific property are two separate assessments.
Domain's June 2026 House Price Report recorded the first quarterly decline for Sydney houses in 3.5 years, with selling conditions shifting toward buyers. That context matters when evaluating comparable sales for any shortlisted suburb.
Which Sydney suburb is best for your budget and lifestyle?
Rather than naming a single winner, the more useful question is which market group fits your situation. The table below maps buyer types to general suburb characteristics. Price references are illustrative of the market segments and should be verified against current NSW Valuer General sales data before acting.
| Buyer type |
General suburb characteristics |
Likely trade-off |
| First-home buyer |
Outer metropolitan, unit or smaller house, near rail |
Longer commute, less land |
| Family |
Middle-ring access to quality schools, parks, local centres |
Higher price for house and land |
| Professional / commuter |
Inner or middle ring with reliable CBD or employment-hub access |
Smaller house or land component |
| Upsizer |
Established suburb with larger housing stock, potential for renovation |
Significant price jump from first property |
| Downsizer |
Well-serviced suburb with lower-maintenance housing, lifestyle amenity |
Limited detached house supply at entry price |
| Residential investor |
Rental demand depth, supply constraints, tenant profile match |
Popular suburb does not equal suitable investment |
A buyer can identify the right suburb category and still select an unsuitable dwelling. A smaller house on a busy road in a desirable suburb can underperform a well-positioned house on a quieter street in a less-prominent suburb. Suburb screening and property assessment are separate steps.
Best affordable suburbs to buy a house in Sydney
How these suburbs were evaluated: We compared buyer fit, current house-sale evidence availability, transport corridor access, housing type composition, planning context, and proximity to employment hubs. The shortlist is non-ranked. Price figures show the reporting period. A suburb passing this screen does not mean every property in that suburb is suitable. Buyers should verify current sales volume and dwelling condition independently.
The Sydney property market's June 2026 median of $1,733,891 for houses means genuinely accessible house prices relative to the citywide figure are concentrated in outer western, south-western, and some north-western corridors. Western and south-western suburbs such as Granville, Merrylands, and Chester Hill have been cited in market commentary as areas where house prices may sit materially below the citywide median, though buyers should verify current sales data directly through the NSW Valuer General before drawing conclusions.
| Suburb area |
Transport corridor |
Typical housing type |
Main buyer fit |
Key limitation |
| Granville / Merrylands |
T2 / T5 train lines to Parramatta and City |
Older detached houses, semi-detached |
First-home buyers, investors |
Older dwelling stock may need significant capital expenditure |
| Chester Hill / Sefton |
T3 rail corridor |
Detached houses, mix of block sizes |
Families, first-home buyers |
Commute to CBD is 45-plus minutes; verify current services with Transport for NSW |
| Campbelltown corridor |
Macarthur rail line |
Houses with land |
Families, upsizers on tighter budgets |
Distance from CBD; check flood risk for individual properties |
| Blacktown / Seven Hills |
T1 Western line, future metro |
Detached houses, townhouses |
First-home buyers, families |
Supply pipeline may affect resale depth; check development approvals |
What to check beyond the median house price
A suburb median includes a range of dwelling conditions, street positions, and block sizes. Before shortlisting a specific property, verify:
- Land size and configuration: Corner blocks and irregular lots carry different constraints.
- Dwelling condition: Older stock in value suburbs often requires material renovation budgets.
- Street position: Proximity to main roads, rail corridors, or industrial zones affects liveability and resale.
- Flood and bushfire exposure: Run the address through the NSW RFS bush fire prone land tool and the NSW Planning Portal.
- Section 10.7 planning certificate: Apply through Service NSW to check zoning, flooding constraints, and development restrictions.
- Transport frequency: Verify actual timetables with Transport for NSW rather than estimated times from listings.
- School catchment: Check the exact address using NSW School Finder and confirm directly with the school.
- Total holding costs: Factor rates, insurance, maintenance, and potential strata fees into monthly cash flow.
Best family-friendly suburbs in Sydney
Family suitability is not a suburb label. It is the combination of verified school access, usable parks and outdoor space, childcare availability, local services, transport options at the times that matter, and the type of housing available at the buyer's actual budget.
Middle-ring suburbs across the Inner West, Northern Beaches, Hills District, and North Shore corridors are often cited in discussions of family-friendly Sydney locations. What those discussions frequently omit is that the house types, price points, and catchment boundaries differ significantly within each of those regions.
Some areas worth assessing for family buyers include:
- Inner West (Ashfield, Leichhardt, Marrickville): Good rail access, established local centres, and a mix of housing from terrace houses to larger semis. Inner West property buying support covers this corridor in more detail.
- Hills District (Castle Hill, Baulkham Hills): Larger land parcels, newer housing stock, and good access via the North West Metro to Norwest and the CBD, though prices reflect that demand.
- Northern Beaches (Dee Why, Collaroy, Narrabeen): Strong lifestyle appeal but limited rail access; bus and future transport reliability should be verified with Transport for NSW before committing.
- Canterbury-Bankstown area (Belmore, Lakemba, Hurstville corridor): More accessible price points with reasonable rail access, diverse amenities, and established primary schools; dwelling condition and flood risk vary by street.
How school catchments and family amenities affect the shortlist
School access in New South Wales depends on the buyer's exact street address, not just the suburb name. Catchment boundaries can change, and proximity does not guarantee enrolment. Before finalising a shortlist:
- Enter the full address in NSW School Finder to identify the designated public school.
- Contact the school directly to confirm current enrolment rules and any capacity constraints.
- Check whether the school provides the year levels and programs the family needs.
- Visit the local area at school drop-off and pick-up times to assess traffic and route options.
- Confirm childcare availability and after-school options within a reasonable travel radius.
Do not rely on historical catchment descriptions from listing portals or social media. They are frequently outdated.
Best Sydney suburbs for professionals and commuters
For professionals, the right suburb depends on the actual destination, not just the generic "CBD access" label. Sydney has multiple major employment hubs, including the Sydney CBD, Parramatta, Macquarie Park, North Sydney, and the emerging Western Sydney Aerotropolis corridor.
| Employment hub |
Practical suburb zone to assess |
Recommended transport check |
| Sydney CBD |
Inner West, Eastern Suburbs, Lower North Shore, Sutherland shire via Illawarra line |
T1, T2, T3, T4, T8 train lines; Sydney Metro City |
| Parramatta |
Parramatta itself, Westmead, Granville, North Parramatta |
T1 Western, T5 Cumberland, Metro West (in progress) |
| Macquarie Park |
Ryde, Meadowbank, West Ryde, Lane Cove |
Metro Northwest Line to Macquarie Park station |
| North Sydney |
Crows Nest, Waverton, Neutral Bay, Cammeray |
Metro City via new Crows Nest station; bus |
| Western Sydney |
Penrith, Campbelltown, Liverpool |
Western and South Western rail corridors |
Always verify current routes, timetables, and interchange requirements directly through Transport for NSW. Infrastructure projects change service patterns, and listing-portal commute estimates are not reliable.
Is inner-ring convenience worth the higher purchase price?
The honest answer is: it depends on what the buyer is giving up.

| Factor |
Inner-ring suburb |
Middle or outer-ring suburb |
| Commute time |
Shorter, more reliable |
Longer, may involve interchanges |
| Purchase price |
Substantially higher |
More accessible |
| House size and land |
Smaller, often terrace or semi |
Larger, more detached housing |
| Renovation restrictions |
Heritage controls common |
Fewer restrictions in newer areas |
| Resale depth |
Strong owner-occupier demand |
Varies by corridor |
Transport access does not automatically create capital growth, and a shorter commute does not justify any price premium without comparable sales support. Run the numbers against verified sales data before deciding.
Best suburbs in Sydney for property investors
Investment suitability and owner-occupier suitability use different criteria, and conflating them is one of the most common suburb-selection errors. This section is secondary to the owner-occupier focus of this guide. For deeper investment suburb analysis, the team at Buyers Agency Australia has published dedicated strategy-led Sydney investment suburb research covering rental demand, supply, and portfolio fit.
For investors assessing Greater Sydney suburbs, the key screening questions are:
- What is the tenant profile and depth of rental demand in this suburb?
- What does the supply pipeline look like, including approved developments and rezonings?
- What is the gross yield based on verified rental evidence, and how does the net yield compare after all costs?
- What property type trades most frequently, and does that match the investment brief?
- Does the suburb role in the portfolio make sense given concentration risk?
To build a property investment strategy before choosing a suburb, clarify the portfolio objective first. A suburb that suits a buy-and-hold cash-flow strategy will differ from one suited to a future land-release position.
This is general information only, not personal financial or tax advice.
Why a popular suburb is not automatically a suitable investment
Suburb popularity in media coverage, social media, and auction clearance headlines does not confirm investment suitability. A high-profile suburb can carry:
| Risk factor |
What to check |
| Apartment oversupply |
Development approvals and completions in the postcode |
| Rising vacancy |
Current vacancy rate from a dated, recognised data source |
| High strata costs |
Levy schedules and special-levy history in the strata records |
| Gross versus net yield gap |
Body corporate, management, maintenance, and insurance costs |
| Tenant concentration |
Single employer or student dependency can affect vacancy during downturns |
Verify rental evidence against dated suburb-level data, not a single listing price. For a step-by-step process, see buying an investment property step by step.
Premium and established Sydney suburbs worth considering
Established suburbs with limited land supply, strong owner-occupier demand, and well-developed amenity are worth assessing for buyers with the appropriate budget and property-type brief. These are not risk-free locations, and no suburb guarantees growth.
Areas that consistently attract strong owner-occupier depth include the Eastern Suburbs corridor (Randwick, Coogee, Bronte), Lower North Shore (Mosman, Neutral Bay, Cremorne), Inner West established pockets (Balmain, Leichhardt, Annandale), and parts of the Northern Beaches.
For Eastern Suburbs buying guidance, coastal access, proximity to the CBD, and limited new housing supply contribute to consistent buyer demand, though the entry price for detached houses in this corridor is well above the Sydney median.
Buyers should note that established suburbs often carry heritage planning controls that restrict renovation, extension, and redevelopment. Check with the relevant local council and obtain a Section 10.7 planning certificate before proceeding.
How should you compare Sydney suburbs before buying?
Suburb comparison should follow a sequence, not a shortlist-first approach. The NSW Government property buying guidance sets out the key stages of property purchase in New South Wales. Applied to suburb selection, the logical order is:

- Confirm borrowing capacity and total cash required including stamp duty, conveyancing, building inspection, and buffer.
- Define house, townhouse, or unit requirements so the suburb search reflects the actual dwelling type available.
- Set the maximum commute time and the specific destination before mapping suburb zones.
- Check current sales and comparable properties using dated NSW sales evidence, not automated valuations.
- Verify schools, transport, and amenities using official sources, not listing-portal descriptions.
- Review planning, flood, bushfire, and contamination risks at the property level using the NSW Planning Portal and NSW RFS tools.
- Inspect the property, review the contract, and obtain professional advice from a conveyancer, solicitor, building inspector, and mortgage broker.
The order is deliberate: buyer brief first, then market, then suburb, then specific property, then due diligence, then offer.
What suburb-level checks should happen before a property inspection?
Before booking an inspection, complete the following evidence pack for each shortlisted suburb:
| Check |
Pass |
Investigate further |
Likely remove |
| Current house sales volume |
Multiple recent comparable sales |
Low volume but comparable evidence exists |
No verified sales in 12 months |
| House versus unit composition |
Clear detached-house market |
Mixed or unit-dominant suburb |
No detached house stock in budget |
| Commute test |
Under maximum travel time at peak hour |
Near maximum; verify timetables |
Exceeds maximum or requires multiple interchanges |
| School catchment confirmed |
Confirmed via NSW School Finder for exact address |
Catchment pending school confirmation |
Address falls outside preferred catchment |
| Development pipeline |
No major adjacent approvals |
Some infill but low-density |
Significant high-density pipeline adjacent |
| Flood or bushfire mapping |
Clear on NSW Planning Portal |
One risk flag present; property-level certificate needed |
Multiple constraints requiring specialist advice |

Common mistakes buyers make when choosing a Sydney suburb
Most suburb-selection errors come from using incomplete information or confusing category-level data with property-level reality.
- Choosing from a headline or social-media list. Media rankings are rarely updated with current sales evidence and seldom reflect the buyer's specific brief. Check dated verified sales data for the suburb instead.
- Chasing the lowest median without checking travel time or dwelling condition. An accessible median price in a distant suburb can carry a commute cost and renovation budget that eliminates the financial advantage. Run the full cost comparison.
- Confusing suburb median data with the value of a specific house. A suburb median includes all transaction types. A house on a main road or with structural issues can sit well below or well above the median for different reasons. Use comparable sales at the street level.
- Assuming school proximity guarantees enrolment. As noted above, school access in NSW is address-specific. Confirm using NSW School Finder before committing to a suburb based on school access.
- Ignoring flood, bushfire, planning, and strata issues. These are property-level constraints, not suburb-level ones. A suburb that is generally low-risk can contain individual properties with significant exposure. Obtain a Section 10.7 planning certificate for the specific address.
- Relying on a single data source. No single report, portal, or agent opinion provides a complete picture. Cross-reference the NSW Valuer General, Transport for NSW, NSW School Finder, and council planning portals for each suburb.
When can a buyers agent help with Sydney suburb selection?
A buyer-side agent operates exclusively for the purchaser, not the vendor. Under NSW Government buyer-agent guidance, a buyers agent can help a purchaser define the brief, search for properties, provide information and advice, access off-market opportunities, and assist with negotiation and settlement.
The Buyers Agency Australia approach, led by property expert Dragan Dimovski with more than 20 years of experience, applies a strategy-to-settlement process across suburb research, property sourcing, due diligence, negotiation, and settlement support. The process begins with a clear buyer brief before any suburb or property is shortlisted.
For anyone researching what a Sydney buyers agent does before deciding whether buyer-side representation is appropriate, that explanation covers the scope and limitations of the role.
| What a buyers agent can do |
What a buyers agent does not replace |
| Define the suburb brief and screening criteria |
Legal advice from a conveyancer or solicitor |
| Source on-market and off-market options |
Mortgage broking and lender comparison |
| Assess comparable sales and property value |
Structural building inspection and pest report |
| Negotiate price and terms at auction or private treaty |
Accounting, tax, or financial planning advice |
| Coordinate due diligence and settlement |
NSW Fair Trading or legal dispute resolution |
Service details for Buyers Agency Australia checked September 2026. Confirm current scope, fees, and availability directly with the team before engaging.
Buyers Agency Australia is the service provider discussed in this section. The article is general educational information, not personal financial, tax, or legal advice. Confirm current service scope, fees, and availability directly with the team before engaging.
If you want support mapping out your suburb brief before shortlisting properties, you can book a free strategy session to work through your requirements with the team.
When Buyers Agency Australia may not be the right fit
Self-directed buyers with strong local knowledge, sufficient time, negotiation experience, and an existing team of legal, finance, and inspection professionals may prefer to manage the process independently. A buyers agent does not replace a solicitor, conveyancer, mortgage broker, accountant, financial adviser, or building inspector. The Buyers Agency Australia approach is most relevant for buyers who want end-to-end support from strategy through to settlement, particularly those buying in markets where they have limited local familiarity or off-market access.
Sydney suburb selection checklist
Before committing to a suburb shortlist, work through these questions:
- Does the suburb fit the buyer's actual confirmed budget, including all purchase costs?
- Is the preferred house type (detached, semi, townhouse) available in meaningful numbers at that price?
- Does the commute work at the actual times that matter, verified against current timetables?
- Are school and amenity claims confirmed through official sources, not portal descriptions?
- Have planning, flood, and bushfire risks been checked at the property level?
- Are comparable sales consistent with the proposed purchase price?
- Does the dwelling fit the buyer's lifestyle needs or portfolio strategy, not just the suburb's general reputation?
- What specific issue would cause the buyer to walk away from this suburb or property?
If any question cannot be answered with verified evidence, that gap should be closed before making an offer, not after.
To map out your next property move with a clear suburb brief and evidence-led approach, a free strategy session with Buyers Agency Australia is a practical starting point. If you are ready to discuss buyer-side acquisition support directly, contact the team.
This is general information only. Obtain professional legal, lending, tax, and financial advice for your specific circumstances before making any property decision.
Frequently asked questions about buying in Sydney suburbs
What are the best suburbs to buy a house in Sydney?
There is no single best suburb for every buyer. The shortlist should match budget, commute, house type, lifestyle, and risk tolerance based on verified current evidence.
Where can I find more affordable houses in Sydney?
More accessible house prices relative to the citywide median are typically found in selected western, south-western, and outer areas, but each location must be checked for commute, housing stock, dwelling condition, and property-level risks.
What are the best family-friendly suburbs in Sydney?
Family suitability depends on verified school access confirmed through NSW School Finder, parks, childcare, transport reliability, local services, and the type of house available at the buyer's budget.
Is it better to buy in Western Sydney or the inner ring?
Western Sydney may provide more house and land for the budget, while the inner ring may offer shorter commutes and stronger access to certain employment and lifestyle hubs. The right answer depends on the buyer's destination, budget, and property-type brief.
How do I compare Sydney suburbs before buying?
Compare current verified sales, transport timetables, school catchments, amenities, housing stock, planning controls, natural hazard exposure, holding costs, and the individual property's condition and contract terms.
Should I choose a suburb based on house price growth?
Price growth should not be the only selection factor. Past performance does not guarantee future results, and a suburb that has risen strongly may not match the buyer's finances, lifestyle, or property-type needs.
How do school catchments work in Sydney?
School access depends on the exact street address and current enrolment rules. Use NSW School Finder for the specific property address and confirm details directly with the school, as catchment boundaries can change.
What property risks should I check in a Sydney suburb?
Check planning controls, flood exposure, bushfire-prone land designation, contamination, strata levy history, building condition, contract terms, and comparable sales at the street level before making an offer.
Can a buyers agent help me choose a Sydney suburb?
A buyers agent can help define the brief, compare locations, source properties, coordinate due diligence, and negotiate. They cannot guarantee a price, yield, growth rate, or investment outcome, and they do not replace legal, financial, or inspection professionals.
When is Buyers Agency Australia not the right fit?
A self-directed process may suit buyers with strong local knowledge, sufficient time, negotiation experience, and trusted legal, finance, and inspection advisers already in place.
 General
Compare the best suburbs to buy in Sydney by budget, lifestyle, transport, schools, property type and long-term suitability.
A commercial buyers agent in Sydney represents the buyer when purchasing office, retail or industrial property. Buyers Agency Australia describes its approach as strategy development, opportunity sourcing, property and lease assessment, due diligence coordination, negotiation and settlement support. Fees, inclusions and professional responsibilities depend on the written engagement, so buyers should confirm them before proceeding.
You might be a business owner searching for your own premises in Greater Sydney, an SMSF trustee weighing up business real property, or a portfolio builder shifting from residential into commercial real estate. In each case, the real question is not simply "Can I buy this property?" but "Does the asset, tenant, lease, price and risk profile fit my acquisition strategy?"
Commercial property requires a different evidence base from residential property. Lease income, outgoings, permitted use, building condition, zoning and vacancy risk all feed directly into the investment case. The Australian Property Institute's due diligence guidance makes clear that a structured, professional approach to these checks is essential before any contractual commitment.
This guide covers the commercial buyers agent role, Sydney asset types, how opportunities are sourced and assessed, what due diligence involves, fee structures, how to evaluate Buyers Agency Australia's commercial service, and a practical decision checklist for your own buying readiness.
What Does a Commercial Buyers Agent in Sydney Do?
A commercial buyers agent is a licensed property professional who represents the buyer, not the seller, throughout the acquisition of commercial property. The selling agent is engaged by and owes their duties to the vendor. A buyers agent's duties run entirely to the buyer.

In NSW, the activities of property agents are regulated under the Property and Stock Agents Act 2002, overseen by NSW Fair Trading. A buyer's agency agreement sets out the scope of engagement, fees and the agent's authority to act. Buyers should verify current licence details through the NSW Fair Trading register before signing any agreement.
Buyers Agency Australia's commercial property acquisition service describes a buyer-side approach covering strategy, sourcing, assessment, negotiation and settlement coordination across office, retail and industrial assets. Exact inclusions depend on the written engagement.
How Buyer-Side Representation Differs from the Selling Agent
The selling agent is appointed by the vendor and has a legal duty to act in the vendor's best interest. A buyers agent is engaged by and paid by the buyer, and their role is to identify, assess and help secure a property that fits the buyer's brief.

The NSW Government's guidance on using a real estate agent to buy property explains the buyer's agent role, buyer's agency agreement requirements and the types of support a buyer's agent may provide. Buyers should seek independent legal advice before signing any agency agreement.
What Support May Be Included
Depending on the written engagement, commercial buyer-side support may include:
- Defining the acquisition brief and market selection criteria
- Sourcing on-market, pre-market and off-market opportunities
- Property and lease assessment, including income and outgoings review
- Coordinating inspections and professional due diligence checks
- Comparable sales and valuation evidence review
- Negotiation strategy and offer management
- Settlement coordination and handover support
All inclusions, exclusions and payment triggers must be confirmed in the written buyers agency agreement before the engagement proceeds.
What a Buyers Agent Does Not Replace
A buyers agent does not replace a solicitor or conveyancer, finance broker or lender, accountant or tax adviser, independent property valuer, building and pest inspector, environmental consultant, planning adviser or, where relevant, a licensed SMSF financial adviser. Each of these professionals provides regulated or specialist advice that falls outside the buyers agent's role.
| Role |
Primary Function |
| Commercial buyers agent |
Buyer representation, sourcing, assessment, negotiation coordination |
| Solicitor or conveyancer |
Contract review, title search, legal advice, settlement |
| Finance broker or lender |
Commercial property finance, loan structure, lender requirements |
| Independent valuer |
Market valuation, capitalisation rate assessment |
| Building consultant |
Physical condition, defects, capital expenditure estimation |
| Accountant or tax adviser |
Depreciation, GST, tax structuring, SMSF compliance |
| Planning adviser |
Zoning, Local Environmental Plan, permitted use, development potential |
Who Should Use a Commercial Buyers Agent in Sydney?
Not every commercial buyer needs buyer-side representation. Whether the support makes sense depends on the buyer's time, experience, access to professional networks, asset complexity and distance from the Sydney market.
Business Owners Buying Their Own Premises
Business owners acquiring their own Sydney premises must balance operational requirements with property fundamentals. Permitted use under the relevant Local Environmental Plan, building condition, loading access, expansion potential, car parking, services and financing all need assessment before an offer is formed. A buyers agent can help separate the business decision from the property decision and apply a consistent evidence-based framework.
SMSF Trustees Considering Commercial Property
SMSF trustees can acquire commercial property that qualifies as business real property under superannuation law, subject to specific rules on related-party transactions, arm's-length leasing and borrowing arrangements. According to ASIC Moneysmart, around 17.5% of SMSF assets are held in residential and commercial property, highlighting how common this strategy has become.
However, SMSF property decisions are technically complex. The ATO's guidance on acquiring assets from related parties applies strict rules to business real property, arm's-length testing and related-party leases. Any trustee considering commercial property within an SMSF should seek specific advice from a licensed financial adviser and a qualified SMSF accountant before proceeding.
Interstate Investors and Portfolio Builders
Investors based outside Sydney, or those building commercial portfolios alongside existing residential holdings, often face challenges with sourcing, inspections, evidence review and coordinating professionals across time zones. Structured buyer-side support can help manage these logistics without implying guaranteed faster acquisition or superior returns. The Sydney property buying support offered through Buyers Agency Australia reflects this national and interstate client profile.
Which Commercial Property Types Can You Buy in Sydney?
Sydney's commercial real estate market spans office, retail and industrial assets, each with distinct income profiles, tenant risk factors and due diligence priorities. No single asset class is universally better. The right choice depends on the buyer's intended use, income requirements, risk tolerance and exit flexibility.

| Asset Type |
Typical Use |
Key Income Risk |
Key Due Diligence Focus |
| Office |
Professional services, corporate occupancy |
Tenant renewal, incentive cycles, vacancy between leases |
Lease term, building services, refurbishment obligations |
| Retail |
Food, service, specialty retail |
Trading performance of tenant, foot traffic, anchor tenancy |
Tenant trading covenant, outgoings split, permitted use |
| Industrial |
Warehousing, logistics, manufacturing, trade |
Functional obsolescence, zoning changes |
Building clearance, access, power, zoning, adaptability |
Office Property
Sydney office assets range from CBD towers to strata suites in suburban centres. Lease duration, rent review structure, incentive obligations and building quality are central to the assessment. Vacancy between leases and the cost of refurbishment or make-good works can significantly affect net income. Accessibility, services and the changing requirements of occupiers should be reviewed against both the current lease and the likely re-leasing scenario.
Retail Property
Retail property income depends heavily on the tenant's trading performance and the strength of the trade area. Outgoings structures, fit-out responsibilities, permitted use restrictions, assignment rights and lease renewal options all affect the risk profile. Relying on a single tenant or a weakening trade area without current evidence creates exposure that the headline rent figure alone will not reveal.
Industrial Property
Sydney industrial and warehouse assets have attracted sustained investor interest due to their functional simplicity, tenant demand from logistics and supply-chain operators, and relatively straightforward lease structures. Building functionality, including truck access, internal clearance height, power capacity and loading configuration, determines which tenants the asset can attract. Zoning under the relevant Local Environmental Plan must be confirmed, as permitted uses vary across Greater Sydney. A detailed industrial property investment guide covers the key assessment factors across this asset class.
How Should Investors Match the Asset Type to Their Brief?
| Consideration |
Office |
Retail |
Industrial |
| Owner-occupier potential |
Yes, in strata or whole-building formats |
Sometimes, subject to permitted use |
Common for trade and logistics operators |
| Long-lease income stability |
Possible with strong covenant tenant |
Possible, but trading risk is higher |
Often achievable with national tenants |
| Outgoings exposure |
Varies by net or gross lease structure |
Tenant often pays outgoings in net leases |
Net lease with landlord cap is common |
| Capital expenditure risk |
Higher, particularly in older buildings |
Moderate, linked to fit-out obligations |
Lower if building is functional and modern |
| Exit flexibility |
Depends on building age, size and location |
Depends on trade area strength |
Generally broader tenant pool in high-demand precincts |
How Does a Sydney Commercial Buyers Agent Find Opportunities?
The sourcing process starts with the buyer's brief, not with a property search. Defining budget, confirmed finance position, asset type, location preference, income requirements, acceptable vacancy tolerance and hold period sets the filter before any property is assessed.
Start with the Acquisition Brief
A well-formed acquisition brief specifies: maximum purchase price, finance position and pre-approval status, intended use (owner-occupier or investment), acceptable asset types, preferred locations across Greater Sydney, minimum lease term or income profile, risk tolerance (new versus established, single versus multi-tenant), hold period and exit considerations.
Without this clarity, a property search becomes reactive. The brief disciplines the shortlist. For broader context on how to structure this approach, the commercial property investment guide from Buyers Agency Australia covers strategy-first planning in detail.
On-Market, Pre-Market and Off-Market Sourcing
Commercial properties are sold through advertised listings, direct agent relationships and, in some cases, off-market approaches where the vendor has not publicly listed the asset. Buyers Agency Australia describes access to on-market and off-market opportunities as part of its commercial service, subject to selling-agent relationships, seller circumstances and timing.
Off-market status does not automatically mean better value, lower risk or less competition. An off-market property still requires full due diligence, independent valuation evidence and the same lease and income assessment as any listed asset. The how to invest in commercial property guide covers this sourcing dynamic in practical terms.
What Should You Assess Before Buying Commercial Property in Sydney?
Commercial property must be assessed as both a physical asset and, where relevant, an income-producing asset. The advertised gross rent is not the same as sustainable net income, and the listing price is not the same as independent market value.
Tenant Quality and Lease Terms
The lease is part of the asset, not an attachment to it. Before forming a price position, buyers should review: tenant business strength and covenant quality, lease term remaining, options to renew and rent review mechanisms, current incentive obligations or outstanding lease incentive recovery, permitted use and any sublease or assignment restrictions, make-good obligations at lease expiry, personal or bank guarantees and any arrears history.
A professional legal review of the lease and all variations is essential. Do not rely on the tenancy schedule alone.
Net Income, Outgoings, Yield and Vacancy Risk
Gross rent minus landlord-borne outgoings equals net income. Outgoings can include council rates, water rates, insurance, land tax, management fees and shared facility costs, depending on the lease structure. The net income figure drives the yield calculation, so any errors in outgoings assumptions distort the return.
Advertised yields are often based on the current passing rent, which may differ from sustainable market rent, especially if the tenant is on an expiring lease or the incentive structure inflates the headline figure. Yield assumptions should be tested against comparable evidence and reviewed by a qualified valuer where the purchase price is material. ASIC Moneysmart's investment property guidance highlights holding costs, vacancy periods and interest rate changes as risks that buyers frequently underestimate.

Location, Zoning, Building Condition and Finance
Access, surrounding land uses, public transport proximity and local planning controls all affect long-term tenant appeal and re-leasing risk. Zoning must be confirmed through the relevant Local Environmental Plan on the NSW Planning Portal before assuming any permitted use. Title and plan documents should be obtained through NSW Land Registry Services and reviewed by the buyer's solicitor or conveyancer.
Building condition, services, capital expenditure requirements and insurance implications should be assessed by a qualified building consultant. Commercial property finance requirements, including deposit size, lender appetite for the specific asset class and location, and loan structure, should be confirmed with a finance professional before the brief is finalised.
What Does Commercial Property Due Diligence Involve?
Due diligence is the structured process of verifying what the buyer has been told and identifying what has not been disclosed. The Australian Property Institute's due diligence guidance makes clear that the exact scope depends on the asset type, intended use and risk profile, and that qualified professionals must conduct each specialist check.

Documents to Request Before Committing
- Contract for sale and any special conditions
- Title documents, registered plan and any encumbrances (via NSW Land Registry Services)
- Current lease, all variations and any side agreements
- Executed tenancy schedule and rent roll
- Outgoings statements and historical invoices
- Tenancy history including any arrears or disputes
- Building approval records, occupation certificate and council records
- Planning information, zoning certificate (Section 10.7 certificate) and any development conditions
- Strata plan, levies and by-laws where the property is strata titled
- Insurance certificates and any current claims
- Finance pre-approval or indicative terms from the lender
Professional Checks to Coordinate
Each specialist role is distinct and cannot be replaced by the buyers agent:
- Solicitor or conveyancer: contract, title, planning certificate, lease review and settlement
- Independent valuer: market valuation and capitalisation rate assessment
- Building consultant: physical condition, defects, capital expenditure estimate
- Pest or environmental consultant: contamination, asbestos, pest infestation where relevant
- Accountant: GST, depreciation, tax treatment, outgoings verification
- Finance professional: commercial property loan structure, lender conditions
- Planning adviser: zoning confirmation, permitted use, development controls
- SMSF financial adviser: superannuation compliance where applicable
The Stop-or-Proceed Decision
Due diligence is not a formality. If title, planning, lease review, building condition, valuation evidence or finance approval raises a material issue, the buyer has three options: renegotiate the price or terms to reflect the risk, add conditions to protect their position, or withdraw before exchanging contracts.
Proceeding automatically when evidence conflicts with the initial brief is one of the most common and costly errors in commercial acquisition. A documented stop-or-proceed gate, agreed with the solicitor and buyers agent before due diligence begins, keeps this decision rational rather than emotional.
If you are approaching this stage and want a structured review of your findings, book a free strategy session with the Buyers Agency Australia team to map the evidence against your brief before committing.
How Should You Negotiate and Secure the Right Property?
A buyers agent negotiates on behalf of the buyer using valuation analysis, comparable sales, lease risk and vendor context to inform an offer strategy. The goal is not necessarily the lowest price in isolation, but the best price-and-terms combination given the evidence available.
Build a Price Position from Evidence
A credible price position combines: comparable sales evidence from recent transactions in the same asset class and precinct, capitalisation rate assumptions calibrated to the lease profile and tenant covenant, independent valuation where the purchase price is significant, an assessment of net income after outgoings, and a view of the likely re-leasing cost if the tenant departs.
Advertised yields and vendor price guides are starting points, not conclusions. Where the lease has a short remaining term, near-term expiry risk should be reflected in the offer.
Negotiate Price and Terms Together
Settlement timing, due diligence conditions, access provisions, lease warranties, deposit structure, inclusions and assignment provisions may matter as much as the headline price. A vendor who needs a fast settlement may accept a lower price. A buyer who needs a longer due diligence period may need to offer different terms in exchange.
Negotiation in commercial property is rarely a single conversation. It is a structured process informed by evidence, and the written contract is where the agreed terms become binding.
How Much Does a Commercial Buyers Agent Cost in Sydney?
There is no universal fee for commercial buyer-side services in Sydney. Fees depend on the scope of the engagement, the asset type, the transaction complexity and the written agreement between the buyer and the buyers agent. The NSW Government's buyer's agent guidance confirms that fee structures, payment triggers and engagement scope must be set out in writing.
Fee Structures to Confirm in Writing
| Structure |
How It Works |
What to Clarify |
| Fixed fee |
A set dollar amount for the full engagement |
Whether GST is included, what triggers payment |
| Percentage of purchase price |
A percentage applied to the final purchase price |
The base rate, any minimum fee, and GST treatment |
| Staged or milestone fee |
Payments at engagement, shortlisting, exchange and settlement |
Which milestone triggers each payment |
| Search-only or negotiation-only |
A limited scope engagement for a defined task |
Exactly which services are and are not included |
No current official fee schedule was verified for Buyers Agency Australia at the time of this article's production. Buyers should request a current written fee proposal and confirm all inclusions, exclusions, GST treatment, payment timing and termination provisions before signing.
Questions About Scope, Conflicts and Third-Party Costs
Before engaging any commercial buyers agent, confirm: whether the agent or firm receives any referral fees from third parties such as selling agents, brokers or service providers; who bears the cost of building reports, valuations, legal advice and other professional checks; what happens if no suitable property is found or the buyer withdraws; the termination provisions and notice period; and who is the named person responsible for managing the engagement day to day.
What Should You Ask Before Choosing Buyers Agency Australia for a Sydney Commercial Purchase?
This section describes questions relevant specifically to Buyers Agency Australia and is not an independent comparison or ranking of buyers agents.
Questions About the Commercial Acquisition Process
- Which commercial asset classes do you actively work across in Sydney: office, retail, industrial, or all three?
- How do you form the acquisition brief, and what information do you need from me before starting?
- How are potential properties assessed, and what evidence do you provide before recommending an offer?
- How do you handle off-market opportunities, and what are the limitations on access?
- Who inspects properties on my behalf, and how are findings documented?
- How does your team manage negotiation and settlement coordination?
Questions About the Engagement Agreement
- What is the current written scope of the engagement, including all inclusions and exclusions?
- What is the fee structure, GST treatment and payment trigger?
- What is the term of the engagement and how can either party terminate?
- Who is the named person responsible for my engagement, and how do I communicate with them?
- Are there any referral relationships or third-party arrangements I should know about?
- Do you refer buyers to solicitors, valuers or other professionals, and if so, on what basis?
How Buyers Agency Australia Approaches Sydney Commercial Acquisitions
This section describes Buyers Agency Australia's own buyer-side approach, based on current brand material. It is not an independent ranking or comparison.
Buyers Agency Australia's strategy-led property buying approach for commercial acquisitions follows a sequence from strategy to settlement rather than beginning with a property search. Dragan Dimovski, a property expert with 20+ years of experience, leads the firm's buyer-side advisory work across residential and commercial asset classes.
Strategy Before Search
The approach described by Buyers Agency Australia begins with defining the buyer's objectives and constraints: intended use, target asset class, budget, required income profile, acceptable risk and hold period. Only once this framework is clear does the sourcing process begin. This discipline prevents buyers from making decisions driven by availability rather than strategy.
Data-Led Selection, Sourcing and Due Diligence Coordination
For Sydney commercial acquisitions, Buyers Agency Australia describes its commercial buyers agent service as covering office, retail and industrial property sourcing, lease and financial analysis, on-market and off-market sourcing (subject to relationships, seller circumstances and timing), negotiation support and settlement coordination.
The service connects each acquisition to the buyer's broader portfolio plan rather than treating it as a standalone transaction. Off-market sourcing is described as a capability, not a quality guarantee. Every property, regardless of how it is sourced, requires the same full due diligence process. For buyers exploring how this connects to a broader investment strategy, Buyers Agency Australia's strategy-first property investment advice provides relevant context.
Service scope and availability references were checked against Buyers Agency Australia brand material in August 2026. Confirm current inclusions, availability and engagement terms before proceeding.
When This Is Not the Right Fit
Full-service commercial buyers agent support may not suit a buyer who already has established selling-agent relationships in their target submarket, a professional team in place, the time to conduct their own research and inspections, and sufficient commercial property experience to assess lease risk and building condition independently.
The service does not replace legal, tax, financial, valuation, building, environmental or planning advice. Buyers who need only one component of the process, such as negotiation assistance or a second opinion on a specific property, should ask whether a limited-scope engagement is available.
Is a Commercial Buyers Agent Right for Your Sydney Purchase?
The answer depends on the buyer's situation, not on a general rule. ASIC Moneysmart notes that property investment involves risks including vacancy, interest rate changes, holding costs and possible loss of value. Structured buyer-side support may reduce some of these risks through better evidence and process, but it does not eliminate them.
A Sydney Commercial Buying Readiness Checklist
Before engaging a commercial buyers agent or proceeding independently, work through this checklist:
- Finance pre-approval or indicative terms confirmed with a commercial lender
- Acquisition objective defined: owner-occupier, investment income, SMSF or portfolio addition
- Target asset type identified: office, retail or industrial
- Location range and flexibility within Greater Sydney confirmed
- Minimum lease term and income profile required
- Professional advisers engaged or identified: solicitor, accountant, valuer
- Due diligence budget allocated for reports, legal review and valuation
- Maximum price and decision timeline agreed
- SMSF compliance advice obtained if the purchase is within a superannuation structure
If most of these are in place, you are ready to move. If several remain unresolved, addressing them before searching for a property will produce a more disciplined outcome. To map out your next property move before committing to a search, Buyers Agency Australia offers a free strategy session to help buyers clarify their brief.
This article is educational and does not constitute personal financial, tax, legal, planning, valuation or building advice. Readers should seek appropriate professional advice before making any property acquisition decision.
Frequently Asked Questions About Commercial Buyers Agents in Sydney
What does a commercial buyers agent in Sydney do?
A commercial buyers agent represents the buyer when purchasing office, retail or industrial property, covering sourcing, assessment, due diligence coordination, negotiation and settlement support. Exact inclusions depend on the written engagement agreement.
Who should use a commercial buyers agent?
Buyers with limited time, remote location, limited Sydney market access, complex asset requirements or SMSF considerations may benefit most. Self-directed buyers with established networks and professional teams may not need full-service support.
What types of commercial property can Buyers Agency Australia help with?
Based on current brand material, Buyers Agency Australia's commercial buyers agent service covers office, retail and industrial property across Sydney and nationally. Confirm current asset-class coverage before engaging.
Can a commercial buyers agent find off-market property?
Access to off-market opportunities may be available, subject to selling-agent relationships and seller circumstances. Off-market status does not guarantee better value, lower risk or less competition. Full due diligence applies regardless of how the property is sourced.
What should I check in a commercial property lease?
Review the tenant covenant, lease term and remaining duration, options to renew, rent review mechanism, outgoings structure, incentive obligations, permitted use, assignment rights, personal or bank guarantees, make-good provisions and any arrears. Have a solicitor review the actual lease document and all variations.
What due diligence is required before buying commercial property?
Due diligence should cover the contract, title and plan documents, current lease and variations, outgoings history, building condition report, planning certificate, zoning confirmation, valuation and finance approval. The Australian Property Institute recommends using qualified professionals for each specialist check.
How much does a commercial buyers agent cost in Sydney?
Fees vary by service scope, asset type and written agreement. Structures include fixed fees, percentage-based fees and staged milestone payments. Confirm all fee terms, GST treatment and payment triggers in writing before proceeding.
Can an SMSF buy commercial property?
An SMSF may be able to acquire commercial property that qualifies as business real property under the ATO's rules, subject to arm's-length leasing, related-party restrictions and LRBA borrowing conditions. Trustees should obtain specific advice from a licensed financial adviser and SMSF accountant before proceeding.
Do I still need a solicitor, valuer, accountant or building inspector?
Yes. A buyers agent does not replace any regulated or specialist professional. Legal, tax, valuation, building, environmental and planning advice must come from appropriately qualified professionals engaged separately.
Next Steps for Your Sydney Commercial Property Brief
If you are considering buying commercial property in Sydney, these are the practical next steps:
- Confirm your finance position with a commercial lender before searching
- Define your acquisition brief: asset type, location, income requirements and hold period
- Engage a solicitor, accountant and valuer before due diligence begins
- Clarify whether full-service buyer-side support or limited-scope assistance fits your situation
- Confirm SMSF advice if the purchase involves a superannuation structure
To discuss your brief and understand whether Buyers Agency Australia's commercial acquisition approach is right for your Sydney purchase, map out your next property move with a free strategy session.
Ready to take the next step? Contact the Buyers Agency Australia team to outline your acquisition objectives and start the conversation.
 General
Learn what a commercial buyers agent in Sydney does, how office, retail and industrial property is assessed, and...
There is no single best suburb to invest in Sydney for every investor. The right shortlist depends on budget, borrowing capacity, strategy, property type, rental demand, supply pipeline and property-specific risks. Greater Sydney added 75,230 people in the year to June 2025, while major infrastructure projects are reshaping parts of Western Sydney and Greater Parramatta, so investors need to assess both current fundamentals and delivery risk before settling on a location. This guide explains how to do that.
You may have a deposit, a borrowing range and a return target but no clear suburb shortlist. That is a common starting point, and a reasonable one. The problem is that picking a suburb from a popular list, without first defining your strategy, often means buying the wrong asset in the right postcode or the right asset in a market that does not suit your portfolio.
A suburb that looks attractive on gross yield may create cash-flow pressure for a leveraged investor, while a premium inner-ring location may not suit someone who needs income support in the early years. Strategy has to come before suburb.
This guide uses a repeatable evaluation framework and a non-ranked research shortlist. It is general educational information, not personal financial, tax or legal advice. Before acting on any information here, seek advice suited to your circumstances from a qualified professional.
For strategy-led property buying support, Buyers Agency Australia works with investors across Greater Sydney and nationally to define the brief, compare markets and source investment-grade properties.
Best Suburbs to Invest in Sydney: What Investors Should Know First
No suburb is universally the best for every investor in the Sydney property market. Location suitability depends on budget, borrowing capacity, cash-flow tolerance, preferred property type and the role a specific purchase plays in a broader portfolio.
The Australian Bureau of Statistics regional population data records that Greater Sydney grew by 75,230 people in the year to June 2025, a 1.4% annual growth rate. That sustained population intake supports underlying housing demand across the city, but it does not translate evenly into investment opportunity across every suburb or every property type.
The distinction between suburb screening and property selection is important. A suburb can have sound demand fundamentals while a specific building, lot or strata plan within it carries material risk. This guide treats those as separate decisions.
How Do You Identify the Best Suburb to Invest in Sydney?
The evaluation sequence matters. Starting with a suburb name before defining the investor's constraints is a common mistake that competing listicles reinforce. A defensible process works in this order: investor brief, market screen, suburb screen, property screen, risk review.

Gross yield provides a useful starting comparison. Divide annual rent by purchase price and multiply by 100. A property purchased for $700,000 generating $520 per week in rent produces a gross yield of approximately 3.9%. Net yield, which accounts for management fees, rates, insurance, maintenance, vacancy and strata costs, will be meaningfully lower. Cash flow after interest repayments at current rates may differ again depending on borrowing structure.
Start With the Investment Brief, Not the Suburb List
Before naming a suburb, define:
- Budget and deposit: What can you borrow, and what equity or cash deposit applies?
- Property type: House, townhouse, unit, duplex-style opportunity or commercial asset?
- Growth or income priority: Is capital growth the primary objective, or does cash flow need to be serviceable from year one?
- Time horizon: Are you holding for five years, ten or longer?
- Vacancy tolerance: Can the property hold through one to two months of vacancy per year without creating financial stress?
- Portfolio role: Is this the first acquisition, a portfolio balance play or an income-support asset?
- Exit flexibility: Would you sell, refinance or subdivide at a future point?
Finance assumptions should be reviewed with a licensed mortgage broker or financial adviser, not modelled from a generic calculator.
Check Demand, Supply and Employment Drivers
Once the brief is clear, assess each suburb against:
- Population movement: Is the suburb's catchment growing, stable or contracting? ABS regional and LGA data provides a starting point.
- Employment hubs: Proximity to major employers supports tenant stability. Westmead Health Precinct, Parramatta CBD and Western Sydney International Airport (currently under final construction phases and expected to open in 2026) are examples of employment anchors with ongoing activity.
- Transport access: Distinguish existing services from funded, approved, under construction and proposed projects. A train station open today has a different risk profile from a metro line at planning stage.
- Tenant profiles: Who rents in this suburb? Workers, students, families and downsizers all behave differently in a vacancy event.
- New supply: What is being built, approved or proposed? Apartments near major corridors can face short-term vacancy pressure when a wave of new supply settles.
- Comparable sales: Are properties selling, and at what price relative to asking? Days on market and clearance rates signal buyer depth.
Use Suburb Data as Evidence, Not a Prediction
Every data point needs a source, period, geography and property type before it can be used responsibly. A useful data checklist:
- Median price (source, period, property type)
- Median weekly rent (source, period, property type)
- Gross yield (calculated, not assumed)
- Vacancy rate (source and period)
- Stock on market and days on market
- Comparable recent sales (address-level, not suburb averages alone)
- New dwelling approvals and completions
Historical performance does not guarantee future returns. Infrastructure announcements can affect access and amenity, but they do not automatically cause capital growth. Treat each as a research prompt, not a buying signal.
Sydney Suburbs With Investment Fundamentals Worth Researching
How this Sydney suburb shortlist was developed
The areas below are organised by investor objective and market role, not ranked by a single score. Each group was assessed against rental demand and vacancy evidence, population and employment drivers, existing and planned transport, new supply pipeline, property type suitability, comparable sales depth, and hazard and planning risk. Suburb-level price, rent and yield figures were not independently verified at the time of drafting. Before inserting numerical comparisons into your own analysis, obtain current dated figures from a recognised data provider such as PropTrack, Cotality, Domain or SQM Research.
Western Sydney and South-West Growth Corridors
Suburbs including St Marys, Blacktown, Liverpool and the Leppington and Austral growth precincts have attracted investor attention because of their relative affordability compared to the inner and middle rings, combined with infrastructure investment.
The NSW Government's Western Sydney investment program includes the Western Sydney International Airport, the Sydney Metro Western Sydney Airport line and planned employment development in the Aerotropolis. These are significant projects, but infrastructure delivery risk must be assessed separately from anticipated investment returns. Delays, cost overruns and phased employment build-up affect how and when access and amenity actually improve.
The outer ring of Greater Sydney has recorded vacancy rates around 2.0% (SQM Research, December 2025 data), and western growth corridors have at times seen tighter conditions of 0.6% to 1.0% in specific periods. Rental demand in these areas is supported by affordability-driven tenant migration from higher-cost suburbs.
Key consideration: New housing supply in growth precincts can be substantial. A suburb with strong rental demand at the suburb level may still have individual estates or apartment complexes with higher vacancy due to concentrated new stock.
Evidence card:
- Demand driver: Employment corridors, infrastructure spend, affordability-driven migration
- Supply check: Significant greenfield development underway; check individual estate supply
- Rental signal: Outer ring vacancy around 2.0% (SQM Research, December 2025)
- Property type: Houses and townhouses dominant in growth precincts; units near transport nodes
- Risk: Construction pipeline, infrastructure delivery timing, resale liquidity in newer estates
Greater Parramatta and Westmead Employment Hubs
Parramatta functions as Western Sydney's second CBD, with major health, education, government and corporate employment anchors. The NSW Department of Planning's Westmead Precinct planning documents the scale of health, education, innovation and transport investment planned for the precinct.
Tenant demand in Greater Parramatta is supported by healthcare workers, university students and professional services employees. Sydney rents climbed approximately 5.5% in the year to July 2026 (Cotality data via OpenAgent, August 2026), and the middle ring, which includes Parramatta, recorded vacancy around 1.8% in December 2025 (SQM Research).
The caution here is apartment supply. Parramatta has seen consistent high-density development near the CBD and light rail corridor. Some completed precincts have experienced localised vacancy easing, and investors in high-rise complexes should assess strata costs, building quality and comparable rent data carefully before committing.
Evidence card:
- Demand driver: Health precinct, second CBD employment, student population, Metro West pipeline
- Supply check: Significant apartment pipeline; assess building-level vacancy, not suburb average alone
- Rental signal: Middle ring vacancy around 1.8% (SQM Research, December 2025)
- Property type: Units with strong yield potential; established houses at higher price points
- Risk: Apartment oversupply in specific towers, strata levies, construction disruption
Established Inner and Middle-Ring Markets
Inner and middle-ring suburbs carry a different risk and return profile. Land scarcity, established amenity, strong owner-occupier demand and transport connectivity have historically supported resale liquidity. These are not yield-focused markets. Gross yields on houses in established middle-ring suburbs often sit well below the Sydney-wide unit average.
The trade-off is entry cost. With the Sydney median house price reaching approximately $1.79 million in the March 2026 quarter (Domain House Price Report, March 2026), a leveraged investor in an established inner-ring suburb needs to be comfortable with a higher loan amount and potentially negative cash flow in the short term.
The premium inner ring may suit investors with strong borrowing capacity, a long time horizon and a portfolio strategy that prioritises capital growth and owner-occupier depth over immediate income. It is not the right fit for every buyer, and proximity to desirable amenity does not guarantee superior total returns.
Evidence card:
- Demand driver: Established amenity, strong owner-occupier base, high tenant competition
- Supply check: Limited new land supply; strata unit supply varies by corridor
- Rental signal: Lower gross yields; tighter vacancy in sought-after pockets
- Property type: Houses and boutique apartments; avoid high-density towers in oversupplied corridors
- Risk: High entry cost, cash-flow pressure, concentration risk for smaller portfolios
Which Sydney Areas Suit Capital Growth, Rental Income or a Balanced Strategy?
The table below compares strategy objectives against the signals, property types and trade-offs that are relevant to each. Treat this as a screening guide, not a forecast.

| Investor objective |
Signals to screen |
Property types to consider |
Trade-offs and risks |
| Capital growth focus |
Land scarcity, owner-occupier depth, infrastructure maturity, employment access, low new supply |
Houses, townhouses with land component |
Higher entry cost, lower gross yield, potential cash-flow pressure |
| Rental income focus |
Gross yield above citywide average, vacancy below 2%, affordable rents relative to suburb median price, tenant depth |
Units, townhouses near employment and transport |
Supply risk in apartment corridors, higher management needs, strata costs |
| Balanced growth and income |
Moderate yield with owner-occupier demand, established amenity, manageable supply pipeline |
Established houses or boutique apartments in middle-ring markets |
Narrower suburb shortlist, higher selectivity required at property level |
Capital Growth-Focused Research Areas
Land scarcity is a consistent feature of suburbs that have recorded sustained capital growth in Greater Sydney. Where land cannot be easily replicated, and where owner-occupiers compete with investors for limited stock, resale conditions tend to be more liquid.
Infrastructure maturity matters here too. A funded and operating rail line has a different investment implication than a proposed metro project. Investors assessing capital growth potential should separate what exists today from what has been announced, approved or commenced.
Portfolio sequencing is an often-overlooked variable. The suburb that suits a first acquisition may not suit a third or fourth purchase. Capital-growth-focused buyers in premium markets may need strong cash reserves or existing equity to service the holding costs through market cycles.
Rental Income-Focused Research Areas
High gross yield can be misleading without accounting for operating costs. Net yield, after property management fees (typically 7% to 10% of rent), council rates, insurance, maintenance, vacancy allowance and strata costs where applicable, will be materially lower than the gross figure.
For a unit with a purchase price of $480,000 generating $520 per week, the gross yield is approximately 5.6%. After strata fees of $600 to $800 per quarter, council rates, property management and an allowance for vacancy, the net yield may sit closer to 3.5% to 4.0%. Finance costs at current rates determine whether the asset is negatively or positively geared. These assumptions should be modelled with a licensed accountant or financial adviser, not taken from a suburb profile alone.
Vacancy risk is the key income variable. Suburbs with concentrated new apartment supply can see vacancy rise quickly when a large complex settles, even if the broader suburb has tight conditions.
Balanced Growth and Income Strategies
A balanced strategy screens for adequate rental support without sacrificing property quality, owner-occupier appeal or long-term liquidity. In practical terms, this often means looking at established houses or boutique apartments in middle-ring suburbs where the tenant base is diverse, comparable sales are active and the supply pipeline does not include a large new development on the same street.
The discipline is in not overpaying for a suburb label. Comparable sales analysis at the property level, not the suburb median, is where a balanced strategy gets tested.
Affordable Sydney Investment Suburbs for Different Budgets
Budget shapes the property type and suburb search before it shapes the suburb name. Three broad bands are worth understanding:
Entry-level budgets may access Western Sydney houses, units in outer-ring suburbs or townhouses in middle-ring precincts, depending on borrowing capacity. Lower purchase prices can bring higher gross yields, but investors should assess supply pipeline, resale liquidity and whether the market has depth beyond investor buyers.
Mid-range budgets may open established houses in middle-ring Western Sydney, units in Greater Parramatta or townhouses in inner-middle ring suburbs. This band typically involves a trade-off between yield and quality of land component.
Higher budgets may suit inner-ring houses or established apartments with owner-occupier demand. Yield will generally be lower, and the investment case rests more heavily on long-term capital growth and resale depth.
No price band is inherently better. A lower purchase price does not automatically mean a better investment, and a higher-priced asset in the wrong location or at the wrong time in the cycle can underperform. Budget is a constraint that changes the property type and search area; it is not a quality signal on its own.
For context, the Sydney median house price was approximately $1.79 million in the March 2026 quarter (Domain House Price Report, March 2026), while Cotality data recorded Sydney dwelling values at approximately $1.24 million in July 2026, reflecting a period of softening from the January 2026 peak. Any numerical planning assumptions should be checked against a current dated source before use.
Is Western Sydney or the Inner Ring Better for Property Investors?
The honest answer is that suitability depends on strategy. The comparison table below sets out the key variables.
| Variable |
Western Sydney (outer and growth areas) |
Inner and middle ring |
| Entry cost |
Lower; wider range of price points |
Higher; concentrated in upper price bands |
| Land component |
Greater for houses in growth precincts |
Limited in inner ring; variable in middle ring |
| Tenant demand |
Supported by affordability migration and employment corridors |
Strong; supported by lifestyle, transport and employment access |
| Owner-occupier depth |
Growing but thinner in newer estates |
Established and deep in most inner and middle-ring suburbs |
| Infrastructure status |
Significant investment underway; delivery risk exists |
Predominantly existing services |
| Gross yield potential |
Generally higher for units near transport and employment |
Generally lower; income not the primary driver |
| Supply risk |
High in growth precincts and apartment corridors |
Lower for houses; moderate for units in some corridors |
| Resale liquidity |
Variable; stronger in established parts of Western Sydney |
Generally stronger in established inner and middle ring |
Infrastructure delivery risk deserves specific attention. The Western Sydney International Airport and associated Metro line represent meaningful long-term investment, but the employment and amenity uplift is phased. An investor buying near the Aerotropolis in 2026 is buying ahead of the full employment build-up, not into a completed precinct. That distinction should be priced into the investment thesis.
Which Property Types Fit a Sydney Investment Suburb Strategy?
Property type and suburb selection are interconnected decisions. The same suburb can contain high-quality houses with strong owner-occupier demand alongside apartment towers with elevated vacancy and strata risk.
| Property type |
Land component |
Gross yield potential |
Key checks |
Key risks |
| House |
High |
Lower in established markets |
Building and pest inspection, zoning, comparable sales |
Maintenance cost, holding cost in premium suburbs |
| Townhouse |
Moderate |
Moderate |
Strata records, body corporate fees, building quality |
Special levies, shared-wall issues, limited lot size |
| Apartment / unit |
Nil or minimal |
Higher; especially in middle and outer ring |
Strata levies, building defects, supply pipeline, vacancy |
Oversupply, strata cost blowout, building defect risk |
| Duplex-style |
Moderate to high |
Moderate to strong where dual income applies |
Council zoning, subdivision potential, separate title |
Planning constraints, higher management complexity |
For investors considering commercial assets such as office, retail or industrial property alongside residential holdings, commercial property buying support requires a separate evaluation framework covering lease terms, tenant covenant, yield and finance structure.
When assessing apartments, review the owners corporation records, capital works fund balance, any pending special levies and the building's defect history. The NSW Government recommends obtaining a strata inspection report and reviewing the most recent AGM minutes before exchanging contracts. Brand-new investment properties carry specific risks that established stock does not; the risks of brand-new investment properties are worth understanding before shortlisting new builds.
What Risks Should You Check Before Buying in a Sydney Suburb?
Suburb-level research does not replace property-level due diligence. A suburb can have sound demand while a specific street, building or lot carries material risk.
| Risk |
How to test it |
Decision response |
| Oversupply |
Check development applications, building approvals and current listings depth in the specific property type and precinct |
Review vacancy trend for the specific property type; avoid buying into a corridor with excessive new supply settling simultaneously |
| Flood exposure |
NSW Government flood mapping and council flood certificates |
Obtain a Section 10.7 planning certificate and, where required, a flood report. Do not rely on suburb-level statements alone |
| Bushfire prone land |
NSW Rural Fire Service bush fire prone land mapping |
Check the property address against the BFPL tool. Obtain specialist advice if land is mapped as bush fire prone |
| Zoning and planning changes |
NSW Planning Portal, Section 10.7(2) and (5) certificate, local council |
Understand what can be built on and around the property |
| Strata liabilities |
Strata inspection report, capital works fund, AGM minutes |
Do not exchange without reviewing strata records. Underfunded capital works funds create special levy risk |
| Building defects |
Building and pest inspection, engineer's report for strata buildings |
Obtain an independent inspection before exchanging |
| Weak tenant demand |
Current vacancy rate for the specific property type in the immediate precinct |
Do not use suburb-wide vacancy as a substitute for street or building-level rental evidence |
| Overpaying |
Comparable sales analysis for the specific property type, condition and position |
Instruct a solicitor or conveyancer to review the contract and conduct a comparable sales review before exchange |
| Optimistic rent assumptions |
Check current rental listings and recent lease evidence for comparable properties |
Use actual comparable rents, not suburb medians alone, to model yield |
For guidance on the NSW buying and inspection process, the NSW Government provides useful baseline expectations on pre-purchase checks.
A Sydney Investment Suburb Research Checklist
Use this checklist before progressing any suburb or property. A material unresolved risk at any step is a reason to pause, not to proceed on headline yield alone.

- Investment brief confirmed: Budget, deposit, borrowing capacity, property type, growth or income priority, time horizon, vacancy tolerance and portfolio role are documented.
- Market data obtained: Suburb-level median price, median rent, gross yield and vacancy sourced from a recognised data provider with a specific date and property type noted.
- Comparable sales reviewed: Recent sales for comparable properties in the same suburb, street type and condition reviewed at address level.
- Rental evidence checked: Current rental listings and recent leases for comparable properties reviewed. Gross and net yield modelled separately.
- Supply pipeline assessed: Development applications, building approvals and new listings for the specific property type in the relevant precinct reviewed.
- Planning and zoning checked: Section 10.7 planning certificate obtained. Zoning and any overlays understood.
- Flood and bushfire risk checked: NSW Government and NSW RFS mapping checked at address level. Specialist reports obtained where relevant.
- Strata records reviewed (for strata properties): Strata inspection report, capital works fund, special levy history and AGM minutes reviewed.
- Building inspection completed: Independent building and pest inspection obtained before exchanging contracts.
- Contract reviewed: Solicitor or licensed conveyancer has reviewed the contract and provided advice.
- Finance assumptions stress-tested: Serviceability reviewed at a rate buffer. Holding cost modelled against realistic vacancy and expense assumptions.
- Tax and structure advice obtained: Accountant and, where relevant, financial adviser have reviewed the structure and tax implications.
- Exit plan considered: Resale liquidity, comparable buyer pool and realistic hold period reviewed.
For detailed guidance on the investment property buying process, Buyers Agency Australia covers the key stages from brief to settlement.
Once the checklist is complete and no material risks are unresolved, you are in a better position to commit. If you would prefer structured support through this process, book a free strategy session to map out the approach before selecting a suburb.
How Buyers Agency Australia Can Help Select and Secure an Investment Property
Buyers Agency Australia provides buyer-side property advisory services across Greater Sydney and nationally, with a focus on strategy-led acquisition for residential investment and, separately, commercial property buyers. Dragan Dimovski, the principal, brings more than 20 years of property experience to the firm's approach.
The process works in five stages:
- Brief definition: Clarify the investment objective, budget, property type, suburb criteria, time horizon and portfolio context before starting any search.
- Market and suburb assessment: Compare market groups, assess suburb fundamentals using current evidence and identify areas that match the brief rather than trending headlines.
- Property sourcing: Source suitable properties, including those not yet publicly listed, and assess each against the investor's brief.
- Value and risk assessment: Conduct comparable sales analysis, assess rental evidence and coordinate building, pest and strata inspections as relevant.
- Negotiation and settlement support: Negotiate on behalf of the buyer and coordinate the purchase process through to settlement.
The NSW Government notes that buyers agents can assist with finding, assessing, negotiating and supporting a purchase, subject to NSW licensing and agency agreement requirements. Buyers Agency Australia operates within that framework.
For Sydney investment property guidance specific to your market, the team covers suburb selection, property-level due diligence and negotiation across the Sydney metro area.
This article is general educational information. Buyers Agency Australia is discussed here as the featured service provider. Readers should obtain professional financial, tax and legal advice suited to their individual circumstances before making any property investment decision.
When a Buyers Agent May Not Be the Right Fit
A self-directed buyer with deep local knowledge, clear investment criteria, existing professional support and the time to conduct thorough research may prefer to manage the search independently. A buyers agent adds most value where the brief is complex, the market is competitive, the buyer has limited local knowledge or where time constraints make thorough independent research difficult. The service should justify itself against the buyer's specific complexity and risk exposure, not be treated as a default.
Understanding what a Sydney buyers agent covers in practice helps investors decide whether representation fits their situation.
Frequently Asked Questions About Sydney Investment Suburbs
What is the best suburb to invest in Sydney?
There is no single best suburb for every investor. The right location depends on budget, strategy, property type, rental demand, supply risk and the role the purchase plays in your portfolio.
Is Western Sydney a good place to buy an investment property?
Western Sydney may suit investors who prioritise relative affordability and yield, but infrastructure delivery risk, construction pipeline and resale liquidity should be assessed before buying in growth precincts.
Should I prioritise capital growth or rental yield in Sydney?
The right priority depends on your cash-flow position, borrowing capacity and time horizon. High-yield suburbs may carry more supply risk, while premium locations may require a longer hold to realise growth.
Are houses or apartments better for Sydney property investment?
Neither is universally better. Houses offer land component and lower strata risk; apartments can deliver stronger gross yields but carry oversupply, strata levy and building defect risks that require careful assessment.
How do I check rental demand in a Sydney suburb?
Review current vacancy rates from a recognised provider such as SQM Research, check active rental listings for comparable properties, and assess recent lease evidence for the specific property type in the immediate precinct.
How can I identify oversupply before buying?
Review development applications and building approvals on the NSW Planning Portal, check the number of competing listings currently on market in the property type, and assess days on market for comparable rentals.
Does proximity to a train station guarantee capital growth?
No. Transport access is one demand driver among many. Infrastructure delivery status, employment depth, supply pipeline, property quality and buyer competition all influence outcomes independently.
What checks should I complete before buying an investment property in NSW?
At minimum: Section 10.7 planning certificate, building and pest inspection, strata records review where applicable, flood and bushfire mapping, comparable sales analysis, contract review by a solicitor and finance stress-testing.
Can a buyers agent help choose the right Sydney suburb?
Yes. A strategy-led buyers agent can help define the brief, compare market groups, source suitable properties and conduct due diligence, though buyers with strong local knowledge and professional support may prefer an independent process.
When is a Sydney investment suburb not the right fit for my strategy?
When the suburb's dominant property type does not match your brief, when the supply pipeline is excessive relative to tenant demand, when the entry cost creates unsustainable cash-flow pressure, or when property-level risks remain unresolved after due diligence.
Choosing the Right Sydney Suburb for Your Investment Plan
The decision process comes down to five steps:
- Define the portfolio objective and budget before researching any suburb or property type.
- Shortlist market groups and suburbs using current evidence on demand, supply, employment, transport and rental conditions.
- Compare property types and supply risks within your shortlisted areas, not just across suburb names.
- Complete property-level due diligence including comparable sales, inspections, strata records, planning checks and rental evidence.
- Decide whether to proceed independently or seek structured buyer-side support based on your complexity, time and risk exposure.
The Sydney property market contains genuine opportunity across different strategy types, but it also contains concentrated risk in specific corridors and property types that require careful navigation. A suburb label is not an investment strategy.
If you want to map out your suburb shortlist and property criteria before committing to a search, book a free strategy session with Buyers Agency Australia. For tailored buyer-side support with experienced investment property guidance, contact the team directly to discuss your investment plan.
 General
A practical framework for identifying the best suburbs to invest in Sydney, covering demand, supply, rental yield, capital...
A buyers agent in Balmain represents the buyer and can help define the brief, source suitable properties, assess value, coordinate due diligence, negotiate or bid at auction, and support the purchase through settlement. Buyers Agency Australia takes a strategy-led approach across residential, investment and selected commercial property decisions. Balmain properties still require individual checks for condition, title, strata, planning, heritage, access and total ownership costs.
You have found a Balmain property that feels right. The price guide looks reasonable, the street is quiet, and you can picture the lifestyle. But the real question is whether the asset fits your goals, sits within your budget, and stacks up against comparable evidence. That question is harder to answer than it looks.
The deeper issue is not simply who can find a property. It is who can test whether it suits your risk tolerance, finance position and intended use before you make an offer or walk into an auction room unprepared.
Balmain sits on a peninsula within Sydney's Inner West, governed by Inner West Council. The suburb includes character houses, terraces, apartments, strata complexes and small commercial lots, and each asset type brings its own title, planning and due diligence considerations. A terrace near the foreshore is a very different purchase from a strata apartment near Rozelle or a commercial tenancy on Darling Street.
Buyers Agency Australia's buying approach is designed to frame each purchase around what the asset needs to do for the buyer, then coordinate search, assessment, negotiation and settlement support from that starting point.
Why Balmain Requires a Property-Specific Buying Strategy
Balmain buying decisions should be property-specific because homes and assets differ by location, condition, title, planning and intended use. The suburb label alone is not a sufficient guide to value, risk or suitability.
According to Inner West Council, Balmain sits at the northern edge of the Inner West Council area, which covers approximately 186,000 residents across a 36 square kilometre footprint. The suburb is a distinct locality from Balmain East, Birchgrove and Rozelle, and buyers should be precise about which part of the peninsula they are assessing.
Several local factors make a property-by-property approach necessary:
- Peninsula form and access: Roads into Balmain converge at limited entry points, which affects accessibility, parking, tradespeople costs and resale appeal depending on the specific street.
- Heritage character and planning controls: Parts of Balmain and Balmain East fall within heritage conservation areas under Inner West Council planning instruments. Controls are property-specific, not suburb-wide, and must be verified through council records or a qualified town planner for each asset.
- Mixed housing stock: Inner West Council community data shows that Balmain has a much higher proportion of medium and high-density dwellings than the broader council area, with separate houses making up a small share of total stock. This shapes both the purchase decision and the due diligence process for strata titles.
- Mixed-use history: Balmain's industrial and maritime past has produced a range of property types, including converted warehouses, small commercial sites and mixed-use lots. Permitted use, zoning and contamination risk must be checked at the individual property level.
- Street-by-street variation: Outlook, natural light, noise, parking, flood exposure and proximity to commercial uses vary substantially from one street to the next. No suburb average captures these differences.
For broader Inner West buying guidance, the considerations above extend across neighbouring suburbs, but Balmain's peninsula geography and heritage density make local, property-level research essential.
What Does a Buyers Agent in Balmain Do?
A buyers agent acts exclusively for the buyer. Unlike a selling agent, who is engaged by and legally obligated to the vendor, a buyers agent is appointed to find, assess, negotiate and help secure a property on the buyer's behalf. The NSW Government confirms that a buyers agent can help search for and evaluate properties, arrange inspections, conduct research, negotiate price and terms, bid at auction, and support the buyer through to settlement.
In NSW, buyers agents must hold a current real estate licence issued under the Property and Stock Agents Act 2002, regulated by NSW Fair Trading. Buyers should verify licence status before signing any agency agreement.
The relationship between buyer and agent is governed by a written buyer's agency agreement, which should clearly set out the services included, fee structure, payment triggers, duration and any conflicts of interest. Understanding the agreement before signing is a basic protection.
From Property Brief to Settlement Support
The acquisition process generally follows this sequence, though the steps may vary for an owner-occupier, residential investor, interstate buyer or commercial buyer:
- Define goals and constraints: Intended use, budget, ownership structure, risk tolerance and timeframe.
- Confirm finance readiness: Pre-approval or formal finance capacity confirmed before active search begins.
- Build the property brief: Target property type, location, condition threshold, must-haves and deal-breakers.
- Search and shortlist: On-market, pre-market and private opportunities reviewed against the brief.
- Inspect and assess: Physical inspection, condition assessment and preliminary evidence review.
- Due diligence coordination: Building and pest inspection, contract review, strata records, planning checks and comparable sales analysis, each conducted by the appropriate qualified professional.
- Offer or auction: Evidence-led negotiation or disciplined auction bidding within a pre-set limit.
- Exchange and settlement support: Coordination with the solicitor or conveyancer through to successful settlement.
No standard timeframe applies. The process depends on the buyer's brief, market conditions, property type and finance complexity.
What a Buyers Agent Does Not Replace
A buyers agent coordinates the acquisition process. That coordination does not replace the advice or services of a solicitor or conveyancer, building inspector, pest inspector, registered valuer, accountant, mortgage broker, town planner, environmental consultant or SMSF adviser. Each professional carries their own scope of responsibility, and buyers should engage the right specialist for each part of the transaction.
How to Assess a Balmain Property Before Making an Offer
The core principle is straightforward: check the asset, the legal right to use it, the income case if applicable, and the total cost of ownership. Every factor in the table below matters only if it changes use, value, risk, cost, liquidity or the buyer's intended outcome.

| Factor |
Evidence to Request |
Professional or Source |
Buyer Decision |
| Property type and title |
Title search, strata plan if applicable |
Solicitor or conveyancer |
Owner-occupier, investor or commercial use? |
| Street position and access |
Physical inspection, council road records |
Buyers agent, council |
Does access affect value or usability? |
| Condition and defects |
Building and pest inspection report |
Licensed building inspector, pest inspector |
Is remediation within budget and appetite? |
| Heritage and planning controls |
Council heritage maps, planning portal |
Town planner, Inner West Council |
Do controls restrict intended use or renovation? |
| Strata records |
Strata records search, levy schedule, AGM minutes |
Strata inspector, solicitor |
Are levies, defects or disputes manageable? |
| Comparable sales |
Recent settled sales, same property type, same street |
Buyers agent, valuer |
Does the asking price reflect market evidence? |
| Rental demand (if investing) |
Current listings, vacancy data, property manager advice |
Property manager, buyers agent |
Is the rent realistic and is vacancy acceptable? |
| Renovation potential |
Council DA history, heritage constraints, costs |
Builder, town planner |
Does renovation improve or complicate the asset? |
| Total ownership costs |
Rates, levies, insurance, maintenance, land tax |
Accountant, strata manager |
Can the buyer sustain holding costs over time? |
| Flood and environmental risk |
Council flood maps, Environment Protection Authority records |
Town planner, council |
Does the site carry an undisclosed risk? |
Which Balmain Property Factors Matter Most?
Street position, outlook, parking, privacy, natural light, layout and physical condition can vary materially from one Balmain street to the next. A ground-floor strata apartment with no parking in a heritage-affected building carries a very different risk and cost profile from a freestanding terrace on a wide, north-facing block.
No single factor is universally most important. Trade-offs between condition, location, price, permitted use and renovation potential should be assessed against comparable properties before an offer is made. If a property has waterfront exposure, foreshore access or any flood risk, a property-specific government map, council record or qualified environmental report should be obtained before proceeding.
Checks for Residential Investors
For buyers pursuing balmain property investment as part of a broader residential portfolio, the assessment requires additional evidence:
- Current rent evidence from comparable tenanted properties, not asking rents from listings.
- Realistic vacancy assumptions, not best-case projections.
- Strata levies, special levy history and sinking fund balance.
- Insurance, rates, land tax liability and ongoing maintenance allowance.
- Renovation costs if the property requires work before tenanting.
- Portfolio concentration: does this asset complement or duplicate existing holdings?
No capital growth, high rental yield or strong cash flow can be promised by any adviser. Any current rental or market figure cited should show source, asset type, date and methodology. If those details are missing, treat the figure with caution.
Checks for Commercial Buyers
For buyers considering office, retail or industrial assets in the Inner West area, commercial property buying support involves a different evidence set. A commercial buyer should review:
- The executed lease, rent ledger, lease expiry date and rent review schedule.
- Tenant quality and covenant strength.
- Net income after recoverable outgoings.
- Permitted use under the current zoning.
- Access, parking, fit-out condition and estimated capital expenditure.
- Vacancy risk and reletting timeframe if the lease expires.
A thorough commercial property due diligence checklist covers these items in detail. Buyers Agency Australia can coordinate the process, but the legal, valuation, building, tax, finance and planning components must be handled by the relevant qualified specialists. For finance considerations, the commercial property finance guide provides useful context on serviceability and loan structures. If you are evaluating commercial acquisition support, understanding how to hire a commercial buyers agent outlines what to look for before engaging.
If your Balmain search includes a commercial asset, book a free strategy session to discuss the brief before committing to a search.
How Do Off-Market and Pre-Market Opportunities Work in Balmain?
A buyers agent may be able to identify properties before they reach broad public listing, but access is not guaranteed, nor does it automatically mean the opportunity is better value or lower risk.
Off-market and pre-market access depends on existing relationships with selling agents, private vendor networks, buyer brief matching and the vendor's willingness to transact without full market exposure. Timing, asset fit and the vendor's circumstances all affect whether a private opportunity proceeds.
| Possible Source |
What It May Provide |
What Is Not Guaranteed |
| Selling agent relationships |
Early sight of a property before listing |
Exclusivity, a discounted price or successful purchase |
| Private vendor conversations |
Direct approach where vendor is considering selling |
Vendor willingness, transparency or fair pricing |
| Buyer brief matching |
Notification when an off-market asset fits the brief |
Availability, condition, clear title or negotiated access |
Off-market does not mean cheaper, better or lower risk. The same due diligence requirements apply regardless of how the property was sourced. Every claim about condition, title, planning, strata and comparable value must still be independently verified.
How Should You Negotiate or Bid for a Balmain Property?
Evidence-led pricing starts before any offer is made. A buyer who enters negotiation or an auction without a clear price limit, independent comparable sales evidence and a defined walk-away point is relying on instinct rather than information.

Pre-auction negotiation can be a useful strategy when vendor circumstances support it, but it requires understanding the contract terms, the vendor's motivation and the strength of the comparable evidence. A pre-auction offer should reflect the same disciplined analysis as any other purchase decision.
At auction, the NSW Government confirms that a buyers agent can bid on a buyer's behalf under a written authority. Auction preparation should include:
- Finance capacity confirmed and pre-approval current.
- Solicitor or conveyancer review of the contract before auction day.
- Building and pest inspection completed, not deferred.
- Comparable sales reviewed and a maximum price set independently of the vendor's price guide.
- A clear walk-away limit agreed before entering the room.
Setting a Price and Walk-Away Limit
The maximum price should reflect finance capacity, comparable settled sales for the same property type, condition-adjusted value based on inspection findings, required works costs, intended use and the strategic value of the asset to the buyer's portfolio. The vendor's price guide, the auctioneer's commentary and the emotional atmosphere of the room are not reliable inputs for a maximum price decision.
Walk-away discipline is not a failure. A buyer who holds to their evidence-based limit protects their financial position regardless of the auction outcome.
Who Should Use a Balmain Buyers Agent?
The value of engaging a buyers agent depends on the buyer's situation, not on a universal recommendation. The NSW Government notes that a buyers agent can help buyers who want independent assistance finding, assessing and purchasing a property.
| Buyer Situation |
Likely Value |
Important Limitation |
| Time-poor professional |
Search, inspections and evidence review handled on their behalf |
Buyer still must approve the brief, strategy and final offer |
| Interstate or overseas buyer |
Local inspection, market knowledge and settlement coordination |
Buyer must still confirm finance, ownership structure and legal advice |
| First-time investor |
Process guidance, due diligence coordination and negotiation support |
Not a substitute for tax, finance or legal advice |
| Portfolio builder |
Data-led property selection and assessment against portfolio strategy |
Agent coordinates; valuation, accounting and legal remain separate |
| Commercial buyer |
Commercial acquisition coordination for office, retail or industrial assets |
Lease, valuation, building, finance and planning remain specialist roles |
| Experienced buyer with time and access |
May choose to manage search and negotiation independently |
Can still engage for negotiation or auction support only if scope allows |
Buyers who have the time, local access, professional network and confidence to manage the full process independently may choose to handle some or all steps themselves. A buyers agent adds the most value where complexity, time pressure, distance or evidence gaps make independent management difficult.
What Should You Check Before Engaging a Buyers Agent?
Before signing a buyer's agency agreement, the NSW Government recommends that buyers understand exactly what services are included, how fees are calculated and what their obligations are. Compare scope and obligations, not just a headline fee.
Licence and registration: Confirm the agent holds a current NSW real estate licence, verifiable through the NSW Fair Trading public register.
Service scope: What is included? Full search, evaluation, negotiation, auction bidding? Which steps are the buyer's responsibility?
Fee structure: How is the fee calculated? When is payment triggered? Is GST included? What happens if no property is purchased?
Conflicts of interest: Does the agent receive any referral fees, commissions or benefits from other parties in the transaction?
Sourcing approach: What channels does the agent use? Are any properties sourced from related parties?
Due diligence responsibilities: Which specialist reports are the buyer's responsibility to commission and fund?
Agreement duration and exit terms: How long does the agreement run? How can it be ended if the relationship is not working?
For buyers considering commercial acquisition support, understanding commercial acquisition and due diligence support and the scope of a Sydney suburb buying strategy for similar Inner Sydney markets can help frame the right questions before the first meeting.
How Buyers Agency Australia Can Help in Balmain
Buyers Agency Australia takes a strategy-led approach to property acquisition, informed by national property investment guidance and designed to connect each purchase decision to the buyer's broader goals rather than treating it as a stand-alone suburb choice. Founded by Dragan Dimovski, who brings more than 20 years of property investment experience, the agency supports buyers across residential, investment and selected commercial acquisitions.
This section explains Buyers Agency Australia's own buyer-side approach and is not an independent ranking of buyers agents. The information here is general in nature and does not constitute personal legal, tax, financial, valuation, lending, planning or SMSF advice.
A Strategy-First Approach to Residential and Commercial Buying
A home purchase, a residential investment and a commercial acquisition are three distinct decisions with different evidence requirements, risk profiles and professional support needs.
For a home purchase, the brief centres on lifestyle fit, condition, title, planning and a sustainable price. For a residential investment property, it shifts to rental evidence, strata health, vacancy assumptions and portfolio fit. For a commercial asset, the brief expands to include lease quality, tenant covenant, net income, permitted use, access, fit-out condition and reletting risk.

Buyers Agency Australia can support all three paths. For commercial buyers seeking office, retail or industrial assets in Sydney and the Inner West, the commercial acquisition and due diligence support service coordinates the search, assessment and negotiation process while ensuring each specialist role is handled by the right professional. The agency's service scope should be confirmed on the official website before engaging, as availability and service details may change.
When This Is Not the Right Fit
Buyers Agency Australia does not replace a solicitor, conveyancer, registered valuer, accountant, mortgage broker, building consultant, town planner, environmental consultant or SMSF adviser. Each of those professionals carries independent obligations that a buyers agent cannot and should not fulfil.
Buyers who are not ready to accept the realistic risks of property ownership, including vacancy, repair costs, lease expiry, refinancing uncertainty, planning changes or fluctuating market conditions, should seek independent financial and legal advice before committing to any acquisition. This limitation is not a disclaimer. It is a practical guide to making a well-supported decision.
Frequently Asked Questions About Buyers Agents in Balmain
1. What does a buyers agent in Balmain do?
A buyers agent in Balmain acts for the buyer, not the seller. Services typically include defining the property brief, searching on-market and private opportunities, arranging inspections, coordinating due diligence, negotiating price and terms, bidding at auction and supporting settlement.
2. Is a buyers agent the same as a selling agent?
No. A selling agent is engaged by the vendor and legally obligated to act in the vendor's interest. A buyers agent is engaged by and obligated to the buyer. The two roles represent opposite sides of the same transaction.
3. Can a buyers agent help me buy an investment property in Balmain?
Yes, a buyers agent can support residential investment property purchases by assessing rental demand, reviewing strata records, coordinating due diligence and providing comparable sales evidence. The agent does not replace a tax accountant, property manager or finance broker.
4. Can a buyers agent access off-market properties in Balmain?
A buyers agent may identify properties before broad public listing through agent relationships and private networks. Access is not guaranteed and depends on timing, asset fit and vendor willingness. Off-market does not automatically mean better value or lower risk.
5. How much does a buyers agent cost in Sydney?
Fees vary by agent, service scope, property type and agreed terms. The written buyer's agency agreement sets out the fee structure, including when payment is triggered and whether GST applies. Buyers Agency Australia quotes fees after understanding the client's goals; no numerical range is published without a current written source.
6. Do I still need a solicitor or conveyancer?
Yes. A buyers agent does not review or execute the contract of sale, provide legal advice on title, strata or planning, or complete conveyancing. A solicitor or conveyancer must be engaged separately for every residential or commercial purchase.
7. Can a buyers agent bid at a Balmain auction?
Yes, provided a written authority is in place as required under NSW law. Effective auction support includes pre-auction contract review, building and pest inspection completion, a confirmed maximum price based on comparable evidence and disciplined bidding within that limit.
8. What should I check before signing a buyer's agency agreement?
Confirm scope, fee structure, payment triggers, GST treatment, conflict-of-interest policy, due diligence responsibilities, agreement duration and exit terms. Verify the agent's current NSW licence through the NSW Fair Trading public register before signing.
9. Can Buyers Agency Australia help with commercial property?
Yes. Buyers Agency Australia supports commercial acquisitions including office, retail and industrial assets. The service coordinates search, assessment and negotiation while requiring buyers to engage their own legal, valuation, finance and planning specialists. Confirm current service availability on the official website.
10. When is a buyers agent not the right fit?
A buyers agent may not add significant value for experienced buyers with sufficient time, local access and professional networks to manage the full process independently. It is also not a substitute for legal, financial, tax, valuation, building, planning or SMSF advice.
Next Steps for Buying Property in Balmain
Before contacting a buyers agent, work through this checklist:
- Define whether the purchase is a home, residential investment or commercial asset.
- Confirm budget, finance pre-approval status, ownership structure and risk tolerance.
- Identify the property factors that are non-negotiable: location, property type, condition threshold, access or other criteria.
- Decide which parts of the process you want support with: full search, due diligence coordination, negotiation, auction bidding or end-to-end management.
- Prepare a written brief covering your goals, timeframe, must-haves and constraints.
- Bring that brief to a conversation with a licensed buyers agent to test whether the service scope fits your situation.
If you are ready to structure a Balmain property search around clear evidence and a defined brief, map out your next property move with a Buyers Agency Australia strategy session. For a direct conversation about a specific Balmain brief or a broader Inner West search, contact the Buyers Agency Australia team to discuss the next step.
 General
Discover how a buyers agent in Balmain helps home buyers and investors with property search, due diligence, negotiation...
A commercial buyers agent in Australia represents the purchaser when acquiring office, retail or industrial property. They help define the acquisition strategy, source opportunities, assess leases and tenant income, coordinate due diligence, negotiate price and terms, and support the transaction through to settlement. The agent does not replace a solicitor, conveyancer, accountant, finance broker, registered valuer, building consultant or licensed financial adviser. The right purchase depends on documented lease, tenant, valuation, finance, ownership and downside evidence.
You have found a commercial property with an attractive advertised yield. The lease looks clean, the tenant seems established, and the location feels right. The question most buyers reach at this point is not whether the property looks good. It is whether the income, the building, the lease terms and the downside scenario hold up once the documents are examined properly.
Buying commercial property is not only a search exercise. It is a sequence of strategy, evidence, finance, negotiation and settlement decisions, each of which can expose or protect your capital depending on how carefully it is managed. Buyers Agency Australia's investment approach is built around exactly that sequence: strategy first, evidence second, and execution only when both stacks up.
This guide covers each stage of the commercial property buying process from asset selection through to settlement. It is general information only and is not personal financial, tax, legal, valuation or SMSF advice.
What Is a Commercial Buyers Agent?
A commercial buyers agent is a licensed property professional engaged by the purchaser to represent their interests across a commercial property acquisition. The agent works exclusively for the buyer across the full process, including strategy definition, asset sourcing, lease and income assessment, due diligence coordination, price and terms negotiation, and transaction management through settlement.
The term buyers agent and buyers advocate are used interchangeably across Australian states and territories. The written agency agreement controls the scope of the engagement, the fee structure and the obligations of both parties. The label alone does not define what is included.
How buyer-side representation differs from a selling agent
The distinction matters because a selling agent is engaged by and paid by the vendor. Their obligation, under general law and relevant state licensing requirements, is to the party who appointed them.

|
Buyers Agent |
Selling Agent |
| Represented party |
Purchaser |
Vendor |
| Payment source |
Buyer (fee or retainer) |
Vendor (sales commission) |
| Primary objective |
Secure the best outcome for the buyer |
Achieve the best sale outcome for the seller |
| Scope |
Strategy, sourcing, assessment, negotiation, settlement |
Marketing, listing, offers, sales management |
State and territory licensing rules vary across Australia. In NSW, for example, real estate agents and buyers agents must hold a current licence issued under the relevant Property and Stock Agents Act. Buyers should confirm their agent holds the applicable licence for the jurisdiction where the transaction is taking place. Independent legal advice on the written agency agreement is recommended before proceeding.
For practical guidance on investment property buyers agent guidance, it helps to understand what the written engagement actually covers before the search begins.
Who Should Consider Buying Commercial Property?
Commercial property suits a range of buyers, but suitability depends on individual circumstances, not a general profile.
Business owners purchasing premises for their own operations gain control over their tenancy and may build an appreciating asset over time. The suitability depends on capital, lease alternatives, business stability and cash requirements.
Commercial investors seeking income-producing assets are drawn to longer lease terms and the potential for net leases where the tenant pays outgoings. Risk tolerance, portfolio concentration, finance capacity and time available for management all affect suitability.
SMSF trustees should be aware that a self-managed superannuation fund may acquire certain business real property subject to strict conditions under the Superannuation Industry (Supervision) Act and ATO guidelines on SMSF property. Licensed financial advice from a qualified SMSF adviser is required before proceeding.
Portfolio builders adding commercial assets to an existing residential portfolio need to account for different financing conditions, tenant dynamics and management complexity.
Moneysmart notes that borrowing to invest carries significant risks including income, interest-rate, capital and liquidity exposure. Consulting a finance broker, accountant and solicitor before committing is not optional, it is part of a sound acquisition process.
Which Type of Commercial Property May Suit Your Strategy?
Office, retail and industrial are distinct asset classes. Each carries different demand drivers, lease structures, building requirements and exit considerations. The asset class question should be answered before evaluating any individual property.
Office, retail or industrial: what changes the assessment?
|
Office |
Retail |
Industrial |
| Key demand drivers |
Employment density, transport, tenant consolidation |
Trade area population, foot traffic, anchor tenants |
Freight networks, e-commerce growth, clear-span usability |
| Lease complexity |
Moderate, gross or net leases, fitout incentives |
High, disclosure obligations, outgoings, trading hours |
Generally lower, often net leases with long terms |
| Vacancy exposure |
Higher for secondary-grade assets |
Location and anchor-dependent |
Currently lower, with vacancy stabilising in 2026 |
| Building requirements |
HVAC, services, NCC compliance, end-of-trip |
Car parking, signage, access, building presentation |
Hardstand, clear-span height, loading docks, zoning |
| Future reletting test |
Would another tenant type use this floor plate? |
Would a different retail category take this tenancy? |
Could this building serve a different freight or storage profile? |
CBRE's research estimated Australian commercial investment volumes of around $44 billion in 2026, reflecting improving confidence across all three sectors as borrowing costs stabilised. That aggregate figure does not tell a buyer whether a specific asset at a specific price and lease term is sound, which is exactly what the asset-level assessment must answer.
For buyers seeking commercial property acquisition support across these three asset classes, the starting point is always the strategy, not the asset.
How Do You Set a Commercial Property Buying Strategy?
The strategy defines what you are buying, why, and what evidence would confirm or reject any individual opportunity. Starting with an advertised property and working backwards almost always produces a weaker outcome than starting with a written brief.
Income, growth, lease security and portfolio fit
A target yield cannot be assessed in isolation. A 7% advertised yield on a property with an expiring lease, a single tenant, an aging building and owner-borne outgoings may represent a worse income position than a 5.5% yield on a modern net lease with five years remaining and annual CPI reviews. The income picture only emerges when outgoings, vacancy allowance, incentives and capital expenditure are factored in.
Your acquisition brief should address each of the following before you inspect anything:
- Investment objective: income, capital growth, or portfolio diversification
- Asset class preference: office, retail or industrial, with reasons
- Target market and location criteria: population, freight, employment or trade area drivers
- Budget and ownership structure: individual, company, trust or SMSF
- Hold period: short, medium or long-term exit strategy
- Income target and vacancy tolerance: minimum passing yield, acceptable downtime
- Risk limits: maximum lease expiry exposure, minimum tenant covenant standard
- Exit pathway: sale, refinance, owner-occupation or portfolio aggregation
If you want help completing that brief before committing to a search, book a free strategy session with a specialist before you inspect a single property.
How Do You Research Commercial Property Opportunities?
Commercial property sourcing spans on-market listings through commercial portals, pre-market conversations with selling agents, and off-market approaches through buyer-side networks. Off-market access is a legitimate sourcing channel but it does not automatically produce better value. Every opportunity, regardless of how it is sourced, must clear the same evidence standard.
A practical screening sequence before inspection
Run every opportunity through this filter before committing to a formal inspection or requesting documents:

- Strategy fit – Does the asset class, market and income profile match your brief?
- Location – Do the tenant demand drivers (employment, freight, trade area) support the location?
- Tenant – Is there a named tenant, a lease in place, and a public record to assess covenant?
- Lease – What is the remaining term, option structure and rent review mechanism?
- Building – Is the building age, condition and configuration consistent with current tenant needs?
- Income – Does the advertised income match the executed lease, net of owner-borne outgoings?
- Valuation – Does comparable sales evidence support the asking price at the stated yield?
- Exit – Would another tenant type, buyer type or owner-occupier want this asset at expiry?
If any step surfaces a material unknown, pause and gather the evidence before proceeding. For practical commercial property investing steps, the discipline of screening early avoids the cost of late-stage due diligence failures.
What Should You Check in a Commercial Property Due Diligence Review?
Due diligence is not a single event. It is a structured review across legal, financial, physical and regulatory dimensions, each of which requires a different professional.
The following checklist covers the core items a buyer should request and verify. It does not replace a solicitor, conveyancer, building consultant, valuer or environmental specialist.
| Category |
Item to Review |
| Lease documents |
Executed lease, all variations, disclosure statements |
| Rental income |
Rent ledger, arrears history, current passing rent |
| Outgoings |
Schedule, recoverable vs owner-borne items, reconciliation |
| Incentives |
Rent-free periods, fit-out contributions, cash incentives |
| Tenant security |
Bank guarantee, personal guarantee, bond amount |
| Make-good obligations |
Lease clause, cost estimate, building condition at entry |
| Permitted use |
Lease clause versus council planning and zoning consent |
| Title |
Certificate of title, encumbrances, easements, covenants |
| Zoning |
Local environmental plan, permitted uses, development consent |
| Building condition |
Independent building and services report |
| Environmental |
Phase 1 or Phase 2 environmental assessment where relevant |
| Insurance |
Current policy, notifiable events, claims history |
| Maintenance obligations |
Who maintains structure, roof, HVAC, car park and services |
Lease and tenant due diligence
The lease is the primary income document in a commercial property acquisition. It is not a background document, it is the asset. Before any offer is made, the following questions need documented answers:
Passing rent vs market rent. What is the tenant currently paying, and what would an equivalent space achieve on the open market today? A below-market rent expiring in 12 months creates a very different income forecast than a rent already above market with four years remaining. A registered valuer or experienced commercial leasing adviser can benchmark this.
Effective rent. If the landlord granted a six-month rent-free period or a $200,000 fit-out contribution at lease commencement, the effective rent over the initial term is lower than the face rent. The calculation matters for both valuation and income planning.

Rent reviews. Fixed percentage, CPI, market review or ratchet clauses all produce different income trajectories. A five-year lease with a single market review at year three carries more income uncertainty than annual CPI reviews with a ratchet clause.
Lease expiry stress test. Model the downside: if the tenant does not renew, what does vacancy for six or twelve months cost the owner? Include make-good costs, reletting incentives, a leasing agent commission and any fit-out contribution for the incoming tenant. This is where commercial property investment considerations often separate well-assessed assets from problematic ones.
NSW lease disclosure requirements, which include the lease term, rent reviews, outgoings, fit-out obligations and planned disruptions, are described in NSW Small Business Commissioner guidance. Rules vary by state. Confirm the applicable disclosure obligations with a solicitor in the relevant jurisdiction.
Building, title, zoning and environmental checks
The buyers agent may coordinate the collection of building reports, title searches, planning certificates and environmental assessments. They do not replace the independent professionals who interpret those documents.
Zoning and permitted use should be verified against the current local environmental plan and any development consent, not against the listing description or the vendor's representations. business.gov.au guidance on choosing a business location recommends checking council requirements and zoning before committing. This principle applies equally to investment buyers.
A future reletting test should also run in parallel: if the current tenant's permitted use is narrow, would a different business category be able to occupy the same space? Access, power, clearance, HVAC, parking and loading are all factors that affect the reletting pool at lease expiry.
How Much Finance and Capital Do You Need to Buy Commercial Property?
There is no universal deposit or loan-to-value ratio for commercial property in Australia. Lenders assess the borrower, the asset, the lease, the tenant covenant, the location, the independent valuation and the interest cover position before determining lending terms. A strong net-lease asset with a creditworthy tenant will attract different terms to a vacant building or a short-lease property.

Commercial property costs beyond the purchase price
Building the full capital requirement before making an offer avoids the risk of a finance gap at settlement. The following items should be estimated before any offer is made:
- Deposit – as required by the contract and lender
- Stamp duty – imposed by state and territory governments at varying rates
- GST – may or may not apply depending on the transaction structure; seek ATO and accountant advice
- Legal and conveyancing fees – solicitor review of contract, lease, title and searches
- Building condition report – independent inspector
- Environmental assessment – if required by asset type or history
- Independent valuation – required by most lenders
- Finance establishment costs – application, valuation, legal fees
- Land tax – varies by state, ownership structure and asset type
- Post-settlement reserves – vacancy allowance, maintenance, capital works
Stamp duty is generally imposed by state or territory governments on property transactions, with tax treatment depending on the circumstances and the ownership structure, as described in business.gov.au tax guidance. Confirm the applicable duty and GST position with an accountant and the relevant state revenue authority before exchanging contracts.
Moneysmart describes borrowing to invest as high risk, with exposure across income, interest-rate, capital and liquidity dimensions. Adequate cash reserves beyond the purchase itself are a meaningful part of a sound commercial acquisition plan.
How Is Commercial Property Valued?
Commercial property valuation is primarily income-based. The most widely used method applies a capitalisation rate to the net operating income of the property.
Gross yield = Annual gross rent divided by purchase price, expressed as a percentage.
Net yield = Net operating income (after owner-borne outgoings) divided by purchase price, expressed as a percentage.
Capitalisation rate (cap rate) = The rate of return a buyer requires from the net income of the property. Lower cap rates reflect higher asset quality, longer leases and stronger tenant covenants. Higher cap rates reflect greater risk, shorter leases or secondary locations.
For a hypothetical example (for illustration only, not a valuation conclusion):
- A property generating $80,000 net annual income priced at $1,200,000 implies a cap rate of 6.67%.
- If the owner pays $15,000 in outgoings, the gross income needed to achieve the same net position is $95,000.
Why net income matters more than headline yield
Advertised yields are almost always gross figures. Once owner-borne outgoings, a realistic vacancy allowance, incentive amortisation and capital expenditure are factored in, the effective net income can be materially lower.
A rent-normalisation check is worth running before accepting any headline number: compare the current passing rent with evidence of achievable market rent at expiry, accounting for current incentive levels in the local leasing market. The Australian Property Institute's valuation insights emphasise that evidence-based assessment across income, condition, location, supply and demand is the correct standard for commercial property analysis.
A registered valuer should be engaged for any formal valuation opinion. Using comparable sales evidence without a professional assessment carries its own risks, particularly when lease terms, outgoings or building condition differ between properties.
For broader commercial buying strategy guidance, working from net income to a warranted cap rate before arriving at a maximum price is a more defensible approach than reverse-engineering a price from an advertised yield.
How Do You Negotiate and Buy Commercial Property?
Negotiation on commercial property covers more than purchase price. The conditions, settlement timing, lease documentation requirements, access arrangements, and risk allocation between buyer and vendor are all negotiable terms.
An evidence-based offer starts with a maximum price derived from the verified net income, an appropriate cap rate for that asset quality and location, and a realistic downside model. Never lead with the maximum. The vendor's asking price is a starting position.
Key negotiation considerations:
- Conditions precedent – finance, valuation, building inspection, lease review and solicitor approval are standard conditions; negotiate the period and scope
- Document completeness – require all lease documents, variations, arrears ledger, outgoings schedules and title information before waiving conditions
- Lease alignment – if rent, outgoings or tenant obligations are misrepresented in the information memorandum, that is grounds for renegotiation before exchange
- Walk-away triggers – proceed if evidence supports the income and price; renegotiate if outgoings are owner-borne and not disclosed; seek expert input if the lease contains unusual make-good or assignment clauses; withdraw if the tenant is in arrears, the building has major defects, or the downside model is unworkable
Solicitor review of the contract of sale, conditions, and lease documentation before exchange is not optional. The buyers agent may coordinate the process, but legal interpretation requires a qualified practitioner.
What Happens During Commercial Property Settlement?
Settlement is a coordinated sequence of legal, financial and administrative steps. The exact requirements vary by state and transaction structure.
- Contract exchange – deposit paid, conditions period begins
- Finance approval – lender assessment, valuation ordered
- Inspections and searches – building report, title search, planning certificate, environmental checks
- Legal review – solicitor reviews contract, lease, title, searches and any outstanding matters
- Conditions satisfaction – each condition cleared in writing before the due date
- Settlement preparation – solicitor calculates settlement figures, lender prepares drawdown
- Title transfer – title transferred at settlement, lender registers mortgage
- Post-settlement handover – keys, lease copies, rent records, insurance, outgoing notices and tenant communications transferred from vendor to buyer
If the property is tenanted, the settlement handover package should include all executed lease documents and variations, a current rent ledger, confirmation of the bond or bank guarantee amount, the last outgoings reconciliation, and any notices outstanding between landlord and tenant.
How Can Buyers Agency Australia Help With a Commercial Property Purchase?
Buyers Agency Australia provides buyer-side advisory and acquisition services for commercial and residential property across Australia. The commercial service is designed for investors, business owners and SMSF trustees seeking office, retail or industrial assets.
Dragan Dimovski, founder and principal property investment advisor, brings more than 20 years of personal property investing experience to the advisory process. The team's stated approach centres on strategy-led selection, data-driven assessment, off-market access and end-to-end buyer-side coordination from brief through settlement.
How the commercial buyers agent service maps to the buying process:
| Buying Stage |
Buyers Agency Australia Role |
| Strategy |
Acquisition brief, asset class selection, market and budget parameters |
| Sourcing |
On-market, pre-market and off-market opportunity identification |
| Assessment |
Lease review, income analysis, comparable sales, downside modelling |
| Due diligence |
Coordinating building, legal, valuation and environmental reviews |
| Negotiation |
Evidence-based price and terms negotiation on the buyer's behalf |
| Settlement |
Transaction management, condition clearance, settlement coordination |
Buyers Agency Australia publishes this guide and provides buyer-side property advisory services. Service scope, availability and engagement terms should be confirmed directly with the team before proceeding.
What the buyers agent does not replace: solicitor and conveyancer advice, independent valuation, licensed financial advice, SMSF advice, tax advice from a registered accountant, building inspection, and environmental assessment.
When a commercial buyers agent may not be the right fit
Full-service buyer-side support is not the right fit for every commercial acquisition. An experienced commercial investor with deep local market knowledge, adequate time, a clear acquisition brief and an established team of legal, tax, finance, valuation and building advisers may prefer to manage the process directly. The value of buyer-side engagement is highest when one or more of those elements is absent.
What Risks and Professional Advice Should You Consider?
Commercial property carries real risks. Understanding them before committing capital is part of sound decision-making.

| Risk |
Evidence to Examine |
Mitigation Direction |
| Vacancy |
Lease term, options, local leasing demand |
Stress test downtime cost before offer |
| Tenant default |
Arrears history, financial position, security held |
Require bank guarantee, assess covenant |
| Lease expiry |
Remaining term, market rent comparison, reletting cost |
Model downside before exchange |
| Interest rates |
Loan serviceability at higher rates |
Confirm cover ratio with finance broker |
| Valuation variance |
Independent valuation vs asking price |
Make valuation a condition precedent |
| Illiquidity |
Days on market, buyer demand for this asset type |
Consider exit options at acquisition |
| Building defects |
Age, condition report, HVAC and roof |
Engage independent building consultant |
| Environmental risk |
Site history, environmental assessment |
Phase 1 or Phase 2 assessment where relevant |
| Zoning change |
Current permitted use, council planning |
Confirm with solicitor and local council |
| Tax and structure |
GST, stamp duty, land tax, deductibility |
Seek advice from accountant and ATO guidance |
| SMSF conditions |
SIS Act, business real property rules |
Licensed financial adviser and ATO guidance |
This article is general information only. It is not personal financial, tax, legal, valuation or SMSF advice. Readers should seek advice from appropriately qualified professionals before making any property investment decision.
Frequently Asked Questions About Buying Commercial Property in Australia
What does a commercial buyers agent do?
A commercial buyers agent represents the purchaser in an office, retail or industrial acquisition. They provide strategy definition, opportunity sourcing, lease and income assessment, due diligence coordination, price and terms negotiation, and settlement management on the buyer's behalf.
What is the difference between a commercial buyers agent and a selling agent?
A selling agent is appointed by and paid by the vendor. A buyers agent is appointed by and paid by the purchaser. The written agency agreement and relevant state disclosure obligations define each party's duties. Independent legal advice on your agency agreement is recommended.
What should I check in a commercial property lease?
Review the executed lease and all variations, confirm the remaining term and option periods, check rent review mechanisms, identify owner-borne outgoings, examine make-good obligations, permitted use clauses, assignment rights, security instruments and any arrears or incentives outstanding.
What is the difference between gross and net commercial property yield?
Gross yield divides annual rent by purchase price before deducting expenses. Net yield divides net operating income (after owner-borne outgoings) by purchase price. Net yield is the more meaningful figure for income planning. The calculation basis should always be disclosed and verified against the executed lease and outgoings schedule.
How much deposit do I need for a commercial property loan?
There is no universal amount. Lenders assess the borrower's financial position, the asset quality, the lease and tenant covenant, the independent valuation, the location and the interest cover ratio. A qualified finance broker can advise on realistic lending parameters for a specific asset and borrower profile.
Can an SMSF buy commercial property in Australia?
An SMSF may be able to acquire certain business real property subject to strict conditions under the Superannuation Industry (Supervision) Act and ATO guidance. This is a complex area. Advice from a licensed financial adviser with SMSF expertise and review of ATO SMSF guidance is required before proceeding.
Is a high commercial property yield always better?
No. A high yield may reflect a short remaining lease, a weak tenant covenant, high owner-borne outgoings, a secondary location or a building requiring capital expenditure. Yield must be assessed alongside tenant quality, lease term, outgoings, vacancy risk and a verified valuation.
When should I walk away from a commercial property?
Withdraw or renegotiate when: the independent valuation does not support the asking price; the tenant is in arrears or the security is insufficient; the make-good or environmental position is unresolved; the permitted use is too narrow for alternate tenants; or the lease expiry downside model produces an unacceptable result.
Does off-market commercial property mean better value?
Not automatically. Off-market sourcing expands the opportunity set but does not guarantee a price advantage. Every opportunity, however it is sourced, must clear the same evidence standard: lease, income, valuation, building and exit.
When is a commercial buyers agent not the right fit?
Experienced investors with established local market knowledge, clear acquisition criteria and a complete advisory team covering legal, tax, finance, valuation and building may prefer to manage the process independently. Buyer-side support adds the most value when experience, time, local networks or specialist knowledge is limited.
What Should You Do Before Making a Commercial Property Offer?
Before submitting any offer on a commercial property, confirm the following:
- Your written acquisition brief is complete and the property matches it
- The executed lease and all variations are in your hands and reviewed by a solicitor
- Passing rent is confirmed against the rent ledger, not the information memorandum
- Owner-borne outgoings are identified and the net income is calculated
- A lease expiry downside model has been run, including vacancy, make-good and reletting costs
- Independent building and environmental advice has been obtained or conditions are structured to allow it
- Finance indicative terms are confirmed with a broker and a valuation condition is included
- Your maximum price is derived from net income and a warranted cap rate, not the asking price
- A solicitor has reviewed the contract of sale before exchange
For investors ready to move from research to acquisition, national property buying guidance covers the full scope of buyer-side support across commercial and residential markets.
If you want a structured starting point, map out your next property move with a strategy session designed around your specific commercial acquisition objectives. Or contact the team directly to discuss your brief and how buyer-side support can fit your process.
This article is published by Buyers Agency Australia and is general information only. It does not constitute personal financial, tax, legal, valuation or SMSF advice. Readers should obtain advice from appropriately qualified professionals before making any property investment or acquisition decision. Service scope, availability and engagement terms should be confirmed directly with Buyers Agency Australia before proceeding.
 General
Learn how to buy commercial property in Australia with buyer-side guidance on leases, yields, due diligence, finance, negotiation...
A buyers agent in Paddington, Sydney can represent you through property search, comparable-sales research, inspections, due diligence coordination, negotiation, auction bidding and settlement support. The right process starts with your brief, budget and intended use, not with a listing.
Paddington's heritage conservation context and NSW auction rules make property-specific checks essential. A successful NSW auction bid carries no cooling-off period, so finance, contract and inspection decisions should be settled before bidding begins.
Picture the scene: you have spent several evenings comparing Paddington terraces and apartments online, trying to reconcile guide prices, renovation scope, strata levies and auction campaign timelines. The suburb feels right. The real question is whether a specific property fits your budget, purpose, risk tolerance and long-term plan.
That distinction matters. Paddington's Victorian streetscapes are protected by heritage conservation controls that directly affect what you can build, extend or alter. Strata exposure varies between properties. Auction clearance rates can be high, and a winning bid in NSW is legally binding from the moment the hammer falls. Getting the sequence right before you make an offer or raise a paddle is where disciplined buyer-side support earns its place.
This guide explains the Paddington buying process and the stated approach of Buyers Agency Australia. It is not legal, tax, financial, valuation, building or pest advice. Engage qualified professionals for those roles.
Why buyers choose Paddington, Sydney
Paddington sits in Sydney's Eastern Suburbs, approximately three kilometres from the CBD and within the Woollahra local government area. The suburb is widely recognised for its Victorian terrace rows stepping down sloping streets, its mix of boutique retail and hospitality, and its proximity to Centennial Park, the Sydney Cricket Ground and the broader Eastern Suburbs lifestyle corridor.
The housing mix is dominated by terraces and semi-detached homes on narrow lots, with a secondary layer of strata apartments in smaller boutique blocks. Each property type creates a different due diligence requirement, a different holding-cost structure and a different renovation risk profile. That variety is what makes a property-specific assessment framework more useful than a suburb-level summary.
| Buyer type |
What Paddington typically offers |
Key consideration |
| Owner-occupier |
Character home, walkable lifestyle, inner-city access |
Heritage controls limit some renovation work; parking is often scarce |
| Residential investor |
Established rental demand in an inner-Sydney suburb |
Rental evidence, strata levies and holding costs must be checked property by property |
| Portfolio builder |
Potential for a long-term hold in a tightly supplied market |
Asset role, finance structure and exit strategy should be confirmed before search |
| Interstate buyer |
Remote purchase with delegated search and inspection support |
Local coordination and specialist inspection are essential before exchange |
What Paddington's location and housing mix mean for buyers
Paddington sits within the Eastern Suburbs Sydney corridor, with convenient road and bus connections to the CBD, nearby hospitals and employment centres. The housing stock centres on two- and three-storey terraces and semi-detached homes, often on lots of 100 to 200 square metres or narrower. Apartment buildings in Paddington tend to be older boutique blocks rather than high-rise developments.
Parking is limited in many streets. Access via rear lane or courtyard varies significantly by property. These physical attributes are worth assessing before a shortlist is formed, because they affect both liveability and resale appeal for different buyer cohorts.
How heritage context can change the buying brief
A significant portion of Paddington sits within a heritage conservation area governed by Woollahra Council planning controls. Heritage NSW records the Paddington Urban Heritage Conservation Area as a recognised conservation area of state significance, reflecting the suburb's coherent Victorian built form and its historic development pattern.
That heritage status does not mean renovation is impossible, but it does mean that alterations, additions and changes to facades, rooflines and materials are subject to council assessment against the relevant development control plan provisions. A buyer planning to extend, reconfigure or alter a Paddington terrace or semi needs to verify the exact heritage and planning status of the target address through the relevant council and NSW Planning Portal resources before making renovation assumptions or pricing that work into an offer.
Is Paddington suitable for a home or investment property?
Suitability depends on the individual property, the buyer's intended use, finance position, risk tolerance and holding period. Paddington is not automatically the right market for every strategy. A terrace requiring significant structural work carries a different risk profile than a renovated apartment with a clear strata history. An investment brief focused on cash flow must account for strata levies, council rates, insurance, maintenance and finance costs alongside any rental evidence.
The property's condition, strata or title situation, heritage status, price evidence and intended role should all pass assessment before a budget commitment is made.
What does a buyers agent in Paddington actually do?
A buyers agent in Paddington represents the buyer exclusively. As the NSW Government confirms, a buyers agent or buyers advocate can help you find, assess, inspect and negotiate a property purchase, and can bid at auction on your behalf. They do not replace a solicitor, conveyancer, lender, accountant, registered valuer, building inspector or pest inspector. For what a Sydney buyers agent covers in practice, the service sequence typically moves through the following stages.

| Stage |
Buyer decision point |
Professional boundary |
| Brief development |
Goals, budget, property type, intended use approved |
Finance position confirmed by lender or broker |
| Property search |
Shortlist criteria applied; access to listed and pre-market opportunities explored |
Legal and tax structure confirmed by solicitor and accountant |
| Inspection and assessment |
Comparable sales reviewed; condition, price and fit assessed |
Building and pest reports ordered from qualified inspectors |
| Due diligence coordination |
Heritage, planning, strata, title and contract checks coordinated |
Solicitor or conveyancer reviews contract; inspector reviews condition |
| Negotiation or auction bidding |
Offer submitted or bid placed within a pre-agreed maximum price |
Contract signed subject to solicitor review (not applicable at auction in NSW) |
| Settlement support |
Coordination through to completion |
Conveyancer manages settlement; lender funds the purchase |
From property brief to shortlist
The search process starts with a documented brief covering budget, finance readiness, property type, location boundaries, non-negotiables and intended use. A clear brief filters out properties that do not serve the buyer's actual strategy, saving both time and the risk of emotional attachment to the wrong asset.
For Paddington, relevant brief parameters might include whether terraces or apartments are in scope, whether the buyer can accept strata exposure, whether heritage-restricted renovation is acceptable, and whether a rear courtyard or parking space is required. These decisions shape the shortlist before the first property is inspected.
Assessing price, condition and fit
A buyers agent can review comparable sales from recognised datasets, assess a property's condition against the buyer's renovation tolerance, and evaluate the contract context before recommending an offer position. This is a market assessment informed by available evidence, not a formal property valuation. A registered valuer provides a formal valuation; a buyers agent provides buyer-side analysis to support a decision.
For investors, the assessment should also consider the investment property buying process including rental evidence from current comparable leases, strata levy schedules, and the full holding-cost picture rather than headline yield estimates.
Negotiation, auction bidding and settlement support
A buyers agent can represent you in private treaty negotiation, expressions of interest processes, and at auction. The agent acts on your instructions, within an agreed price limit and under documented authority. Settlement coordination may include liaising with solicitors, conveyancers, lenders and other parties, but the agent does not replace those professionals.
How should you assess a Paddington property before making an offer?
A disciplined property assessment applies a fit-before-price test. A property should not progress because it is within budget alone. It should first demonstrate that it fits the buyer's brief, passes a physical condition check, carries supportable price evidence and suits the intended use. Buyers seeking strategy-led property advice before active search often find they refine their brief significantly during this stage.
Property type, condition and renovation scope
Terraces in Paddington range from unrenovated shells requiring full structural and services work to fully updated homes commanding a significant premium. Semi-detached homes carry similar variables. Apartments introduce strata considerations: levy levels, special levies, by-laws, defect history and the building's maintenance fund all affect the true cost of ownership.
Before any renovation scope is priced into an offer, a buyer should obtain a report from a qualified building inspector and verify the property's heritage and planning status through council and the NSW Planning Portal. An inspection report does not constitute a legal compliance certificate, a repair quotation or a future-risk guarantee.
Comparable sales and valuation evidence
Comparable sales should be dated, genuinely similar in property type, size, condition and location, and drawn from recognised sources. Broad suburb medians can obscure the difference between a renovated terrace and an unrenovated one on the same street. A buyers agent's market assessment is not a formal valuation; where a bank, lender or decision-making process requires a formal figure, a registered valuer should be engaged.
Investment fit, rental evidence and holding costs
For investment buyers, rental evidence should come from current comparable leases, not headline estimates. Holding costs should be calculated across strata levies, council rates, insurance, maintenance allowances and finance costs. The financial implications of tax structure, depreciation and cash flow require input from a qualified accountant or licensed financial adviser. A buyers agent coordinates property assessment; financial and tax advice sits with the appropriate licensed professional.
Buying off-market property in Paddington
Off-market and pre-market opportunities exist alongside public listings in most established Sydney suburbs. A buyers agent with active relationships in the Paddington market may learn of properties before they are listed, or may be made aware of private sale situations that do not reach public portals. Buyers Agency Australia describes off-market sourcing access as part of its buyer-side service, though access depends on current relationships, seller circumstances and market timing.
Important caveats apply. Off-market does not automatically mean better value, less competition or reduced risk. A private opportunity still requires the same building and pest inspections, heritage and planning checks, strata review, contract review and comparable-sales analysis as any listed property. Due diligence is not optional because a transaction is private.
| What off-market means |
Possible benefit |
Key limitation |
| Property not yet or not publicly advertised |
Reduced competition at the point of first contact |
Seller still controls terms, timing and price expectations |
| Pre-market: offered to select buyers before public campaign |
Early access before broader interest builds |
Agent relationships, not buyer demand, drive access |
| Genuine private sale |
No public campaign; negotiated directly |
Same due diligence required; no guarantee of favourable pricing |
How to negotiate or bid on Paddington property
Paddington properties sell through private treaty, expressions of interest and auction. Each method has a different evidence requirement, a different risk profile and different legal consequences.

Private treaty offers
A private treaty offer is made in writing and may include conditions such as finance approval, building and pest inspection, and a review period. The NSW standard cooling-off period of five business days generally applies to residential purchases (with some exceptions), as confirmed by NSW Fair Trading. Comparable sales, an agreed maximum price and solicitor review of the contract should all precede the offer. A buyers agent can submit and negotiate the offer on the buyer's written authority.
Expressions of interest
Expressions of interest (EOI) processes vary by vendor and selling agent. A buyer should clarify the deadline, deposit expectations, whether the process is confidential, and whether a contract exchange follows immediately or after further negotiation. EOI processes can close quickly and conditions may be limited. Solicitor review of the contract before submitting an EOI is strongly advisable.
Auction bidding in NSW
Auctions in NSW are governed by state rules. Bidders must register before the auction. The contract is reviewed and the deposit is prepared before bidding starts. As the NSW Government confirms, a successful auction bid in NSW is unconditional: there is no cooling-off period, and exchange occurs at the fall of the hammer. Finance must be unconditionally approved, all inspections completed and a maximum bid price agreed in writing before the auction day. Emotional discipline under live auction conditions is where representation from an experienced buyers agent can provide practical value.

What due diligence should you complete before buying in Paddington?
The specific checks required depend on the exact property address, type and condition. The following table sets out the primary categories. It is not exhaustive for every situation.

| Check |
Risk addressed |
Responsible professional |
Decision point |
| Building and pest inspection |
Structural defects, timber pest damage, moisture issues |
Qualified licensed inspector |
Before making an offer or before auction day |
| Strata records and levy schedule |
Special levies, defects, disputes, by-laws, maintenance fund |
Solicitor, conveyancer or strata report provider |
Before exchange |
| Title search |
Encumbrances, easements, caveats |
Solicitor or conveyancer |
Before exchange |
| Contract of sale review |
Conditions, inclusions, sunset dates, vendor warranties |
Solicitor or conveyancer |
Before making an offer |
| Planning and zoning check |
Permitted uses, floor space ratio, setbacks, overlay controls |
Buyer or buyers agent with council and NSW Planning Portal |
Before finalising renovation assumptions |
| Heritage and conservation status |
Controls on alterations, materials, additions |
Heritage NSW and relevant council |
Before exchange and before any renovation is costed |
| Flood and hazard assessment |
Flood risk, contamination, proximity to known hazards |
Relevant council flood maps and specialist reports |
Before exchange |
| Finance condition |
Unconditional approval, valuation, LVR compliance |
Licensed lender or mortgage broker |
Before exchange (or before auction) |
| Insurance |
Building and landlord insurance scope |
Licensed insurer or broker |
Before settlement |
Building and pest inspections
A building and pest inspection should be conducted by an appropriately qualified inspector before exchange or before bidding at auction. The report will identify visible defects, evidence of timber pest activity and accessibility limitations at the time of inspection. It does not constitute a legal compliance certificate, a repair quotation or a guarantee against future defects. For Paddington terraces with shared walls and heritage fabric, a specialist report covering older building materials and heritage elements is advisable.
Strata, title and contract checks
For apartments and any strata property, the strata records reveal the levies, the administrative and capital works fund balances, minutes of recent meetings, outstanding special levies, any ongoing defect disputes and registered by-laws. These records should be reviewed by a solicitor or conveyancer. Unanticipated special levies can materially change the cost of ownership and should be identified before exchange.
Planning, heritage and property-specific risks
Planning status, heritage overlays, flood risk and other hazard considerations must be checked at the address level through the relevant council, the NSW Planning Portal, Heritage NSW and appropriate hazard mapping tools. No general statement about Paddington's planning environment substitutes for address-specific searches on the property you intend to purchase.
Buyers agent fees and service options in Sydney
Buyers agent fees in Sydney vary by service scope, engagement structure and individual agreement. The common structures are set out below. Buyers Agency Australia's fixed-fee positioning is described in its current brand material, but specific fee figures should be confirmed directly with the team, as no official pricing page was independently verified for this article.
| Fee structure |
How it works |
Buyer consideration |
| Fixed fee |
A set dollar amount agreed at engagement |
Clarity on total cost; confirm GST, inclusions and exclusions in writing |
| Percentage of purchase price |
Fee calculated as a percentage of the final price |
Incentive structure differs; confirm whether the fee applies to the purchase price or list price |
| Staged or milestone fee |
Fees attached to search commencement, exchange and settlement |
Useful for mapping cash flow; check what happens if no purchase proceeds |
| Search-only or negotiation-only |
Partial service covering one stage |
Lower scope; confirm what is not included and who handles other steps |
What a written buyers agency agreement should clarify
Before signing, a buyers agency agreement should confirm: the service scope; the engagement term and any exclusivity period; the fee trigger (search commencement, exchange or settlement); what is included and excluded; auction attendance costs; inspection or travel costs; referral arrangements and any conflicts of interest; termination rights and the position if no purchase proceeds within the engagement period.
Obtaining all fee, GST, scope, exclusion and termination terms in writing protects the buyer regardless of the service structure chosen.
Licensing and role boundaries
NSW buyers agents must hold the relevant real estate agent licence or operate under a licensed agent. Buyers can verify a licence independently through Service NSW. A buyers agent does not replace a solicitor, conveyancer, lender, accountant, registered valuer, building inspector or pest inspector. Each of those roles requires a separate qualified professional.
Is a buyers agent worth it for buying in Paddington?
The answer depends on the buyer's situation, not a blanket recommendation. The NSW Government's buyers agent guidance notes that a buyers agent can help with finding, inspecting, negotiating and bidding, but does not guarantee a particular outcome. Full-service representation adds a cost that should be weighed against the buyer's own time, local knowledge, professional support and negotiation confidence.
| Scenario |
Potential value from buyer-side support |
| Interstate or overseas buyer |
Local coordination, inspections and negotiation without travel |
| Time-poor professional |
Search, shortlisting, inspection attendance and coordination managed |
| Auction-inexperienced buyer |
Preparation, contract review, maximum-price discipline and bidding support |
| Investor requiring due diligence coordination |
Assessment across comparable sales, strata, heritage and holding costs |
| Buyer with complex renovation or heritage brief |
Assessment of renovation risk and heritage approval context |
Who may benefit from buyer-side support
Buyers who are purchasing from interstate, have limited time for inspections, are unfamiliar with NSW auction conditions, or are navigating a complex strata or heritage property may find that coordinated buyer-side representation supports a more disciplined acquisition process. The benefit is practical: access to current comparable sales, pre-auction preparation, and a documented approach to due diligence coordination.
When full-service support may not be the right fit
A buyer with extensive local knowledge, time to inspect and assess properties, established relationships with specialist advisers, and confidence in negotiation and auction environments may find self-directed purchasing appropriate. No buyers agent can guarantee a purchase outcome, a specific price result, off-market access or financial return. The service is designed to support the process, not to replace the buyer's own judgement or the advice of other professionals.
Why work with Buyers Agency Australia for a Paddington purchase
Buyers Agency Australia describes a strategy-led, buyer-only approach built around understanding the buyer's goals, finance position and intended property role before active search begins. The stated model is data-informed rather than listing-led: properties are assessed against the buyer's documented brief rather than presented because they are available.
Dragan Dimovski, founder of Buyers Agency Australia, brings 20+ years of property investment experience to the buyer-side process, including knowledge of the Eastern Suburbs market. This is a brand-attributed claim that should be confirmed directly before engagement.
Service scope and availability should be confirmed directly before engagement. Brand service information checked September 2026.
A strategy-led process before property search
The Buyers Agency Australia approach, as described in its current official material, begins with a strategy conversation before a property search is activated. For a Paddington purchase, that means aligning goals (home, investment asset or portfolio step), confirming the finance position, selecting the relevant property type, identifying non-negotiables around heritage exposure, strata, renovation scope and access, and then applying those filters consistently through search, assessment and negotiation.
For investors considering office, retail or industrial assets in Paddington or the broader Eastern Suburbs, that sits within a separate pathway. Commercial property buying support involves different due diligence, lease assessment and yield considerations, and should be discussed separately from a residential acquisition brief.
How the approach applies to residential and investment buyers
For a home buyer, the process centres on fit, condition, heritage compliance potential and long-term liveability. For an investor, the process adds rental evidence review, holding-cost modelling and asset-role assessment to the property brief. Both benefit from a documented maximum price and a structured due diligence sequence before any offer is made or auction entered.
The Buyers Agency Australia approach applies the same discipline to both buyer types: strategy before search, evidence before offer, and coordination through to settlement.
Start your Paddington property search with a strategy session
Before active searching begins, the most useful step is to clarify your purchase goals, confirm your finance position, define the property role and set realistic brief parameters for Paddington's market. Book a free strategy session with the Buyers Agency Australia team to map out what a disciplined Paddington acquisition process looks like for your specific situation. This is a decision-clarity conversation, not an obligation to proceed.
Paddington buyers agent FAQs
What does a buyers agent in Paddington do?
A buyers agent in Paddington represents you exclusively as the buyer, managing brief development, property search, inspection coordination, comparable-sales assessment, due diligence coordination, negotiation or auction bidding, and settlement support. They do not provide legal, tax, finance, valuation, building or pest advice.
Is a buyers agent the same as a buyers advocate?
Yes, in common Australian usage the terms are interchangeable. Both describe a licensed professional acting for the buyer. Always verify the agent's licence and service scope independently before signing an agreement.
How much does a buyers agent cost in Sydney?
Fees vary depending on service scope, engagement structure and the individual agreement. Structures include fixed fees, percentage-based fees, staged fees, and search-only or negotiation-only arrangements. Obtain the full fee, GST, inclusions, exclusions and termination terms in writing before engaging any buyers agent.
Can a buyers agent find off-market property in Paddington?
A buyer-side network may provide access to selected off-market or pre-market opportunities in Paddington, depending on current agent relationships and seller circumstances. Access is not guaranteed, and an off-market opportunity does not automatically carry a better price or lower risk. Full due diligence still applies.
Should I use a buyers agent for a Paddington auction?
Auction preparation in NSW requires unconditional finance approval, a solicitor-reviewed contract, completed inspections and a pre-agreed maximum bid price before auction day. As confirmed by the NSW Government's auction guidance, a successful NSW auction bid has no cooling-off period. A buyers agent can coordinate that preparation and bid on your behalf within your agreed limit.
What checks are important before buying a Paddington terrace or apartment?
At minimum: a building and pest inspection, contract and title review by a solicitor or conveyancer, strata records review for apartments, a planning and heritage status check for the specific address, and a hazard or flood assessment through the relevant council resources. The exact checks required depend on the property type, condition and address.
Can an investor use a buyers agent to buy in Paddington?
Yes. An investor can engage a buyers agent to manage property search, assessment of rental evidence and holding costs, due diligence coordination, and negotiation. The buyers agent does not provide financial, tax or investment advice; a qualified accountant and licensed financial adviser should be engaged for those roles.
Can interstate buyers purchase Paddington property remotely?
Yes, with appropriate support. A buyers agent can conduct inspections, coordinate specialist reports and manage negotiation locally. Interstate buyers still require independent legal advice from a NSW solicitor or conveyancer, unconditional finance approval and qualified inspection professionals. Virtual inspection options can supplement but do not replace a physical inspection before exchange.
What should I ask before signing a buyers agency agreement?
Confirm the agent's licence, the service scope, the fee trigger, what is included and excluded (inspections, travel, auction attendance), any referral arrangements or conflicts of interest, termination rights, and what happens if no purchase proceeds within the engagement period.
When is a buyers agent not the right fit?
A buyers agent adds a cost and may not suit a buyer who has the time, local knowledge, professional advisory support and negotiation experience to manage the process independently. No buyers agent can guarantee a purchase outcome, a specific price, off-market access or a financial return.
Next steps for choosing a Paddington buyers agent
Before proceeding with any Paddington purchase, work through this decision sequence:
- Define whether the purchase is for living, investing or a broader portfolio strategy.
- Confirm your finance position, total buying costs and decision authority.
- Verify the buyers agent's NSW licence, written service scope, fee trigger and any conflicts.
- Require address-specific due diligence before exchange or auction bidding.
- Set a maximum price from comparable-sales evidence, not from auction pressure.
When you are ready to clarify your brief and assess whether Paddington fits your acquisition goals, map out your next property move with a free strategy session. If you want to discuss your brief directly, contact the team to get started.
 General
Need a buyers agent in Paddington, Sydney? Learn how to assess property, manage due diligence, negotiate and buy...
Buyers Agency Australia helps Surry Hills buyers define a property brief, source suitable on-market and, where available, off-market opportunities, assess value and risk, coordinate due diligence, negotiate or bid at auction, and support the purchase through to settlement. The exact fee, scope and professional referrals must be confirmed in writing before engagement. A buyers agent does not replace a solicitor, conveyancer, lender, building inspector, pest inspector or tax adviser.
You might be scanning listings after work, stepping through apartments on a Saturday, or trying to read an auction price guide that tells you almost nothing useful. Maybe you are buying from interstate and have not yet set foot in the suburb. The practical pressure is the same: you need to decide whether a property is worth pursuing, what it is actually worth, and what risks you are taking on.
The decision is rarely about which property looks the most appealing. It is about whether the property fits your budget, intended use, risk tolerance and long-term plan. A confident shortlist requires evidence, not instinct.
For buyers who want structured support through that process, strategy-led property buying support is what Buyers Agency Australia is built around. The team works on the buyer's side only, from initial brief through to settlement, across Sydney and nationally.
Why buy property in Surry Hills?
Surry Hills sits roughly two kilometres south-east of Sydney's central business district, making it one of the most accessible inner-city suburbs in New South Wales. It is a mixed-use suburb with a dense street grid, a strong hospitality and creative industry presence, and a housing stock that ranges from Victorian terraces and Edwardian homes through to mid-century apartment blocks and newer residential buildings.
For buyers considering Sydney property buying support, Surry Hills offers genuine proximity to multiple employment centres without requiring car reliance. Central Station is on the western edge of the suburb, and the Surry Hills Light Rail stop on Devonshire Street is part of the CBD and South East Light Rail route operated by Transport for NSW, connecting the suburb to Circular Quay, Moore Park and beyond. Multiple bus routes run along Crown Street and Elizabeth Street.
Crown Street is the suburb's commercial and social spine, with the Surry Hills Library on Crown Street and Prince Alfred Park adjacent to Central Station providing green space within easy walking distance. These are genuine amenities. They support lifestyle for an owner-occupier and rental demand context for an investor. They are not, on their own, evidence of future price performance.
What local context matters before you inspect
Transport access, walkability and proximity to Crown Street employment and hospitality may appeal to both a professional seeking a primary residence and an investor assessing rental demand. However, the same density that creates walkability can also mean noise exposure, limited parking, or building-to-building overshadowing depending on the specific address.
Surry Hills is not a uniform suburb. A property on a quiet residential block near Prince Alfred Park presents differently to one above a commercial tenancy on Crown Street. Treating the suburb as a single context is a mistake that thorough due diligence is designed to correct.
| Consideration |
Owner-occupier focus |
Investor focus |
| Transport proximity |
Walk to Central, light rail, bus access |
Supports rental demand from workers and students |
| Crown Street amenity |
Lifestyle, walkability, dining |
Proximity to commercial activity may affect quiet enjoyment |
| Parking availability |
Limited street parking in denser blocks |
Check strata entitlement for parking before relying on it |
| Noise exposure |
Check orientation, floor level, adjacent uses |
Affects tenant turnover and rental assumptions |
| Renovation scope |
Heritage controls may limit alterations |
Check planning overlays before assuming development potential |
Which Surry Hills property types need different checks?
Apartments and strata units make up a significant share of Surry Hills' housing stock. These require strata record checks, levy assessment, capital works fund review and building insurance verification before purchase.
Terraces and renovated homes carry their own considerations: heritage overlays, building condition, party wall assessments and permitted use under the current Sydney Local Environmental Plan 2012. Not every terrace in Surry Hills carries heritage protection, but buyers should verify the specific address and intended works against current planning records rather than assuming suburb-wide conditions apply.
Mixed-use properties or properties with a commercial ground floor tenancy introduce a separate layer of lease, zoning and yield analysis. Buyers considering office, retail or industrial assets alongside residential property should review commercial property acquisition support as a distinct service category.
What does a buyers agent do in Surry Hills?
A buyers agent (also called a buyers advocate) is a licensed property professional who represents the purchaser, not the vendor. In New South Wales, acting as an agent for a prospective purchaser is a licensed activity regulated by NSW Fair Trading. The selling agent's obligation is to the vendor. The buyers agent's obligation is to the buyer.

To understand the buyers agent process in full, it helps to see the service as a sequence of connected steps rather than a single transaction function.
From property brief to shortlist
The process begins before any property is identified. A buyers agent will work through the buyer's objectives, budget, borrowing position, intended use (primary residence, investment or both), timeframe, property type preference, risk tolerance and how the purchase fits into a broader portfolio if applicable.
That brief then shapes the search parameters. Properties that do not meet the brief are excluded. This saves time and prevents emotion from driving the shortlist.
Inspections, assessment and due diligence
Once properties are identified, a buyers agent will inspect, assess comparable sales, review property condition, and coordinate with qualified professionals including building inspectors, pest inspectors, solicitors or conveyancers for contract and title review, and where relevant, valuers. The NSW Government guidance on buying property recommends that buyers obtain the contract, arrange legal review and research comparable sales before making an offer.
For investment property buyers agent guidance, this assessment layer also considers rental evidence, ownership costs, strata financials and how the asset performs relative to the buyer's strategy.
Negotiation, auction bidding and settlement support
A buyers agent negotiates or bids at auction under a written authority from the buyer. They do not replace a solicitor or conveyancer for contract review and exchange, a lender for finance assessment, a building inspector for condition reports, a pest inspector for timber pest assessment, or a tax adviser for ownership structure and tax implications.
| Buyers agent coordinates |
Professional responsibility remains with |
| Comparable sales analysis, valuation context, negotiation, auction bidding |
Solicitor or conveyancer: contract, title, exchange |
| Sourcing, inspections, shortlisting |
Building inspector: condition, defects |
| Due diligence coordination, strata record review |
Pest inspector: timber pest assessment |
| Settlement timeline, communication between parties |
Lender: finance approval, valuation |
| Strategy, brief, portfolio fit |
Tax adviser: ownership structure, CGT, depreciation |
How Buyers Agency Australia approaches a Surry Hills purchase
Buyers Agency Australia operates as a buyer-side advisory and acquisition service. The brand, led by Dragan Dimovski with more than 20 years of property investment experience, applies a strategy-first process to residential and commercial property purchases across Sydney and nationally.
Buyers Agency Australia's service scope and availability were reviewed in August 2026. Confirm current inclusions, fees and availability directly before engagement.
This section describes Buyers Agency Australia's stated approach and is not an independent ranking of buyers agents.
Why strategy comes before property search
The starting point is not a suburb or a property type. It is the buyer's objective. A Surry Hills purchase for a professional seeking a primary residence involves different considerations from the same suburb for an investor targeting rental yield, or a portfolio builder using the asset as a stepping stone to build an investment property strategy across multiple locations.
Once the strategy is clear, the asset type, location, budget, cash-flow tolerance and portfolio role follow logically. Without that sequence, there is a real risk of buying a property that looks appealing but does not serve the buyer's actual goals.
How Dragan Dimovski's experience informs the process
Dragan Dimovski is the founder and senior buyers agent at Buyers Agency Australia. According to official brand material, he brings more than 20 years of property investment experience to the firm's acquisition process. The team applies data-informed selection, sourcing across on-market and off-market channels, buyer-side negotiation and end-to-end settlement coordination.
The service is positioned as purchaser-focused rather than volume-driven. Buyers engage the team to represent their interests only. Scope, inclusions and professional referral arrangements should be confirmed in writing before engagement begins.
How on-market and off-market property sourcing works
A complete Surry Hills property search covers public listings on major platforms, pre-market campaigns where a vendor tests appetite before formal listing, and off-market opportunities that do not reach the public portals at all. Agent relationships and local market activity are the primary sourcing channels for pre-market and off-market opportunities.
Off-market access may exist in Surry Hills, but availability depends on current market conditions and active selling agent relationships. Off-market status is a sourcing channel, not a quality signal or a price advantage. What a Sydney buyers agent does in practical terms is run all three channels simultaneously rather than relying on any one source.
What off-market access can and cannot mean
| Common assumption |
More accurate position |
| Off-market means a better price |
Price is determined by comparable sales and vendor motivation, not listing channel |
| Off-market means less competition |
There may be fewer buyers, but the vendor's expectation is unchanged |
| Off-market is always available |
Availability varies by market conditions and active selling agent activity |
| Off-market skips due diligence |
Every property requires the same contract, condition, strata and planning checks |
A useful three-question off-market test: why is this property not listed publicly, what comparable sales evidence supports the asking price, and how much of the due diligence has actually been completed?
What due diligence should cover for a Surry Hills property
Due diligence in Surry Hills is not a single report. It is a coordinated set of checks, each with a distinct professional responsibility. NSW Government guidance on strata property recommends reviewing strata reports, levies, capital works plans, defects, insurance records and by-laws before buying a strata unit. NSW Government conveyancing guidance identifies title, easements, planned development and strata costs as additional checks.

Strata records, levies and building condition
For apartments and units in Surry Hills, a strata report (including a section 184 certificate from the owners corporation) should confirm current levies, any outstanding special levies, the capital works fund balance, known defects, building insurance cover and by-law compliance. A building inspector provides a separate condition assessment that a strata report alone does not cover. Both reports serve different purposes and should not be treated as substitutes for each other.

Planning, zoning and heritage considerations
Surry Hills contains properties with heritage significance, but heritage overlay and zoning status vary by individual lot. Buyers should verify the specific property address against current Sydney LEP records and council planning information before assuming that renovation, subdivision or any development is permitted. Checking that the intended use matches current zoning is essential, particularly for buyers considering mixed-use or commercial ground-floor properties.
Comparable sales and rental assumptions
The asking price for any Surry Hills property should be tested against recent, genuinely comparable sales in the same price range, property type and condition bracket. Rental estimates for investment properties should be tested against current rental evidence for comparable properties in the same street or immediate precinct, not suburb-wide averages. No median price or rental yield figures are included in this guide because no current, dated, authoritative figures were verified for publication.
Book a free strategy session to work through how these checks apply to a specific property you are considering.
How to negotiate or bid for a Surry Hills property
Surry Hills properties are sold by both private treaty and auction. The method of sale affects the timeline, the contract position, and the legal consequences of exchange.

| Factor |
Private treaty |
Auction |
| Negotiation timing |
Before exchange; offer and counter-offer process |
No negotiation after the hammer falls |
| Cooling-off period |
Usually five business days in NSW (conditions apply) |
No cooling-off period after auction exchange |
| Due diligence timing |
Can be completed before making an offer |
Must be completed before auction day |
| Finance readiness |
Generally available before exchange |
Finance must be unconditional before bidding |
| Contract position |
Buyer can negotiate conditions |
Contract is typically vendor's standard terms |
NSW Fair Trading confirms that successful auction bidders generally exchange contracts and pay a deposit at auction, with no cooling-off period after that exchange in NSW. All inspections, contract review and finance must be in place before auction day.
Setting a defensible maximum price
The maximum price for a Surry Hills property should be set in writing before negotiation begins or before attending an auction. It should be based on comparable sales evidence, total acquisition costs (including transfer duty, legal fees, inspection costs and finance costs), the finance limit confirmed by the lender, the expected holding cost against projected rental income for investment properties, and whether the property genuinely fits the buyer's strategy.
A buyers agent may provide negotiation support and valuation context, but cannot guarantee a successful purchase or a specific outcome. Emotional pressure during an auction is real. A written limit established before that pressure arrives is the most practical protection against overpayment.
Preparing for a NSW auction
Auction preparation includes completing all inspections, arranging contract review by a solicitor or conveyancer, confirming unconditional finance approval, registering as a bidder on auction day, and having the deposit available (typically ten percent of the purchase price). A buyers agent attending on a buyer's behalf operates under a written authority that specifies the maximum bid.
Who should use a buyers agent in Surry Hills?
A buyers agent adds most practical value when time, location, expertise, or transaction complexity creates a genuine gap between the buyer's capacity and what the purchase requires.
Buyers who may benefit include:
- Busy professionals who cannot consistently attend inspections, research comparable sales and coordinate due diligence during work hours
- Interstate or overseas buyers who cannot inspect in person or maintain local market visibility
- First-time buyers entering an auction-active inner-Sydney market without prior negotiation or auction experience
- Investors who want an asset assessed against a defined strategy rather than surface appeal
- Portfolio builders adding a Surry Hills property alongside existing assets who need the purchase to fit a broader capital allocation plan
A self-directed buyer who has local knowledge, time to inspect consistently, experience assessing strata and building condition reports, confidence at auction and a clear due diligence process may find they can manage the purchase independently. Full-service engagement is not the only option, and a buyers agent who is worth engaging should acknowledge that honestly.
Buyers agent fees and the engagement process
Fee structures for buyers agents in Australia vary by scope, market and agreement. Common models include a fixed fee for full-service search and purchase, a percentage of the purchase price, a staged payment across engagement and exchange milestones, or a limited-scope arrangement covering only negotiation or auction attendance.
No current Buyers Agency Australia dollar fee or formal fee schedule was verified for this guide. Fees must be confirmed directly with the team before engagement.
What to confirm before signing an agreement
Before signing a buyers agency agreement, confirm:
- Scope: what the service includes and what is excluded
- Fee trigger: when fees become payable and whether a fee applies if no purchase proceeds
- GST: whether quoted fees include or exclude GST
- Exclusivity and term: whether you are restricted from purchasing independently during the engagement period
- Auction attendance: whether auction day attendance is included or a separate cost
- Inspection and travel costs: how these are handled if properties are inspected across multiple suburbs
- Professional referrals: which professionals the buyers agent works with and whether referral arrangements exist
- Termination rights: conditions under which either party can exit the agreement
- Conflicts of interest: whether the agent has any commercial relationship with selling agents, developers or vendors relevant to your search
The written agreement governs the engagement. Read it before signing.
When Buyers Agency Australia may not be the right fit
Full-service buyer representation is not appropriate for every buyer. If you:
- Have strong familiarity with the Surry Hills market, have inspected many comparable properties, and are confident assessing condition and strata records independently
- Can consistently attend inspections during business hours and on weekends without significant trade-off
- Have clear auction experience and a disciplined approach to setting and holding a maximum price
…you may find that you can manage the purchase process yourself, or that a more limited engagement (such as negotiation or auction-only support) serves your needs better than a full-service model. The goal of any buyers agent conversation should be to clarify that before you commit.
Next steps for buying property in Surry Hills
A practical pre-purchase sequence:
- Define the brief: primary residence, investment, or a dual-purpose purchase with clear priorities for each.
- Confirm finance: obtain pre-approval or unconditional finance before inspecting or making offers. NSW Government guidance recommends confirming finance before exchanging contracts.
- Identify property type: apartment, terrace, house or mixed-use; each carries different due diligence requirements in Surry Hills.
- Arrange professional advice: engage a solicitor or conveyancer before the first contract review, not after.
- Define decision authority: who sets the maximum price, who coordinates inspections, and who will attend auction if the property is listed for auction.
If you want support working through that sequence for a specific Surry Hills property or a broader Sydney search, map out your next property move before committing to a purchase timeline.
This article is general information only and does not constitute personal financial, tax, legal or investment advice. Consult a qualified professional for advice relevant to your individual circumstances.
Frequently asked questions about a buyers agent in Surry Hills
Is a buyers agent the same as a buyers advocate?
Yes, the terms are used interchangeably in NSW. Both refer to a licensed professional representing the buyer rather than the vendor. The written agreement and scope of service matter more than which label the agent uses.
Can a buyers agent find off-market property in Surry Hills?
Access to off-market opportunities may exist through selling agent relationships. However, availability is not guaranteed, and any off-market property must still pass the same valuation, condition, strata, planning and contract checks as a listed property.
What does a buyers agent do before an auction?
Before auction day, a buyers agent assesses comparable sales to establish a valuation range, arranges or reviews building and pest inspection reports, coordinates contract review by a solicitor or conveyancer, confirms unconditional finance is in place, and agrees a written maximum bid with the buyer.
Does a buyers agent replace a solicitor or conveyancer?
No. A buyers agent handles sourcing, assessment, negotiation and coordination. Contract exchange, title review, legal conditions and settlement remain the responsibility of a solicitor or conveyancer, as outlined in NSW Government conveyancing guidance.
How much does a buyers agent cost in Australia?
Fee structures vary by scope, service model and agreement. No verified current fee schedule for Buyers Agency Australia is included in this guide. Contact the team directly to confirm current fees and what is included before signing any agreement.
Can Buyers Agency Australia help with an investment property?
Yes. The brand's stated approach covers strategy-led selection, property assessment, sourcing, due diligence coordination, negotiation and settlement support for investment property purchases. The process begins with the buyer's strategy and intended portfolio role before identifying specific assets.
Can a buyers agent help an interstate buyer?
A buyers agent can support interstate buyers by conducting inspections, reporting on property condition and local context, and coordinating due diligence professionals on the ground. Buyers should confirm current service coverage with Buyers Agency Australia directly before engaging for a remote purchase.
What should I ask before hiring a buyers agent?
Key questions include: Is the agent licensed in NSW? Who do they represent? Do they have any referral arrangements with selling agents or developers? What does the service include and exclude? What are the fees and payment triggers? How do they handle conflicts of interest, and what happens if no purchase proceeds?
Should I use a buyers agent to buy an apartment in Surry Hills?
If you lack time to inspect consistently, are unfamiliar with reading strata reports and comparable sales, or are bidding at auction for the first time, a buyers agent can add structure and discipline to the process. If you are confident across all of those areas, a more limited engagement may be sufficient.
Can Buyers Agency Australia help with commercial property as well as residential property?
Yes. The brand provides commercial buyers agent guidance for office, retail and industrial acquisitions alongside its residential service. Commercial property requires separate asset-specific due diligence, lease analysis, yield analysis, finance assessment and professional advice beyond the residential buying process.
A practical decision framework for your Surry Hills purchase
Before committing to any Surry Hills property, work through these five steps:
- Define the asset role: is this property for living, residential investment, or part of a broader portfolio strategy? The answer shapes every subsequent decision.
- Confirm the budget and total acquisition costs: purchase price is only part of the cost. Add transfer duty, legal fees, inspection costs, strata levies from settlement, ongoing ownership costs and finance costs before assessing affordability.
- Test the property through evidence: comparable sales, building and pest condition, strata financials, planning and heritage status, and contract terms. Each check has a distinct professional responsibility.
- Set a written maximum price before negotiating or bidding: based on the evidence above, not on auction-day pressure or a vendor's price guide.
- Confirm the buyers agent's scope, fees, conflicts and professional referrals in writing before any engagement begins.
If you would like to work through that framework with a strategy-led team, map out your next property move with Buyers Agency Australia, then speak with the Buyers Agency Australia team to discuss your specific brief.
This article is general information only and does not constitute personal financial, legal, tax or investment advice. Always consult qualified professionals for advice specific to your circumstances.
 General
Looking for a buyers agent in Surry Hills? Discover how Buyers Agency Australia supports property search, due diligence,...
There is no single best suburb to invest in Australia. The right shortlist depends on your budget, investment strategy, property type, risk tolerance and holding period, then must be tested against demand, supply, rental conditions, infrastructure and property-level risks. ABS data for 2024-25 shows Perth (2.4%), Brisbane (2.1%) and Melbourne (2.0%) among the faster-growing capital cities, but city-level population growth is a screening signal only, not proof that every suburb in those cities is suitable. The right suburb is the one that supports the investor's goals, risk profile and next portfolio decision under conservative assumptions.
You have a deposit ready, or equity to access, and every property platform is serving you a list of the country's hottest suburbs. The numbers look compelling. But most of those lists rank locations by recent price growth or headline yield without showing you how the recommendation changes when your budget, property type, or risk tolerance shifts.
Choosing a suburb before defining the portfolio role that property needs to play can lead to the wrong cash-flow profile, the wrong property type for that market, or a risk exposure you did not price in. A suburb that suits a cash-flow investor holding a Brisbane house may be entirely wrong for a Sydney-based investor buying their first unit.
Buyers Agency Australia's approach is strategy-first and buyer-side, which means suburb selection starts with what the purchase needs to achieve, not with what has performed recently. This article gives you the independent framework to test any suburb before you decide whether to go further.
Why there is no permanent best suburb to invest in Australia
No suburb holds the top position permanently. Markets move through supply cycles, infrastructure changes, employment shifts and interest-rate conditions that alter the investment case every few years. A suburb that delivered strong capital growth between 2020 and 2023 may now carry a development pipeline, higher vacancy or compressed serviceability that changes the outlook entirely.
City-level averages compound this problem. PropTrack's July 2026 Home Price Index recorded national dwelling values sitting 1.8% below their March 2026 peak, with capital-city price movements diverging significantly by city and property type. Reading one headline figure and applying it to a suburb-level decision is like navigating with a continent-level map.
This article uses a shortlist by strategy rather than a fixed ranking. A suburb may suit a growth-focused investor buying an established house but fail the same test for a cash-flow investor buying a unit in the same postcode. The table below shows why a single best list collapses under scrutiny.
| What changes |
Why it changes the suburb shortlist |
| Budget and borrowing capacity |
Determines which price points and property types are viable |
| Growth focus versus cash-flow focus |
Changes the vacancy, yield and supply thresholds that matter |
| Holding period |
Shorter holds need stronger resale depth and lower supply risk |
| Property type preference |
A suburb can suit houses and fail for units in the same street |
| Risk tolerance |
Flood, bushfire, insurance and employment concentration all affect suitability |
What makes a suburb suitable for property investment?
Before naming locations, it helps to define what evidence actually supports an investment decision. Every attribute below sits on a spectrum from screening signal to purchase evidence, and the gap between the two is where most mistakes happen.
Demand depth and population growth
Population growth at the capital-city level is a screening signal, not a suburb-level confirmation. The relevant question is whether the specific suburb has growing household formation, a mix of tenant and owner-occupier demand, and enough resale depth to support an exit in five to ten years.
Owner-occupier depth matters because it provides a buyer pool beyond investors when you want to sell. Suburbs with very high investor concentration tend to experience sharper price corrections when sentiment shifts, because fewer owner-occupiers are willing to absorb that stock.
Check ABS regional population data at the SA2 level, not just the Greater Capital City Statistical Area, to understand whether the specific corridor is actually growing.
Supply, vacancy and rental conditions
A suburb can have strong demand and still perform poorly for investors if supply is growing at the same pace. New apartment approvals, land-release corridors and build-to-rent projects all affect how much competing stock a landlord will face at re-leasing.
National rental vacancy sat at 1.3% in June 2026, well below the pre-pandemic balanced range of 2.5% to 3.5%, according to SQM Research's June 2026 bulletin. Brisbane held at 0.9% and Adelaide at 0.7%, both indicating acute to tight conditions. Perth tightened further to 0.6%. These city-level figures are context, not a suburb-level recommendation; always check the specific property type in the specific suburb.
Asking rent is not achieved rent. Gross yield is not net cash flow. Build your rental assumptions from comparable recent lease evidence, not advertised figures.
Employment, infrastructure and liveability
Suburbs with diversified employment nearby, reliable public transport and accessible retail and health services attract a broader, more stable tenant pool. Employment diversity reduces the risk of a single-industry downturn draining demand from a suburb at once.
Infrastructure can support demand when it is confirmed and delivered. Separate announced projects from funded, under-construction and completed works. Infrastructure Australia's 2026 Infrastructure Priority List provides national context, but proximity to a listed priority project is not proof of capital growth at a specific address.
Affordability, resale depth and risk
Affordability affects how many buyers can enter the market at your price point when you want to sell. Price-to-income pressure varies significantly by city and suburb, and serviceability rules set by APRA mean that tightening credit conditions can reduce the effective buyer pool quickly.
Flood, bushfire and insurance risk are often underchecked. They affect insurance costs, lending eligibility, future buyer appetite and resale price. For Brisbane properties, Brisbane City Council's FloodWise Property Report is the appropriate address-level check. For properties in other states, identify the equivalent state or council hazard mapping tool and verify it at the address level, not the suburb level.
What are the best suburbs to invest in Australia in 2026?
The shortlist below presents candidate locations by strategy fit, not as a ranked winner list. Each entry identifies one reason to investigate, one honest limitation and the current evidence still required before a purchase decision. Shortlist inclusion is not a recommendation to buy.
How we evaluated these Australian investment suburbs
Candidates were screened in this sequence:

- Strategy and budget fit for a defined investor profile
- Population and employment demand at the suburb or corridor level
- Rental demand, vacancy and achieved rent from a recognised dataset
- Supply pipeline and planning approvals from official state sources
- Infrastructure status, separated into proposed, funded, under construction and completed
- Affordability, serviceability and price-to-income context
- Resale depth and owner-occupier demand within the suburb
- Flood, bushfire, insurance and other material risk checks
- Property-type fit for houses, townhouses and units separately
- Portfolio sequencing and the investor's ability to hold under conservative assumptions
Candidates were excluded when current suburb-level vacancy or rental evidence was missing, supply risk was unclear, employment was too concentrated without a risk-adjusted case, hazard or insurance evidence was unresolved, or the market could not support reliable comparable sales. No suburb in this article has been independently verified to the level required for a property-level purchase decision.
Growth and owner-occupier depth candidates
| Candidate |
Strategy fit |
Evidence to verify |
Honest limitation |
Investor profile |
| Parramatta, NSW |
Growth and balanced |
Comparable sales by property type, unit supply pipeline, vacancy by building class |
High unit supply risk; new apartment demand and resale require careful property-level screening |
Experienced investor with Sydney market knowledge and strong serviceability |
| Moorooka, QLD |
Balanced growth and rental |
Achieved rents, comparable sales, land content, proximity to employment nodes |
Mid-ring Brisbane with improving demand; check individual street and block conditions |
Growth-focused investor comfortable with Brisbane mid-ring entry prices |
For Sydney buyer-side market support, entry prices and property-type selection within high-demand suburbs require precise due diligence given current price softening in the city overall.
Infrastructure-led and affordability candidates
| Candidate |
Strategy fit |
Evidence to verify |
Honest limitation |
Investor profile |
| Austral and Leppington, NSW |
Long-term growth corridor |
Infrastructure delivery status, land-release schedule, vacancy, employment access |
Infrastructure is progressing but not uniformly complete; holding period likely exceeds five years |
Long-term buy-and-hold investor with capacity to hold through supply additions |
| Clyde North, VIC |
Affordability and growth corridor |
Current vacancy, comparable sales, development pipeline, transport timeline |
Melbourne outer ring; check specific precinct supply and infrastructure delivery status before committing |
Budget-conscious investor comfortable with a 7 to 10 year horizon |
| Alkimos, WA |
Affordability and rental demand |
Achieved rents, vacancy, coastal corridor infrastructure, comparable sales |
Perth market softened in July 2026 per PropTrack data; entry timing and property type require careful assessment |
Yield-aware investor looking at Perth's northern corridor with long holding intentions |
Balanced rental demand and entry-price candidates
| Candidate |
Strategy fit |
Evidence to verify |
Honest limitation |
Investor profile |
| Redcliffe, QLD |
Rental yield and lifestyle demand |
Vacancy, achieved rent by property type, comparable sales, supply pipeline |
Amenity-driven demand can be cyclical; confirm employment diversity beyond lifestyle appeal |
Balanced investor targeting Brisbane's Moreton Bay corridor |
| Near-city Adelaide locations |
Rental yield and affordability |
Vacancy by suburb, land content, comparable sales, state infrastructure plans |
Adelaide's market showed price moderation in mid-2026; entry point and property type still need individual verification |
Cash-flow-focused investor seeking tight vacancy markets at lower entry prices |
For detailed Brisbane investment buying support and current suburb-level evidence, it is worth reading the Brisbane investment analysis before shortlisting a specific location.
Regional candidates require a separate risk tier
Regional markets can produce strong yield figures, but they require a separate due diligence process covering employment concentration, population trend, insurance costs, supply pipeline and resale depth. A regional suburb sitting near a single employer, a mining lease or a tourism corridor carries a risk profile that is not comparable to a diversified capital-city suburb. If regional candidates are part of your strategy, treat employment diversity, insurer appetite and exit liquidity as mandatory checks, not optional ones.
How do I compare an investment suburb before buying?
A repeatable comparison process reduces the risk of a decision based on one good-looking data point. Use the table below as a starting scorecard, not as a final checklist.
| Metric |
Evidence source |
Investor implication |
| Population trend |
ABS SA2 regional data |
Confirms household demand at suburb level, not just city level |
| Vacancy rate |
SQM Research by suburb and property type |
Indicates rental competition for the specific stock you plan to buy |
| Achieved rent |
PropTrack or Cotality comparable lease data |
Confirm what tenants are paying, not what landlords are asking |
| Supply pipeline |
State planning portal and council DA register |
Reveals competing stock that will enter the market during your hold |
| Infrastructure status |
Project authority or state government announcements |
Distinguish proposed, funded, under construction and delivered |
| Days on market |
PropTrack or Cotality by property type |
Indicates resale liquidity and buyer depth |
| Hazard exposure |
Council flood maps, state bushfire maps, insurer feedback |
Affects insurance cost, lender appetite and future resale value |
| Comparable sales |
Dated PropTrack or Cotality suburb data |
Anchors your entry price and exit assumptions in reality |
Compare markets before comparing suburbs
Capital-city data is a screening input, not a purchase recommendation. Sydney showed price softening in mid-2026 according to PropTrack, while Adelaide maintained tight vacancy and positive annual growth into the same period. Melbourne's rental vacancy remains comparatively looser than Brisbane, Adelaide and Perth. These differences mean that the same investment strategy may produce different results in each city, even at similar price points.
Use city-level vacancy, employment diversity, population growth, and price trend data to determine which markets deserve suburb-level research. Then go deeper inside the shortlisted market.
Compare property types inside the suburb
An established house and a new apartment in the same suburb can have entirely different supply, resale, maintenance, body corporate and tenant-demand profiles. An outer-ring suburb with strong house demand may also have hundreds of new units under construction, creating a two-speed rental market within the same postcode. Check the development pipeline specifically for the property type and price bracket you plan to buy.
What data should you check before choosing a suburb?
Building a research sequence before you shortlist a suburb reduces the chance of anchoring on a single number.
Population, household and employment data
Start with ABS regional population data at the SA2 level to understand whether the suburb or corridor is growing independently of the city. Cross-reference with state economic or employment profiles to assess whether employment in the area is concentrated in one industry or spread across multiple sectors. A suburb dependent on one hospital, one university or one industrial precinct carries a demand concentration risk.
Vacancy, rental demand and achieved rent
Use SQM Research's vacancy data at the suburb level and cross-check with PropTrack or Cotality for achieved rents and days-to-lease for comparable properties. The national vacancy rate of 1.3% in June 2026 (SQM Research) tells you the macro context; the suburb-level figure for your specific property type tells you what matters. Asking rent on an advertising platform is not achieved rent. Model your cash flow on documented comparable leases, not the advertised price of the most optimistic listing.
Supply pipeline, planning and infrastructure
Check the relevant state planning portal and council development application register for approved and pending dwellings in the suburb. A suburb can look undersupplied today and face a wave of completions in 18 months. Infrastructure Australia publishes a national priority list, but confirmed state and local project authority documents are the authoritative source for specific projects in your target suburb. Separate project announcements from funded and committed builds.
Flood, bushfire, insurance and property-level risk
Suburb-level reputation is not a substitute for address-level hazard checking. In Brisbane, use the Council's FloodWise Property Report for each address. In New South Wales, Victoria, South Australia and Western Australia, identify the equivalent state hazard mapping tool and verify coverage for the specific property. Always seek written insurance feedback for the address before committing to a purchase, because insurer appetite and premium levels vary by lot and structure type, not just by suburb.

Is a high rental yield enough to make a suburb a good investment?
No. A high gross yield is a signal worth investigating, not a decision in itself. High yields often appear in markets with weaker resale depth, higher vacancy risk, concentrated employment, ageing stock or a development pipeline that is about to add competing supply. A 6% gross yield on a unit that stays vacant for eight weeks per year, requires regular maintenance and carries a high body corporate levy can deliver a negative net cash flow position once holding costs are factored in.
The ATO's guidance on rental property income and deductions makes clear that the tax treatment of a rental property depends on individual circumstances. A gross yield calculation does not capture interest costs, property management fees, council rates, insurance, maintenance or vacancy buffer. Model every yield claim on a net basis before treating it as evidence.
| Gross yield input |
Net cash flow reality |
| Asking rent used |
Only achieved, comparable lease rents are valid |
| No vacancy buffer |
Include at least 4 to 6 weeks vacancy per year as a base assumption |
| Holding costs excluded |
Add rates, insurance, body corporate, management fees and maintenance |
| Interest costs excluded |
Use your actual loan structure, not a headline rate |
| Tax not modelled |
Obtain qualified tax advice before treating deductions as cash savings |
Should you prioritise capital growth or rental yield?
The right balance depends on your portfolio position, not on which strategy is fashionable. A first-time investor building borrowing capacity may need cash flow support to hold comfortably. A more established investor with equity and serviceability headroom may accept lower yield in exchange for stronger resale depth and growth potential. Neither is universally correct.

To build a property investment strategy that reflects your specific position, you need to understand how the chosen suburb and property type interact with your current borrowing capacity and your ability to fund the next acquisition.
| Strategy focus |
What the suburb needs to show |
Key risk to test |
| Capital growth |
Owner-occupier demand, resale depth, employment diversity, infrastructure delivery |
Supply that can outpace demand; price softening during holding period |
| Rental yield |
Tight vacancy, diversified tenant base, low vacancy risk property type |
High yield from a market with weak resale or concentrated employment |
| Balanced approach |
Moderate yield, positive resale depth, manageable supply pipeline |
Assuming both outcomes will be maximised; most suburbs optimise one or the other |
Every strategy decision should include a portfolio sequencing test: does this purchase preserve the investor's ability to acquire the next asset, or does it constrain borrowing capacity to the point where the portfolio stalls?
What mistakes can make a good-looking suburb a poor investment?
The most common errors in suburb selection are not dramatic. They are quiet, repeatable and expensive over a five to ten year holding period. To avoid common property investment mistakes, work through this list before signing a contract.
-
Chasing last year's growth. Past performance is a market observation, not a forward indicator. A suburb that rose 20% in 2024 may now be overpriced relative to comparable markets. Corrective action: compare current entry price to current comparable sales, not to the price three years ago.
-
Relying on a single metric. Yield, median price or days on market each tells one part of the story. Corrective action: apply the full scorecard before reaching a conclusion.
-
Confusing asking rent with achieved rent. Advertised rents on platforms frequently overstate what comparable properties actually lease for. Corrective action: request comparable lease evidence from a property manager active in the suburb.
-
Ignoring the supply pipeline. A suburb can appear tight today with hundreds of new apartments in planning approval. Corrective action: check state planning portals and council DA registers for the specific property type.
-
Treating announced infrastructure as delivered. A train line or motorway extension that is proposed but unfunded does not yet improve access. Corrective action: confirm project status from the relevant project authority before assuming a connectivity benefit.
-
Skipping hazard checks. Flood, bushfire and insurance risk can affect lender appetite, insurance premiums and future resale value in ways that are not visible in a listing description. Corrective action: complete an address-level hazard check for every property before shortlisting.
-
Choosing a suburb because the investor likes it. Personal familiarity is not demand evidence. Corrective action: separate emotional preference from the investment case and test the latter against data.
-
Failing to model the next purchase. A property that stretches serviceability to its limit may prevent the investor from buying again for years. Corrective action: model the impact on borrowing capacity before committing, not after.
Also separate two distinct failure modes: the wrong suburb with the right property type, and the right suburb with the wrong property type. Both produce poor outcomes, but they require different corrective approaches.
How can Buyers Agency Australia help assess the right suburb and property?
Strategy-led property buying support from a buyer-side representation service means the research, suburb screening, property sourcing and negotiation are all done with the buyer's goals as the primary brief, not the vendor's asking price.
Dragan Dimovski, a property expert with more than 20 years of experience, leads the approach at Buyers Agency Australia. The process is structured around defining the investment goal first and working backward to the suburb and property type that can serve it.
Buyers Agency Australia is the publisher and service provider discussed in this section. The article explains process fit and does not guarantee investment performance.
What the process can include
| Step |
What it covers |
| Strategy definition |
Clarify portfolio role, budget, risk tolerance, property type and holding period |
| Market and suburb screening |
Screen capital cities and corridors against demand, supply, vacancy, infrastructure and affordability |
| Property sourcing |
Source properties on-market and through off-market channels as a sourcing method, not a guarantee |
| Suburb and comparable-sales research |
Assess comparable sales, rental evidence, supply pipeline and property-specific risks |
| Due diligence coordination |
Coordinate building, pest, title, planning, flood, strata and insurance checks |
| Negotiation and settlement support |
Negotiate on the buyer's behalf and support through to settlement |
When this approach is not the right fit
The service may not suit a buyer without confirmed finance clarity, a buyer seeking a guaranteed return or capital growth outcome, or a buyer who wants to manage the full research, sourcing and negotiation process independently. A buyers agent is not a mortgage broker, accountant, conveyancer, building inspector or insurance adviser, and cannot replace the professional advice required in each of those disciplines.
A practical suburb selection checklist
Use this checklist to determine whether a suburb warrants deeper property-level research. It is a decision aid, not financial advice.
Go conditions
- Finance and serviceability are confirmed with a qualified broker
- Demand is supported by current vacancy and comparable rental evidence
- Comparable recent sales are available for the specific property type
- Risk checks (flood, bushfire, insurance, planning) are complete at the address level
- The purchase supports the broader portfolio plan and preserves borrowing capacity for the next acquisition

Pause conditions
- Current suburb-level vacancy or rental evidence is incomplete
- The development pipeline for the chosen property type is unclear
- The yield calculation relies on asking rent rather than comparable achieved leases
- Insurance feedback has not been confirmed for the address
Walk away conditions
- The investment case only works under optimistic growth or vacancy assumptions
- Material due diligence remains unresolved
- The purchase would restrict borrowing capacity to the point where the next portfolio decision is blocked
- Flood, planning or title risks are unresolved
If the suburb passes the Go conditions above, book a free strategy session with the Buyers Agency Australia team to test the next layer of property-level research.
What should you confirm before buying an investment property?
Suburb selection is only one stage of a thorough purchase process. Before exchanging contracts, confirm each of the following with the relevant professional or source.
| Check |
Responsible professional or source |
| Deposit, equity and acquisition costs |
Qualified mortgage broker and accountant |
| Finance pre-approval and serviceability |
Qualified mortgage broker, noting APRA serviceability settings |
| Transfer duty and concession eligibility |
Relevant state revenue office (rules vary by state, buyer status and property use) |
| Land tax obligations |
State revenue office and accountant |
| Rental income and deductibility assumptions |
ATO rental property guidance and qualified accountant |
| Insurance availability and premium |
Qualified insurer, confirmed for the specific address |
| Building and pest inspection |
Licensed building inspector and pest inspector |
| Title, contract and conveyancing |
Licensed conveyancer or solicitor |
| Planning, zoning and development overlays |
Relevant state planning portal and council |
| Flood, bushfire and environmental risk |
Council maps and state hazard mapping, address-level |
| Strata or body corporate records |
Strata inspector or solicitor, where applicable |
| Property management expectations |
Experienced local property manager for the suburb and property type |
To plan your investment property deposit and understand acquisition cost implications, review the deposit and cost guidance before engaging a lender. To review the investment due diligence checklist in full, work through each item with the relevant professional before exchanging contracts.
Professional advice is required for personal finance, tax, legal, insurance and planning decisions. No section of this article constitutes advice in any of those disciplines.
Frequently asked questions about Australian investment suburbs
What are the best suburbs to invest in Australia in 2026?
There is no universal best suburb. The shortlist depends on strategy, budget, property type, current data and risk checks. Suburbs that suit one investor profile may be entirely unsuitable for another.
How do I choose an investment suburb in Australia?
Start with your investment strategy, then assess demand, supply, achieved rent, employment diversity, infrastructure delivery status, affordability and hazard risk. City-level data is a screening input, not a suburb-level recommendation.
Is a high rental yield enough to make a suburb a good investment?
No. Gross yield alone is not enough. Vacancy, holding costs, resale depth, employment concentration and property condition all affect whether a high yield translates to a positive net position.
Should I invest in a capital city or regional suburb?
It depends on your risk tolerance, strategy, budget and required resale depth. Regional markets require separate checks on employment concentration, insurance, vacancy and exit liquidity that are not required for diversified capital-city suburbs.
What vacancy rate is good for an investment suburb?
There is no universal threshold. Use the current trend for the specific property type in the specific suburb rather than a fixed national figure. SQM Research provides suburb-level data that allows a meaningful comparison.
How does infrastructure affect property investment suburbs?
Infrastructure can improve access and amenity, but it does not guarantee capital growth. Separate proposed, funded, under-construction and completed projects before including infrastructure as a positive factor in your assessment.
Should I buy a house, unit or townhouse for investment?
The right property type depends on strategy, budget, supply concentration, land content, body corporate exposure and resale demand within the specific suburb. The same suburb can show strong demand for houses and weak demand for new units simultaneously.
How do I check flood or bushfire risk before buying?
Use official address-level hazard maps and obtain written insurance feedback for the specific address. Suburb reputation is not a substitute for property-level checking.
Do I need a buyers agent to invest in property?
No, a buyers agent is not mandatory. Structured research, sourcing, negotiation and due diligence support may be useful for investors who lack time, local market access or comparable-sales experience, but a buyers agent cannot replace a broker, accountant, solicitor or building inspector.
When should I avoid a suburb?
Pause or walk away when the evidence is incomplete or the investment only works under optimistic assumptions. Unresolved supply risk, insurance issues, planning overlays, rent assumptions based on asking price or stretched serviceability are all reasons to pause before proceeding.
The final decision: choose the suburb that fits the strategy
The best suburbs to invest in Australia are not defined by a single year's growth figures or by which city is trending on a property platform. They are defined by four durable questions: Does the suburb have demand that is supported by current evidence? Is the supply manageable for the property type you intend to buy? Can you hold the property under conservative assumptions without compromising the next portfolio decision? Does the purchase move the portfolio closer to your long-term goal?
Those questions do not produce a universal winner. They produce a shortlist that is specific to your position, your timeline and your risk tolerance. Suburb selection is the beginning of the due diligence process, not the end of it.
If you are ready to test a shortlist against those criteria, map out your next property move with Buyers Agency Australia or contact the Buyers Agency Australia team to discuss how a strategy-first approach can support your next investment property decision.
 General
A strategy-led guide to identifying the best suburbs to invest in Australia using demand, supply, yield, infrastructure, and...
Industrial property investment in Australia means buying a commercial asset used for storage, logistics, manufacturing, trade or service operations and assessing whether its income and long-term usefulness fit an investment strategy. The critical checks extend well beyond the advertised yield. Review the location, permitted use, building functionality, tenant strength, lease terms, recoverable outgoings, vacancy exposure, total costs and exit options before making an offer. Property investment carries vacancy, interest-rate, illiquidity and cost risks, so suitability depends on the investor’s goals and capacity to absorb downside. (ASIC Moneysmart)
You find a warehouse with a solid tenant, a long lease and an appealing rent. The income looks durable. But is it?
The building, the lease, the tenant’s operational fit and the replacement-tenant market all need to be assessed together. A strong rent today does not confirm that income is repeatable if the current occupier leaves and the building no longer suits the next generation of users.
Buyers Agency Australia takes a strategy-first approach to industrial, office and retail acquisitions, which means the asset only makes the shortlist once the income has been tested against the downside. This guide works through the same framework, from asset types and lease anatomy to due diligence, financial modelling and acquisition strategy, so you can separate opportunity from evidence.
This article is general educational information only. It is not personal financial, tax, legal, lending, valuation, building or environmental advice. Consult qualified professionals before making any property investment decision.
What Is Industrial Property Investment in Australia?
Industrial property investment involves the direct ownership of a commercial asset used for functional operating activities, including warehousing, logistics, manufacturing, trade, service businesses or storage. Unlike residential property, value is tied closely to the tenant’s operational requirements, the building’s physical suitability and the lease structure governing the income.
The commercial property investment guide from Buyers Agency Australia provides broader context on the commercial asset class. Industrial property sits within that universe but has distinct characteristics that require specific assessment.
What makes an industrial property different from other commercial assets?
| Asset class |
Typical tenant use |
Location logic |
Lease structure |
Vacancy exposure |
Exit consideration |
| Industrial |
Storage, logistics, manufacturing, trade |
Freight access, zoning, labour |
Net or semi-gross, longer terms |
Replacement-tenant pool, building adaptability |
Asset-grade and market depth |
| Office |
Professional services, corporate |
CBD, suburban business park |
Gross, varies by grade |
Precinct supply, demand |
Grade and amenity |
| Retail |
Consumer-facing businesses |
Foot traffic, demographics |
Gross or net, anchor-driven |
Centre performance, trade area |
Lease covenant, centre type |
| Residential |
Individual occupants |
Amenity, schools, transport |
Short-term, regulated |
Low (owner-occupier) |
Broad buyer pool |
Industrial property is a functional operating environment, not simply a large building. The tenant’s workflow, access requirements and power needs shape the asset’s ongoing usability and future reletting potential.
Is Industrial Property a Good Investment in Australia?
Industrial property can suit certain investment strategies, but it is not automatically suitable for every investor. Suitability depends on the specific lease, tenant covenant, building quality, acquisition cost, finance structure and the investor’s risk tolerance.
According to CBRE’s Industrial and Logistics Vacancy Report (1H26), Australia’s national industrial and logistics vacancy rate held at 3.2% as at 30 June 2026, below the sector’s long-term equilibrium threshold of 4%. National net absorption exceeded 1.4 million sqm in 1H26, more than double the level recorded in the second half of 2025. These figures reflect leasing activity across defined asset sizes and markets; they do not apply uniformly to every industrial property or location.
Why investors consider industrial property
Tenant demand for industrial and logistics space has been supported by e-commerce activity, supply-chain requirements, trade businesses, manufacturing operations and storage needs. Business owners may also consider purchasing industrial premises to control their own occupancy costs rather than paying rent indefinitely.
For SMSF (self-managed super fund) trustees, industrial property classified as business real property may be permissible under certain arrangements, but related-party rules, borrowing restrictions and compliance requirements are complex. The Australian Taxation Office provides guidance on SMSF acquisition rules; qualified SMSF, legal and tax advice is essential before proceeding. See also: property investment with superannuation.
Why a higher advertised yield may signal higher risk
A higher-than-market yield on an industrial asset can reflect real value, or it can reflect elevated risk that the market has already priced in. Older buildings with limited access, short lease terms or a thin replacement-tenant pool often carry higher advertised yields precisely because fewer buyers will compete for them.
When a lease expires, the owner may face a period of vacancy, the cost of building upgrades to attract a new tenant, rent incentives and reletting fees. These costs reduce the sustainable net income well below the passing rent figure. The gap between headline yield and owner-level cash flow is one of the most underexamined risks in industrial property acquisition.
What Types of Industrial Property Can You Buy?
Industrial property in Australia covers a range of asset types, each with different occupier profiles, functional requirements and replacement-tenant considerations. The Australian Property Institute’s due diligence guidance highlights that industrial building functionality, including loading access, slab capacity, clear span and power supply, is central to the asset’s investment profile.
Warehouses and logistics facilities
Warehouses and distribution centres are the most recognised industrial asset type. Key functional requirements include clear-span internal layout, adequate ceiling height, slab capacity for forklift and racking loads, hardstand area for truck circulation, loading docks or on-grade roller doors and proximity to freight routes, ports or airports.
Tenant demand for logistics space has been underpinned by e-commerce growth and supply-chain investment, but modern super-prime facilities have outperformed older secondary stock in recent market conditions. An investor acquiring an older warehouse faces a higher risk of competing against newer assets for the next tenant.
Service-industrial units and trade centres
Smaller-bay strata industrial units and trade centre complexes serve trade businesses, service operators and light manufacturers. These assets typically offer a mix of office-to-warehouse ratios, customer-access parking and smaller unit sizes.
Strata titles introduce body corporate considerations and shared infrastructure. Tenant diversification across multiple strata units can reduce single-tenant concentration, but individual unit liquidity on exit may be narrower than a freehold holding.
Manufacturing and specialised industrial assets
Purpose-built manufacturing facilities often carry high replacement-tenant risk. Specialised power connections, chemical handling infrastructure, controlled environments or unique structural modifications may limit the pool of alternative occupiers.
Prior industrial use on any site also raises the possibility of soil or groundwater contamination. A specialist environmental assessment is required before relying on the site’s clean status; a general property inspection does not substitute for this.
| Asset type |
Typical occupier |
Key functional need |
What can make this asset difficult to relet? |
| Warehouse / distribution centre |
3PL operator, retailer, wholesaler |
Ceiling height, loading, hardstand |
Age, location, ceiling clearance below modern benchmark |
| Service-industrial unit |
Trade business, light services |
Parking, customer access, flexible layout |
Body corporate disputes, limited truck access |
| Trade centre |
Building suppliers, trade showrooms |
Customer visibility, parking, display area |
Retail-style fit-out cost, mixed-use zoning complexity |
| Manufacturing facility |
Industrial manufacturer |
Power capacity, structural fit-out |
Specialised infrastructure, contamination history |
| Mixed-use industrial |
Varied tenants |
Flexibility, mixed zoning |
Planning controls, competing asset classes |
How Do You Assess an Industrial Investment Property?
Assessing an industrial property requires working through market, property, tenant and exit in sequence. The Australian Property Institute guidance supports this order of evaluation.
Does the location support the tenant’s operation?
Location must be assessed from the tenant’s operational perspective first. Key factors include access to arterial roads and freight routes, distance to ports and airports, proximity to the tenant’s customer or labour base and the surrounding industrial land uses that signal the precinct’s long-term role.
A location that suits the current tenant but lies outside established industrial precincts may create reletting difficulty if that tenant vacates. Investors should check the relevant council zoning map and local environmental plan (LEP) for permitted uses, and for NSW properties the NSW Planning Portal provides planning controls relevant to each site. State and territory rules differ, so always check the relevant planning authority.
Can another tenant use the building if the current tenant leaves?
This is the replacement-tenant test: would at least two credible occupier profiles be able to use the property without major capital works?
If the honest answer is uncertain, the investor needs to understand the reletting market, likely downtime, required building upgrades, market rent, incentive levels and reletting costs before making an offer. A building that cannot accommodate a broad range of tenants transfers significant risk to the owner at lease expiry.
Five-point assessment framework:
- Location and freight access – confirm suitability for logistics, trade or manufacturing tenants.
- Zoning and permitted use – verify the site can legally host the intended and alternative occupiers.
- Building functionality – assess loading, clear span, ceiling height, slab, power and truck circulation.
- Tenant market depth – identify at least two credible alternative tenant profiles.
- Exit liquidity – assess likely buyer demand at the time of any planned sale.
How Do Industrial Leases Affect Investment Returns?
The lease is the governing document for every dollar of income an industrial investment produces. A long lease is not automatically a good lease; the terms, rent review mechanism, outgoings recovery and make-good obligations determine whether passing rent converts into durable owner income.
Property Council Australia’s commercial due diligence guidance identifies WALE (weighted average lease expiry), tenant covenant, rent reviews and outgoings recovery as central to investment analysis.
What should investors review in an industrial lease?
| Lease item |
Investor question |
Risk if missed |
Evidence required |
| Term and options |
How long is the contracted income? |
Short WALE creates early vacancy risk |
Executed lease and all variations |
| WALE |
What is the weighted average lease expiry across tenancies? |
Misleads on income duration |
Tenancy schedule, lease start and option dates |
| Rent reviews |
Fixed, CPI, market or hybrid? |
Fixed reviews may erode real income |
Rent schedule, review clauses |
| Incentives |
Has rent been discounted at lease start? |
Passing rent overstates sustainable income |
Lease, side deeds, arrears records |
| Make-good obligations |
Who restores the building on exit? |
Owner may inherit a reinstatement cost |
Make-good clause, current building condition |
| Outgoings recovery |
Which costs are recoverable from the tenant? |
Non-recoverable costs reduce net income |
Outgoings schedule, lease definition of recoverable items |
| Assignment and subletting |
Can the tenant transfer the lease? |
Covenant quality may change without consent |
Assignment clause and consent requirements |
| Security |
Personal guarantee or bank guarantee? |
Default may produce no recovery |
Guarantee document, guarantee amount |
Gross rent, net rent and recoverable outgoings
Under a net lease structure, the tenant pays base rent plus recoverable outgoings such as council rates, water, insurance and land tax (where the lease permits). Under a gross lease, the landlord pays most outgoings from the rent received.
The executed lease determines which outgoings are contractually recoverable. Contractual recovery does not guarantee actual cash flow: if the property is vacant, the owner bears all outgoings during that period. Investors must model both the leased and vacant scenarios to understand true owner cash flow.
What Financial Metrics and Costs Should You Model?
Gross yield and net yield are both used in industrial property analysis, but they answer different questions.

Gross yield versus net yield
Gross yield (%) = Annual passing rent / Purchase price x 100
Net yield (%) = Sustainable net income / Total acquisition cost x 100
Sustainable net income deducts non-recoverable outgoings, vacancy allowance, management fees, insurance (where landlord-paid), maintenance, and a capital expenditure reserve from gross rent. It also strips out any lease incentive that inflates the passing rent above the effective rate.
Total acquisition cost adds transfer duty, GST treatment where applicable (industrial property transactions can involve GST implications depending on the structure; seek tax advice), legal fees, valuation, building inspection, finance costs and other transaction expenses to the purchase price.
Illustrative hypothetical example (not a forecast or recommendation):
| Item |
Investor-selected scenario (A$) |
| Purchase price |
2,000,000 |
| Annual passing rent |
120,000 |
| Gross yield (headline) |
6.0% |
| Non-recoverable outgoings |
(12,000) |
| Vacancy allowance (investor-selected: 5% of rent) |
(6,000) |
| Management fee (investor-selected: 5% of rent) |
(6,000) |
| Maintenance and capex reserve |
(8,000) |
| Sustainable net income |
88,000 |
| Total acquisition cost (including estimated transaction costs) |
2,120,000 |
| Net yield |
4.2% |
This example uses investor-selected figures for illustration only. Actual outgoings, vacancy, management costs, capex requirements and transaction costs must be verified for each asset.
What costs should be included before making an offer?
Beyond the purchase price, investors should account for transfer duty (rates vary by state and entity type), legal and conveyancing fees, building inspection, valuation, environmental assessment where indicated, finance establishment costs, land tax (state-based and varies by ownership structure), insurance, ongoing management, maintenance and a vacancy reserve.
Tax treatment, GST applicability and land tax obligations differ by jurisdiction and entity. Confirm the correct treatment with a qualified accountant and solicitor before exchange.
How should an investor stress-test the acquisition?
Model at least three scenarios:
- Current tenant remains, rent reviews perform as per lease.
- Current tenant vacates at first opportunity: model vacancy period, reletting incentives, building upgrade costs and new market rent.
- Interest rates move: apply a higher rate to the finance cost and recalculate cash flow.
If the property remains viable across all three scenarios, the downside risk is understood. If scenario two produces a negative cash flow that the investor cannot absorb, the acquisition carries more risk than the advertised yield suggests.
What Should an Industrial Property Due Diligence Checklist Include?
Due diligence on an industrial asset must identify a reason to proceed, renegotiate on price or conditions, or walk away. Different checks require different professionals: the buyer cannot complete all of them. The property due diligence checklist from Buyers Agency Australia provides a broader framework; the industrial-specific items below extend it.

Title, contract, zoning and planning checks
| Check |
Responsible party |
| Title search: ownership, encumbrances, caveats |
Solicitor |
| Easements and covenants affecting use or access |
Solicitor |
| Zoning and permitted uses under the local environmental plan |
Solicitor, planner or buyers agent |
| Development consents and conditions on current improvements |
Solicitor |
| Future infrastructure or road proposals affecting the site |
Solicitor, planner |
| Compliance with relevant planning controls |
Solicitor |
Building, access and services checks
| Check |
Responsible party |
| Roof condition, structure and slab |
Building inspector or engineer |
| Fire protection systems and compliance |
Fire engineer or building inspector |
| Electrical supply capacity, three-phase power |
Electrical engineer or inspector |
| Loading access, dock height and truck turning radius |
Building inspector, site visit |
| Hardstand condition and load capacity |
Engineer |
| Asbestos register and condition |
Asbestos assessor |
| Stormwater and drainage |
Building inspector |
| Parking provision and compliance |
Building inspector, solicitor |
Environmental and contamination checks
Prior industrial use on a site raises the possibility of soil or groundwater contamination from chemicals, hydrocarbons or other materials. A Phase 1 environmental site assessment, and where indicated a Phase 2 assessment, should be conducted by a qualified environmental consultant before relying on the site’s clean status. Do not assume a site is contamination-free without a current specialist report.
This check is particularly important for manufacturing sites, automotive, chemical, fuel or heavy engineering uses. The relevant state environmental regulator maintains registers of known contaminated sites.
Lease, tenant and income checks
| Check |
Responsible party |
| Executed lease, all variations and side deeds |
Solicitor |
| Rent roll and arrears history |
Solicitor, buyers agent |
| Outgoings schedule and reconciliation |
Accountant |
| Tenant insurance certificates |
Solicitor |
| Personal or bank guarantee documentation |
Solicitor |
| Options and WALE calculation |
Buyers agent, solicitor |
| Incentive deeds and effective rent reconciliation |
Accountant, solicitor |
| Tenant financial information where lawfully available |
Accountant |
What Are the Main Risks of Industrial Property Investment?
ASIC Moneysmart notes that property investment carries vacancy risk, interest-rate exposure, illiquidity and costs that can exceed initial estimates. These apply directly to industrial assets.
| Risk |
Early warning sign |
Potential consequence |
Mitigation |
| Vacancy |
Short WALE, declining tenant enquiry |
Owner funds all outgoings, income stops |
Replacement-tenant test pre-purchase |
| Tenant concentration |
Single occupier in large building |
Full income loss on one default |
Assess tenant covenant, personal guarantee |
| Lease expiry |
Expiry within 2 years of purchase |
Immediate reletting risk |
Price to reflect near-term vacancy probability |
| Obsolescence |
Building below modern clear-height standard |
Limited tenant pool, competing with new stock |
Assess building against current occupier benchmarks |
| Oversupply |
New speculative development nearby |
Downward rent pressure, higher incentives |
Check development pipeline in target precinct |
| Interest rates |
Variable finance cost |
Cash flow turns negative if rates rise |
Model higher rates in stress test |
| Environmental liability |
Prior contamination not assessed |
Owner may inherit remediation costs |
Commission environmental assessment |
| Illiquidity |
Thin buyer market for asset type |
Extended time to sell, forced price reduction |
Confirm buyer depth pre-acquisition |
| Location-specific risk |
Precinct decline, road changes, rezoning |
Reduced tenant demand, value change |
Monitor planning proposals |
Why tenant quality is not enough on its own
A nationally recognised tenant provides a stronger covenant than an unknown entity, but a strong tenant does not remove building risk, lease-expiry risk, building obsolescence risk or the replacement-tenant problem. When a high-quality tenant vacates a building that no longer meets modern functional standards, the owner may face a prolonged vacancy and significant capital expenditure before a replacement occupier is secured.
CBRE’s 1H26 industrial and logistics report noted that vacancy is becoming increasingly concentrated in older prime and secondary assets, while modern super-prime facilities continue to outperform. This bifurcation highlights that asset grade is an independent risk variable from tenant quality.
How Do You Build an Industrial Property Acquisition Strategy?
Strategy must precede search. An investor who selects an asset before defining their objectives, finance capacity, risk limits and ownership structure is making a tactical decision without a strategic framework. The strategy-led property investment process developed by Buyers Agency Australia begins with portfolio role, not the listing.

Start with the portfolio role, not the listing
Before assessing a single asset, define whether the industrial property is intended to provide income, portfolio diversification, business premises, long-term growth potential or a combination. The answer shapes acceptable lease length, tenant risk, building type, location and price point.
SMSF trustees considering industrial assets classified as business real property should confirm the intended purpose, related-party rules and borrowing structure with a qualified SMSF adviser and the relevant ATO guidance before any acquisition proceeds.
Set non-negotiable criteria and walk-away conditions
Seven-step acquisition framework:
- Define the investment objective and time horizon.
- Confirm finance capacity and acceptable loan-to-valuation ratio with a qualified lender or broker.
- Determine the ownership structure with an accountant and solicitor.
- Set minimum acceptable lease quality: WALE, tenant covenant, rent review type and outgoings recovery.
- Define location boundaries and building specification minimums.
- Set the maximum tenant exposure and minimum replacement-tenant profile.
- Establish a walk-away offer price based on net yield after stress-testing.
No property enters the shortlist unless it passes strategy fit, financial fit, lease fit and due diligence feasibility. This pre-search decision gate prevents the common mistake of falling in love with a building before the income has been tested.
For a practical walkthrough of how to move from goals through to settlement, the how to invest in commercial property guide covers the acquisition sequence in detail. Once your strategy is defined, you can book a free strategy session with the Buyers Agency Australia team to work through the framework for your specific situation.
When Does an Industrial Property Buyers Agent Add Value?
Buyer-side support is most useful when the investor needs assistance across multiple workstreams simultaneously: sourcing candidate assets, assessing building functionality, reviewing lease and tenant evidence, coordinating due diligence specialists and negotiating against a well-informed vendor.
| Buyer-side support |
What it involves |
| Strategy and search brief |
Translating investor objectives into a defined asset search |
| Market sourcing |
On-market and off-market candidate identification |
| Lease and tenant assessment |
WALE, rent reviews, outgoings, covenant and replacement-tenant analysis |
| Financial modelling |
Gross yield to net income bridge, stress testing |
| Due diligence coordination |
Managing solicitor, valuer, building inspector, environmental consultant and accountant inputs |
| Negotiation |
Price, conditions, due diligence period, settlement terms |
| Settlement support |
Monitoring conditions, coordinating settlement steps |
How Buyers Agency Australia approaches industrial acquisitions
Buyers Agency Australia is the publisher of this guide. The following section describes its services as provided in current brand material. It is not an independent ranking or recommendation.
Buyers Agency Australia operates as a commercial and residential buyers agency with a national service footprint and a Sydney base, covering industrial, office and retail commercial acquisitions alongside residential investment property. The commercial property acquisition support service is built around strategy-first planning, data-led market assessment, off-market sourcing, lease and financial analysis, negotiation and end-to-end settlement coordination.
Dragan Dimovski, whom the brand presents as a property expert with over 20 years of experience, leads the strategic approach. The framework centres on identifying the industrial asset’s income durability, building usefulness across multiple future occupier profiles, and net income after all costs before making an offer.
Service scope and availability were checked against brand material in August 2026. Confirm current inclusions, availability and any engagement terms before proceeding.
When this support is not the right fit
An investor who prefers to source, assess, negotiate and coordinate every acquisition step independently may not require full-service buyer-side support. Equally, a buyers agent does not replace a solicitor, conveyancer, accountant, financial adviser, lender, independent valuer, building inspector or environmental consultant. Each specialist provides a distinct professional function that falls outside the scope of buyer advocacy.
For investors who want to understand what buyer-side representation covers in practice, the investment property buyers agent guide explains professional responsibilities and boundaries in more detail.
Final Checklist Before Buying Industrial Property
Answer each question before submitting an offer.
- Does this asset fit the defined investment strategy and portfolio role?
- Has the finance capacity and ownership structure been confirmed with qualified advisers?
- Is the net yield acceptable after modelling all non-recoverable costs, vacancy and capex?
- Has the WALE and lease quality been reviewed by a solicitor?
- Is the tenant covenant supported by evidence, not assumption?
- Has the replacement-tenant test returned at least two credible alternative occupier profiles?
- Is the zoning and permitted use confirmed for current and alternative tenants?
- Has a building inspection confirmed structural, loading, fire and services compliance?
- Has the environmental history been assessed by a qualified specialist where prior industrial use occurred?
- What evidence would make you reduce the offer or decline the property?
If any question cannot be answered with evidence rather than assumption, gather the required information before proceeding.
Frequently Asked Questions About Industrial Property Investment in Australia
1. What is industrial property investment in Australia?
It means owning a commercial asset used for storage, logistics, manufacturing, trade or service operations and deriving income from the lease. Asset performance depends on the property, lease, tenant, market conditions and total costs.
2. Is industrial property a good investment in Australia?
It can suit some investor strategies, but suitability depends on the specific lease, tenant covenant, building functionality, vacancy risk, finance structure and individual risk tolerance. It is not automatically suitable for every buyer.
3. What types of industrial property can investors buy?
Warehouses, distribution centres, service-industrial units, trade centres, manufacturing facilities, hardstand and mixed-use industrial assets are all available across Australian markets.
4. How is industrial property yield calculated?
Gross yield equals annual passing rent divided by purchase price. Net yield equals sustainable net income (after non-recoverable outgoings, vacancy allowance, incentives, management, repairs and capex) divided by total acquisition cost.
5. What is WALE in industrial property?
WALE stands for weighted average lease expiry. It indicates the average time remaining across the tenancy schedule, weighted by income. It is one lease metric and does not on its own confirm income security.
6. What should I check in an industrial lease?
Review the lease term, options, rent review mechanism, incentives, outgoings recovery, make-good obligations, assignment rights, security documents, rent arrears history, insurance and permitted use with a qualified solicitor.
7. What due diligence is needed before buying a warehouse?
Legal title, zoning, planning controls, building condition, fire and services compliance, environmental assessment where indicated, lease review, tenant covenant, outgoings reconciliation, insurance and financial analysis. The Australian Property Institute guidance sets out the full scope.
8. Can an SMSF buy industrial property?
SMSF rules can permit certain business real property arrangements, but suitability, related-party rules, borrowing restrictions and compliance obligations require current advice from a qualified SMSF adviser, solicitor and accountant. Refer to ATO guidance on SMSF investment restrictions for the regulatory framework.
9. What are the main risks of industrial property investment?
Vacancy, tenant default, lease expiry, building obsolescence, oversupply, interest-rate changes, environmental liability, illiquidity and location-specific demand shifts are the primary risk categories.
10. When should I use an industrial property buyers agent?
Buyer-side support adds most value when an investor needs sourcing, lease-level assessment, financial modelling, negotiation and due diligence coordination across multiple workstreams. It does not replace legal, tax, finance, valuation, building or environmental professionals.
What Should You Do Next?
The sequence that reduces acquisition risk in industrial property is consistent: define the strategy, confirm finance and ownership structure, set non-negotiable criteria, source and filter candidates, assess the building and lease with evidence, stress-test the net income, complete due diligence with the right specialists, then negotiate on a fully informed basis.
Shortcutting any step transfers risk from the vendor to the buyer.
If you are assessing an industrial asset or building an industrial property acquisition plan, map out your next property move with Buyers Agency Australia through a free strategy session. The team works through strategy, market, lease and financial fit before any property enters consideration.
To speak directly with the team about your situation, contact the team to discuss your objectives and next steps.
 General
A practical guide to industrial property investment in Australia covering warehouses, leases, yield, due diligence, risks and acquisition...