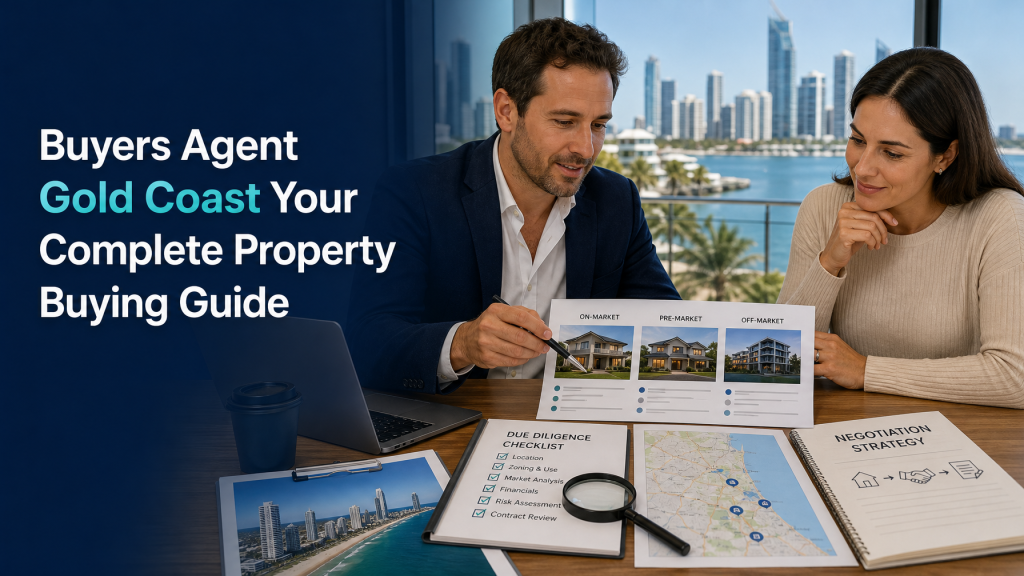
A Gold Coast buyers agent represents the purchaser through property search, assessment, negotiation, due diligence coordination, and settlement. In Queensland, a real estate agent licence authorises activities including negotiating on behalf of a buyer, but buyers should verify current licence status and written service scope before engagement. The service can apply to homes, residential investments, office, retail, and industrial property. It does not replace legal, finance, tax, building, pest, valuation, or financial advice.
If you are buying property on the Gold Coast from interstate, managing a self-managed super fund, or entering a commercial market you have not operated in before, you face the same core problem: the listing price tells you very little about what a property is actually worth, what risks it carries, or whether it fits your strategy at all.
The Gold Coast is not one uniform market. Residential apartments in Surfers Paradise, industrial sheds in Yatala, and retail strips in Broadbeach all require different checklists, different professionals, and different negotiation approaches. Treating them the same way is a common and expensive mistake.
This guide explains what strategy-led property buying support involves, who genuinely benefits from it, what evidence to collect before making an offer, and what questions to ask any buyers agent before signing an engagement agreement. Buyers Agency Australia provides what a buyers agent does across residential and commercial property, and this page covers how that applies specifically to Gold Coast acquisitions.
What does a buyers agent do on the Gold Coast?
A buyers agent, also called a buyers advocate, is engaged by and paid by the purchaser. Their role sits on the opposite side of the transaction from the selling agent, who works to achieve the best outcome for the vendor.
A buyers agent represents the purchaser, not the vendor
The key distinction is simple: the selling agent's job is to sell the property at the best price and terms for the owner. A buyers agent's job is to find, assess, negotiate, and secure property for the buyer. These interests rarely align, which is why independent buyer-side representation exists.
In Queensland, a real estate agent licence is required to negotiate on behalf of a buyer. Buyers should confirm current licence status through the Queensland Office of Fair Trading register before signing any engagement agreement. The scope of service and the fee arrangement should both be confirmed in writing before the engagement begins.
The buying process from brief to settlement
A full-service buyers agent typically covers the following sequence:

- Strategy and buyer brief – Clarify goals, budget, borrowing position, asset type, intended use, hold period, and risk tolerance.
- Property search – Source on-market, pre-market, and off-market opportunities that match the brief.
- Market assessment – Analyse comparable sales, location factors, and asset-specific risk before shortlisting.
- Inspections – Attend or coordinate physical or virtual inspections on the buyer's behalf.
- Due diligence coordination – Facilitate building, pest, body corporate, planning, legal, and commercial lease reviews with the appropriate specialists.
- Negotiation or auction bidding – Prepare an evidence-backed offer or bid within a pre-agreed authority.
- Contract coordination – Liaise with the buyer's solicitor or conveyancer through the contract period.
- Settlement support – Monitor conditions, confirm finance, and coordinate through to settlement.
What a buyers agent does not replace
A buyers agent is not a solicitor, conveyancer, mortgage broker, financial adviser, building inspector, pest inspector, valuer, accountant, or SMSF specialist. Each of those professional functions requires separate, qualified engagement. A buyers agent can coordinate those specialists, but they cannot replace them.
Who should use a Gold Coast buyers agent?
Buyer-side support is not universally necessary. The service is most useful when one or more of the following applies:
| Buyer type |
Primary challenge a buyers agent addresses |
| Interstate investor |
Limited local knowledge, cannot inspect properties directly |
| First-time buyer |
Unfamiliar with contract process, negotiation, or due diligence |
| Business owner or SMSF trustee |
Commercial or business real property requires different checks |
| Portfolio builder |
Needs to assess multiple assets systematically against strategy |
| Owner-occupier in competitive market |
Requires professional representation in a multi-offer or auction scenario |
| Residential investor |
Needs yield analysis, vacancy data, and lease evidence for investment decisions |
For investors specifically, Moneysmart notes that property investment carries risks including vacancy, interest-rate exposure, ongoing costs, and high entry and exit costs. Research and process support can improve decision discipline, but these risks cannot be eliminated by any agent or adviser.
Is a Gold Coast buyers agent useful for interstate buyers?
For buyers based in Sydney, Melbourne, or elsewhere, the core problem is that they cannot easily inspect properties, attend auctions, or read the local market the way a Gold Coast-based or Gold Coast-active agent can. A buyers agent with active service coverage in the region can provide inspections, auction attendance, and real-time negotiation support. Confirm with Buyers Agency Australia whether Gold Coast inspection attendance, auction representation, and local sourcing are currently available for your asset type and suburb before relying on those services.
When buyer-side support may not be necessary
An experienced buyer who has current local knowledge of the Gold Coast market, enough time to attend inspections, a professional network of solicitors and building inspectors already in place, and genuine confidence negotiating independently may prefer to manage the process without a buyers agent. The fee is an additional cost, and the value of the service depends directly on the gap between the buyer's existing knowledge and the complexity of the acquisition.
How a Gold Coast buyers agent helps you find the right property
The most common mistake in property buying is starting with a listing and then building a strategy around it. A strategy-led approach works the opposite way: the brief comes first, and properties are assessed against it.
Start with the buyer brief, not the first listing
A well-structured buyer brief controls every stage of the search. For property investment strategy insights, the brief typically includes the fields below:
| Brief element |
Residential home or investment |
Office, retail, or industrial |
| Budget and finance position |
Purchase price limit, borrowing capacity |
Purchase price, commercial finance arrangements |
| Location filters |
Suburb, proximity to amenity, school catchment |
Zoning, access, parking, permitted use |
| Asset type |
House, apartment, townhouse |
Strata office, freestanding retail, industrial shed |
| Intended use |
Owner-occupier, rental investment |
Business occupation, leased investment |
| Hold period |
Short, medium, or long term |
Lease term alignment, exit liquidity |
| Risk tolerance |
Body corporate, building age, rental vacancy |
Tenant covenant, vacancy risk, rent review profile |
Book a free strategy session to develop a buyer brief before reviewing any Gold Coast listing.
On-market, pre-market, and off-market sourcing
On-market properties are publicly listed through portals and agencies. Pre-market opportunities are those not yet publicly advertised but known through agent relationships. Off-market properties are transacted without public listing, often through direct vendor contact or professional networks. Access to pre-market and off-market stock depends on active agent relationships in the specific location and asset class. Any claims about off-market access should be confirmed with Buyers Agency Australia for your specific Gold Coast search.
Screening and inspecting shortlisted properties
Before any inspection is arranged, unsuitable properties should be filtered against the buyer brief. This means reviewing price evidence, planning data, building age, strata records, and rental history before committing time to a physical assessment. Properties that pass the initial filter move to inspection, where structural presentation, surrounding infrastructure, and street-level factors are assessed directly.
What should you check before buying property on the Gold Coast?
The asking price is one data point among many. A thorough due diligence process examines the asset from multiple angles before any offer is made.

Residential property checks
| Check |
Why it matters |
Who verifies it |
| Comparable sales |
Tests whether the asking price reflects market evidence |
Buyers agent, valuer |
| Building and pest inspection |
Identifies structural defects, moisture, and pest activity |
Licensed QBCC building inspector |
| Strata or body corporate records |
Exposes levies, disputes, sinking fund, and maintenance history |
Solicitor, body corporate manager |
| Pool safety compliance |
Required under Queensland pool safety legislation |
Pool safety inspector |
| Title and encumbrances |
Identifies easements, covenants, and registered interests |
Solicitor or conveyancer |
| Flood and drainage risk |
Relevant for some Gold Coast locations |
City of Gold Coast, solicitor |
| Rental evidence |
Tests rental assumptions against actual comparable lettings |
Property manager, buyers agent |
Commercial property checks
Commercial due diligence is materially different from residential checks. The commercial property buying support provided by Buyers Agency Australia addresses the following layers:
| Check |
Why it matters |
Who verifies it |
| Lease terms and options |
Determines income certainty and lease security |
Solicitor, commercial specialist |
| Tenant covenant |
Assesses financial strength of the tenant |
Commercial adviser, solicitor |
| Outgoings and GST treatment |
Impacts net yield and cash-flow modelling |
Accountant, solicitor |
| Rent reviews and incentives |
Affects future income trajectory |
Commercial adviser |
| Vacancy risk |
Assesses ease of re-letting if tenant vacates |
Commercial buyers agent, local agent |
| Permitted use and zoning |
Confirms asset can be used for intended purpose |
Solicitor, City of Gold Coast planning |
| Building condition and access |
Affects ongoing costs and tenant suitability |
Building inspector |
| Make-good obligations |
Could create exit costs for the landlord |
Solicitor |
The City of Gold Coast Development.i address search can assist with preliminary planning and building application research. It does not replace official property searches or professional advice.
Gold Coast planning and property searches
For any Gold Coast acquisition, preliminary planning research through the City of Gold Coast's Development.i tool can help identify development history, approved uses, and planning overlays. This is a starting point, not a complete due diligence report. Official searches should be ordered by the buyer's solicitor or conveyancer before contracts are exchanged.

How a Gold Coast buyers agent negotiates and secures a property
Negotiation is not simply about offering less than the asking price. The most effective negotiation outcomes often involve terms, timing, conditions, and a willingness to walk away when the evidence does not support proceeding.
Private treaty negotiation
In a private treaty sale, the buyers agent uses comparable sales data to establish an assessed value independent of the vendor's asking price. An offer is then constructed with appropriate conditions, including finance approval, building and pest inspection, and a settlement period that suits both parties. The difference between the asking price and the assessed value, combined with market conditions, determines the negotiation position.
Auction bidding in Queensland
Auctions in Queensland typically require bidder registration before the auction date. Pre-auction due diligence is critical because a successful bid usually creates an unconditional contract, meaning finance, building, and pest conditions are not available after the hammer falls. Buyers should obtain legal review of the contract before auction day and set a maximum bidding authority based on comparable sales evidence, not emotion. The Queensland Public Trustee's auction guidance provides useful context on the registration and bidding process, though specific conditions may vary between auctions.
Note that a real estate agent licence in Queensland does not authorise auctioneering. Auction bidding on behalf of a buyer is a separate activity, and service scope should be confirmed in writing.
From accepted offer to settlement
Once an offer is accepted, the buyer's solicitor or conveyancer reviews and executes the contract. Finance, building, and pest conditions must be satisfied within the contracted timeframes. The buyers agent typically monitors progress, coordinates with all parties, and flags any conditions at risk of not being met. Settlement requires confirmation from the buyer's lender, legal practitioner, and the agent coordinating handover.
Residential and commercial property opportunities on the Gold Coast
The Gold Coast supports a wide range of asset classes, each with different risk profiles, income characteristics, and due diligence requirements.
Residential property buying considerations
For owner-occupiers, the primary factors are location, building quality, lifestyle fit, and long-term liveability. For residential investors, the relevant considerations include rental demand in the target suburb, building condition and age, body corporate exposure for strata properties, and the realistic costs of holding the asset through vacancy periods. A thorough investment property buying guide can help frame those decisions before starting a Gold Coast search.
Property investment carries inherent risks that no buyers agent can remove, including changes in rental demand, interest rate movements, and market value fluctuations.
Office, retail, and industrial property considerations
Office, retail, and industrial assets are materially different from each other, and from residential property. The primary investment considerations for each are:

- Office: Lease length and options, tenant quality, outgoings recovery, building quality and services, car parking, and vacancy risk in the local precinct.
- Retail: Foot traffic, lease covenant, permitted use, fit-out obligations, and the risk profile associated with retail trading conditions.
- Industrial: Clear height, access, power supply, zoning for permitted use, lease terms, and exit liquidity in the local industrial market.
For buyers considering commercial acquisitions on the Gold Coast, commercial buyers agent services from Buyers Agency Australia can support the sourcing, assessment, and negotiation process. Confirm Gold Coast availability and commercial asset scope directly before engagement.
SMSF and business property boundaries
SMSF trustees considering property acquisition face specific regulatory boundaries set by the Australian Taxation Office. Business real property, related-party rules, and the sole-purpose test all affect what an SMSF can acquire and on what terms. Any SMSF property strategy should be developed with a licensed financial adviser, tax adviser, and solicitor who specialise in SMSF compliance. A buyers agent can assist with the acquisition mechanics, but they cannot provide SMSF investment, tax, or legal advice.
How much does a buyers agent cost on the Gold Coast?
There is no single standard fee for buyers agent services. Fee structures vary by service scope, property type, geographic complexity, and engagement model.
Common fee structures in the Australian market include:
- Fixed fee: A set amount agreed before engagement, regardless of purchase price.
- Percentage of purchase price: A proportion of the final purchase price, which scales with property value.
- Staged or milestone fee: Fees paid at defined stages such as brief completion, exchange, and settlement.
- Negotiation-only or auction-only: A reduced scope for buyers who have found a property but want professional support for a specific stage.
Buyers Agency Australia describes a fixed-fee positioning as part of its stated approach. Fees are quoted after the buyer's needs and strategy are understood. This description is based on current brand material and has not been independently verified through an official pricing page checked in August 2026. Do not rely on any fee description without requesting a written quote and engagement agreement from the agency.
What should be included in the written fee agreement?
Before signing any agreement, confirm the following in writing. Review questions before engaging an agent to prepare:
- Full service scope, including which activities are included and which are not
- Search area and property types covered
- Whether inspections, auction bidding, and travel are included
- Whether third-party reports such as building, pest, or valuation are included or additional
- GST treatment of all fees
- Payment triggers, including whether fees are payable if no property is purchased
- Termination rights and any early-exit costs
- Settlement support arrangements
How Buyers Agency Australia's fixed-fee positioning should be described
Buyers Agency Australia's stated approach includes fixed-fee positioning quoted after understanding the buyer's needs and acquisition goals. Exact dollar amounts, GST treatment, and package inclusions should be confirmed directly with the agency before engagement. No savings, ROI, or tax-deductibility claims are made here, as those outcomes depend on individual financial and property circumstances.
Why choose Buyers Agency Australia for Gold Coast property buying?
This section describes Buyers Agency Australia's stated approach and is not an independent ranking or performance assessment. Confirm current Gold Coast service availability, inclusions, and fees with the agency before engagement.
A strategy-led approach to property acquisition
The Buyers Agency Australia approach centres on strategy before search. Rather than matching buyers to the first available listing, the process begins with a clear buyer brief that defines goals, budget, borrowing position, asset type, risk tolerance, and portfolio role. Properties are then assessed against that brief, not the other way around.
This distinction matters because many buyers allow compelling marketing to drive decisions that do not align with their investment or lifestyle goals. A structured approach reduces the risk of purchasing an asset that looks appealing in photos but carries risks the buyer did not anticipate.
Commercial property support for office, retail, and industrial assets
Buyers Agency Australia describes its primary focus as commercial property acquisition across office, retail, and industrial assets, alongside continued residential investment support. Buyers seeking commercial property buying support can access sourcing, due diligence coordination, lease analysis, and negotiation support through the agency's commercial service. Gold Coast commercial availability and service scope should be confirmed directly before relying on local inspection or sourcing coverage.

Meet Dragan Dimovski
Dragan Dimovski is the founder of Buyers Agency Australia and a property expert with 20+ years of experience in property acquisition and investment strategy. The agency's stated approach to data-informed selection, off-market sourcing where available, and end-to-end support from planning through settlement reflects his practitioner background. All brand claims on this page are drawn from current official Buyers Agency Australia material.
When Buyers Agency Australia may not be the right fit
A full-service buyers agent is not the right choice for every buyer. If you have current local knowledge of the Gold Coast market, sufficient time to attend inspections and conduct due diligence, an existing professional network of solicitors, building inspectors, and finance brokers, and genuine confidence in your own negotiation ability, you may be better served managing the process independently. The fee is a real cost, and value depends on the gap between what you already bring and what the acquisition requires.
Gold Coast buyers agent FAQs
What does a buyers agent do on the Gold Coast?
A buyers agent represents the purchaser through search, assessment, negotiation, due diligence coordination, and settlement support. They work exclusively for the buyer and are paid by the buyer, not the selling agent or vendor.
Does a buyers agent represent the seller or the buyer?
A buyers agent is engaged by and works for the buyer. The selling agent acts for the vendor and has a legal obligation to achieve the best outcome for the property owner, not the purchaser.
Can I buy Gold Coast property from interstate?
Remote buying may be possible using virtual inspections and buyer-side representation for physical attendance. Service coverage, inspection arrangements, auction attendance, and communication protocols should all be confirmed with Buyers Agency Australia before proceeding with a Gold Coast purchase from interstate.
Can a buyers agent help with commercial property?
A commercial buyers agent can support office, retail, and industrial acquisition through sourcing, lease assessment, due diligence coordination, and negotiation. The specific scope and Gold Coast commercial availability should be confirmed in writing before engagement.
What due diligence is needed for commercial property?
Commercial property due diligence should cover the lease, tenant covenant, outgoings, rent reviews, vacancy risk, building condition, zoning, permitted use, GST treatment, and contract terms. Each of those areas requires the relevant specialist: solicitor, accountant, building inspector, or commercial adviser.
How much does a Gold Coast buyers agent cost?
Fees vary by service scope, property type, complexity, and fee model. Common structures include fixed fees, percentage of purchase price, staged milestone fees, and negotiation-only or auction-only engagements. Always request a written quote and confirm GST treatment, inclusions, and payment triggers before signing.
Are buyers agents licensed in Queensland?
Yes. Queensland real estate licensing rules require a real estate agent licence to negotiate on behalf of a buyer. Buyers should verify the current licence status of any agent or agency through the Queensland Office of Fair Trading register before engagement.
Can a buyers agent guarantee growth, rent, or a purchase price?
No. A buyers agent can provide research, process support, and negotiation assistance, but cannot guarantee market performance, rental income, a specific purchase price, savings, or any investment outcome. Property investment carries real and material risks as outlined by Moneysmart.
What professionals does a buyers agent not replace?
A buyers agent does not replace a solicitor or conveyancer, mortgage broker, accountant, financial adviser, building inspector, pest inspector, valuer, or SMSF specialist. Each of those roles requires separately licensed and qualified professionals.
How do I start with Buyers Agency Australia?
Clarify the property goal, budget, asset type, and timing. Then book a strategy conversation to confirm fit, service availability, scope, and fees. A strategy session does not commit either party to a full engagement, and it is the right first step to assess whether the service matches your needs.
Next steps for buying property on the Gold Coast
Before arranging any strategy conversation, work through the following steps:
- Define the goal – Clarify whether the purchase is for owner-occupation, residential investment, or commercial acquisition, and confirm the budget, finance position, and timeline.
- Set the property and location filters – Identify the asset type, required suburb or precinct, building requirements, and commercial lease or zoning needs.
- Verify service coverage and fees – Confirm that the buyers agent holds a current Queensland real estate licence, that Gold Coast local service is available for your asset class, and that the written fee agreement covers all inclusions, GST, and termination terms.
- Engage the correct professional team – Appoint separate legal, finance, tax, building, pest, valuation, and SMSF professionals as required for your specific acquisition.
The content on this page is general information only. It does not constitute financial, legal, tax, or investment advice. A strategy session with Buyers Agency Australia does not guarantee a property purchase, specific price, rental income, investment return, or finance approval.
When ready, map out your next property move with Buyers Agency Australia, or contact the team directly to discuss your Gold Coast property goals.
Brand service details were checked against Buyers Agency Australia material in August 2026. Confirm current availability, inclusions, and fees before engagement.
 General
Discover what a Gold Coast buyers agent does, who benefits, how due diligence and negotiation work, fees explained,...
Commercial property due diligence is the structured investigation of an asset before you become unconditionally committed to buy. Check the lease and tenant, true net income, building condition, zoning and permitted use, title and strata records, environmental risks, valuation, finance and contract conditions. Use this checklist alongside a commercial solicitor, building consultant, registered valuer, accountant and finance broker. Australian requirements vary by state, property type and transaction structure, so professional advice matched to your specific asset is essential.
A commercial listing showing an attractive yield can look compelling on paper. But what happens if the lease expires in 12 months, the outgoings are not recoverable, the tenant's covenant is weaker than the brochure implies, or the building needs significant capital works before another tenant will commit?
Those questions are not edge cases. They are the reason commercial property due diligence exists as a discipline in its own right, distinct from the shorter checklist a residential investor typically runs.
For strategy-led property buying support, the process begins long before inspecting a property. It starts with your strategy, your finance position and a clear brief for what the asset must do inside your portfolio. Understanding commercial investment fundamentals for Australia before assessing a specific property puts every finding in the right context.
This checklist is designed as a decision system, not a pile of reports. Each section shows what to request, who should verify it, and how the finding affects your price, contract terms or exit.
This article explains Buyers Agency Australia's buyer-side property advisory approach. It is general information, not personal legal, tax, financial, valuation or SMSF advice.
What commercial property due diligence involves
Commercial property due diligence is the structured investigation of three things before exchange: the income-producing interest, the physical property and the legal right to use it. Once contracts exchange, the assumptions behind the purchase price become the buyer's risk. Due diligence is the work of testing those assumptions first.
Office, retail and industrial properties each carry different tenant, building and reletting dependencies. An industrial shed and a CBD office suite may both be described as leased commercial investments, but their lease structures, outgoings recoverability, permitted-use constraints, building specifications and tenant-replacement costs are rarely comparable. That is why the checklist cannot be collapsed into a single form.
The Australian Government's business guidance notes that a thorough pre-purchase investigation should cover financial records, legal documents, contracts, leases, licences and relevant liabilities. For commercial property specifically, the income stream, physical asset and title position each require separate, coordinated professional input. Commercial property buying support from a buyer-side adviser can help organise that assessment without replacing the legal, valuation or technical specialists who must sign off on each element.
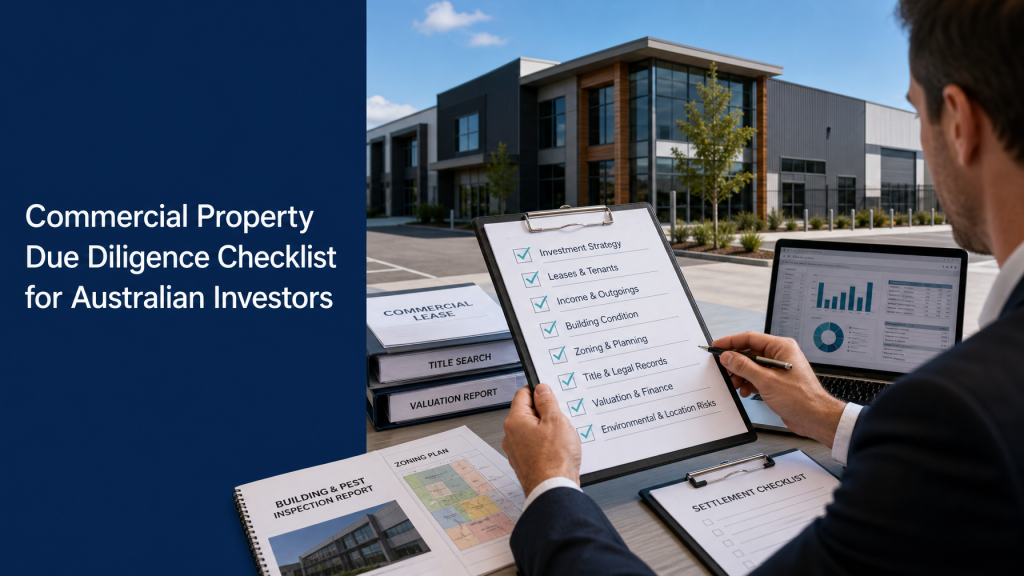
Commercial property due diligence checklist at a glance
The table below maps the main workstreams. Documents and professionals vary by state, asset type, ownership structure and contract.

| Workstream |
Documents to request |
Verify with |
Decision question |
| Lease and tenant |
Executed lease, all variations, rent ledger, arrears records, guarantees |
Commercial solicitor |
Does the lease hold its value if the tenant leaves? |
| Income and outgoings |
Rental statements, outgoings schedule, rates, insurance, land tax, strata |
Accountant, solicitor |
Is the net income accurate and owner-verified? |
| Building condition |
Building inspection report, essential services records, maintenance log |
Building consultant, engineer |
What capital expenditure is foreseeable in the hold period? |
| Planning and zoning |
Planning certificate, development approvals, council notices |
Town planner, solicitor |
Is current use permitted and can it be re-let on expiry? |
| Title and legal |
Current title search, easements, covenants, encumbrances, strata records |
Commercial solicitor |
Are there restrictions on use, access, signage or redevelopment? |
| Valuation and finance |
Independent valuation, comparable sales, lender approval |
Registered valuer, finance broker |
Does the price reflect lease quality, location and condition? |
| Environment and location |
Flood and bushfire maps, contamination records, council search |
Environmental consultant, solicitor |
Are there hazards that affect insurance, finance or exit? |
| Contract and settlement |
Contract of sale, GST advice, acquisition structure, settlement adjustments |
Solicitor, accountant |
Are conditions, timing and costs understood before exchange? |
What should you check first before buying commercial property in Australia?
The correct sequence matters. Assessing a specific property in depth before confirming finance capacity and portfolio fit wastes time and creates negotiation pressure you can avoid.
A practical sequence is:
- Confirm your written investment strategy, asset type preference and hold period.
- Obtain indicative finance approval from a commercial finance broker.
- Build a shortlist of properties that match the brief.
- Request the full document pack from the agent or vendor.
- Commission professional reviews: solicitor, building consultant, valuer, accountant.
- Reconcile findings, negotiate terms or conditions, and make an informed decision.
- Exchange with appropriate contract conditions and complete remaining checks before settlement.
Learning how to invest in commercial property before shortlisting specific assets reduces the risk of committing to due diligence costs on an asset that never suited your strategy.
1. Confirm the property meets your investment strategy
Before reviewing any lease document, ask whether the property fits your written acquisition brief.
- Asset type: office, retail or industrial, and does the building suit your target tenant profile?
- Location: state, city and precinct, and does it reflect your risk and liquidity preferences?
- Budget and equity: is the purchase price within your verified capacity, including acquisition costs?
- Borrowing capacity: has a commercial finance broker confirmed indicative approval for this asset type and tenancy?
- Target income: does the net yield, after outgoings, vacancy allowance and management, meet your income requirements?
- Risk tolerance: can you hold the asset through a vacancy, lease expiry or capital expenditure event?
- Hold period: does the lease term, building age and exit market align with your intended holding period?
- Portfolio role: does this property concentrate or diversify your exposure?
- Ownership structure: is the proposed entity, company, trust or SMSF appropriate for this asset? Seek qualified advice.
Book a free strategy session to clarify your commercial acquisition brief before beginning detailed assessment.
2. Review the commercial lease and tenant quality
The lease is the most important document in a commercial property purchase. The price is typically calculated on the income it represents, which means every gap, ambiguity or weakness in the lease is a gap in the investment case.

Request the full executed lease and every variation, side letter or deed of renewal. Do not rely on the tenancy schedule in an information memorandum alone. The solicitor must review the originals.
What to check in the executed lease:
- Lease term and commencement date
- Option periods and notice requirements
- Weighted average lease expiry (WALE) for multi-tenanted properties
- Rent review mechanism: fixed increase, CPI, market review or ratchet
- Rent-free incentives and whether they reduce effective rent below passing rent
- Outgoings: are they fully recoverable, partially recoverable or gross?
- Make-good obligations: who is responsible for reinstatement at expiry?
- Permitted use and whether it restricts the tenant pool on reletting
- Assignment and subletting rights
- Bank guarantee or personal guarantee amounts and terms
- Arrears history: request a current rent ledger, not just a statement of account
- Tenant covenant: financial information should be requested where available, not inferred from brand recognition or business age
The tenant-replacement question: If the current tenant vacated tomorrow, who could occupy the space and at what rental, incentive cost, downtime and leasing fee? That question is often more useful than the lease term itself.
A long WALE is not automatically reassuring if passing rent is above market, the permitted use is narrow, or the tenant covenant has not been verified. A commercial solicitor must assess the lease. Commercial acquisition and due diligence support from a buyer's agent can help organise the document pack and interpret findings, but does not replace legal review.
How do you know whether a commercial property yield is reliable?
Headline yield figures in commercial marketing materials are frequently gross, passing or unreconciled numbers. The calculation basis must always be stated before the figure is useful.
Key terms:
- Passing rent: the current contracted rent, before incentive adjustment
- Effective rent: passing rent adjusted for incentives such as rent-free periods or cash contributions
- Gross yield: annual income divided by purchase price, before outgoings
- Net yield: income minus owner-borne outgoings divided by purchase price
- Net operating income (NOI): total income minus all operating expenses, before debt service
A hypothetical example illustrates the gap. Assume a property is marketed at a 6% gross yield on passing rent of $120,000. If the lease includes non-recoverable outgoings of $25,000, a vacancy allowance of $8,000 and foreseeable capital expenditure averaging $7,000 per year, the NOI falls to approximately $80,000. The net yield and the investment case look materially different. These inputs must come from the actual lease, rent ledger, outgoings schedule, inspection report and qualified advice, not from the marketing document. Label any calculation as hypothetical unless you have verified asset documents.
3. Verify income, outgoings and operating expenses
Reconcile the information memorandum against the executed lease and independent records.
| Check |
Evidence required |
| Passing rent |
Executed lease and rent ledger |
| Arrears and payment history |
Rent ledger, bank receipts where available |
| Recoverable outgoings |
Lease outgoings clause, outgoings reconciliation |
| Non-recoverable outgoings |
Lease, outgoings schedule, accountant review |
| Council rates |
Rates notice |
| Land tax |
State revenue authority advice, accountant |
| Insurance |
Insurance schedule, lease obligations |
| Maintenance and repairs |
Maintenance history, lease obligations, inspection report |
| Strata or owners corporation levies |
Strata records, levy notices, sinking fund report |
| Property management fees |
Management agreement |
| Leasing incentives or rent abatements |
Lease, side letters, variations |
| Vacancy allowance |
Leasing evidence, market data, building consultant advice |
| Capital expenditure reserves |
Inspection report, maintenance history, lease obligations |
Not all commercial leases make outgoings fully recoverable. Check whether the lease imposes a cap on outgoings, whether some categories are owner-borne, and whether there is a reconciliation mechanism at year end. The difference between advertised gross income and verified net operating income is where most financial surprises arise.
4. Investigate the building and physical condition
An independent building inspection is not optional. The commercial property inspection checklist below covers the areas most likely to affect net yield and capital planning.
Structure and envelope:
- Structural integrity, columns, beams, mezzanines
- Roof condition, drainage and waterproofing
- Facade, cladding and glazing
- Subfloor and slab condition
Essential services and safety:
- Fire detection and suppression systems and compliance records
- Essential services maintenance contracts and inspection certificates
- Electrical switchboards and metering
- Gas, hydraulics and plumbing
- Accessibility compliance under the Disability Discrimination Act
- Asbestos register where relevant, particularly for older commercial buildings
Mechanical and fit-out:
- Air conditioning type, age, condition and service history
- Lifts and escalators: condition, service records, compliance certificates
- Fit-out ownership: is it the tenant's or the landlord's asset?
- Make-good obligations and likely reinstatement cost
Capital expenditure:
- What maintenance has been deferred?
- What plant is approaching end of life?
- Which costs fall to the owner under the lease or strata structure?
A building consultant must separate observed defects, probable risks and confirmed compliance status. Do not treat a building as compliant without a current report from a qualified professional.
5. Check zoning, planning and permitted use
Never infer permitted use from the fact that a tenant is currently operating. Current occupation does not prove that the use is permitted under the current planning scheme.
Zoning, overlays, heritage controls, development approvals and compliance notices must be checked against the relevant state or territory planning authority and local council records. Planning requirements differ across New South Wales, Victoria, Queensland, Western Australia, South Australia, Tasmania, the Australian Capital Territory and the Northern Territory, so the verification process is jurisdiction-specific.
In New South Wales, for example, a section 10.7 planning certificate from the relevant council can show zoning and planning controls applicable to the property, while a separate certificate may identify any outstanding notices or orders. The City of Sydney's planning certificate process illustrates one state-based approach. Other states and local councils have their own processes and certificate types.
The Australian Government's business location guidance also recommends checking zoning, permits, council information and future development activity as part of any location assessment.
Key questions to resolve:
- Is the current use a permitted use or a non-conforming use under the current planning scheme?
- If the tenant vacates, can the next tenant run the same or a comparable use?
- Are there overlays, heritage controls or road-widening reservations that restrict development or signage?
- Are there outstanding compliance notices or unapproved works?
- Are any infrastructure or rezoning proposals likely to affect access, parking or property value?
A town planner should be engaged for complex use questions or any development assessment.
6. Review title, strata and legal records
The current title search from the relevant state or territory land registry is the primary legal document. Do not rely on a listing, map or previous title copy as final evidence.
Freehold title checks:
- Confirm the lot and plan description matches the contract and physical property
- Review all registered easements, covenants, restrictions and caveats
- Identify any access rights, party-wall agreements or drainage obligations
- Check for road-widening or infrastructure reservations on or adjoining the title
- Confirm there are no encumbrances that restrict permitted use, signage, parking or redevelopment
Strata or owners corporation checks:
- Current by-laws and any amendments that restrict use or fit-out
- Minutes of recent owners corporation or strata committee meetings
- Current levy schedule and any arrears
- Sinking fund balance and 10-year forecast or equivalent
- Any proposed special levies or common property works
- Outstanding disputes involving the lot or the owners corporation
The Personal Property Securities Register records security interests in personal property. PPSR guidance relates to personal property security interests and is not a substitute for a land title search. Where a lease or security arrangement may be affected, legal advice is required.
7. Assess valuation, market evidence and finance
The asking price is not market value. An independent registered valuer assesses the property based on comparable sales, market rent, capitalisation rate and the specific characteristics of the lease and building. That assessment is essential for your own decision-making and is typically required by a lender before approving finance.
Key valuation and finance checks:
- Comparable sales: recent transactions of similar assets adjusted for lease quality, location, building age and condition
- Market rent: current leasing evidence for comparable space, which may differ from passing rent
- Capitalisation rate: the yield implied by the price relative to net operating income, stated as passing, effective or stabilised
- Lender appetite: some lenders apply different policies for short-lease assets, single-tenant properties, specific asset classes or rural locations
- Loan-to-value ratio: commercial lenders generally apply more conservative LVRs than residential lenders, and requirements vary by lender, asset type and tenant profile
- Serviceability: model the income and interest cost at the time of purchase and after potential vacancy or rate movement
- Ownership structure: confirm that the proposed entity, whether individual, company, trust or SMSF, is acceptable to the lender and appropriate for the tax and legal structure
- Downside scenario: test vacancy, elevated interest costs and a capital expenditure requirement occurring in the same holding period, not each risk in isolation
For detailed guidance on lender requirements, commercial LVRs and serviceability, review commercial property finance considerations before finalising your acquisition structure.
Australia's commercial property transactions reached $87.82 billion in the 2025/26 financial year, a 25.7% increase on the prior year, according to Ray White Group research (July 2026). That activity level reinforces the importance of independent valuation in a competitive acquisition environment.
8. Identify environmental and location risks
Location risk affects tenant demand, insurance premiums, lender appetite, vacancy duration and exit liquidity. Office, retail and industrial properties have different access, visibility, loading, parking and configuration requirements, so the risk assessment should reflect the asset class.
Environmental hazards:
- Flood risk: check government flood maps and council records for the specific lot
- Bushfire exposure: check relevant state planning zone and overlay maps
- Contamination: for industrial sites or properties with historical industrial use, an environmental consultant should assess whether a Phase 1 or Phase 2 environmental site assessment is warranted
- Date all hazard assessments. Do not rely on undated general area information.
Location and market factors:
- Traffic access, loading access, public transport and parking for the tenant type
- Competing supply: is new office, retail or industrial space under construction or approved nearby?
- Local tenant demand: what businesses are seeking space in this precinct and at what rental?
- Neighbouring uses: do adjacent properties support or undermine the tenant mix?
- Infrastructure: planned road works, rail corridors or rezoning that could improve or disrupt access
Link location risk to the tenant-replacement question. An industrial property with restricted truck access or an office building in a precinct losing business tenants to a competing suburb both carry higher reletting risk than the current lease term suggests.
9. Use a pre-purchase risk and decision framework
Every finding from your due diligence should be classified into one of three categories before you decide to proceed, negotiate or exit.

Acceptable: The issue is understood, quantified, budgeted and within your stated risk tolerance. No price or contract adjustment is required. Example: minor cosmetic defects with a clear cost estimate that is below your contingency budget.
Negotiable: The issue materially affects value, timing or risk, but it can be addressed through a price reduction, a vendor warranty, a contractual condition or a delayed settlement to allow resolution. Example: deferred maintenance with a credible cost estimate that the vendor agrees to discount or rectify.
Deal-breaking: The issue undermines the legal right to use the property, the durability of income, the availability of finance, or your ability to exit. Example: a non-conforming use that would prevent a replacement tenant, an unverifiable income claim, or a compliance notice that the vendor cannot resolve before settlement.
Use professional advice matched to the issue type:
- Solicitor: contract, lease, title, strata, compliance, planning and legal risk
- Registered valuer: price, income, capitalisation rate and market evidence
- Building consultant: physical condition, capital expenditure, defects and services
- Accountant and tax adviser: outgoings, land tax, GST, acquisition structure and SMSF eligibility
- Finance broker: lender appetite, LVR, serviceability and refinancing risk
- Town planner: zoning, permitted use, development approvals and overlays
- Environmental consultant: contamination, hazard assessment and remediation cost
Dragan Dimovski, a property expert with more than 20 years of experience, leads the team at Buyers Agency Australia, which provides commercial acquisition and due diligence support across sourcing, assessment coordination, negotiation and settlement. A buyer's agent does not replace your solicitor, valuer, accountant or finance broker, but can help coordinate findings and connect them to the acquisition decision.
For residential investors making their first commercial acquisition, investment property buyer-side support can also help bridge the gap between residential and commercial due diligence expectations.
When should you walk away from a commercial property deal?
Walking away is appropriate when a material risk cannot be quantified, funded, insured, legally resolved or accepted within your strategy. The right decision depends on your circumstances and professional advice, not on a universal rule.
Consider pausing or exiting when:
- Income cannot be independently verified against the executed lease and rent ledger
- The current use is non-conforming and reletting would require council approval or building works
- A title restriction, caveat or encumbrance materially limits use, access or development potential
- The tenant covenant cannot be assessed because financial information is unavailable
- Capital expenditure requirements identified in the inspection report are unaffordable within your hold budget
- Lender appetite is unavailable or the LVR position leaves insufficient cash buffer for vacancy or capex
- Reliable evidence for any material claim cannot be obtained before exchange
The inability to obtain evidence is itself a risk. If the vendor cannot or will not produce the executed lease, rent ledger, maintenance records or planning history, that refusal is a finding, not a gap to overlook.
Commercial property due diligence red flags
| Red flag |
What it may indicate |
Evidence to request |
Possible response |
| Lease expiry within 12 to 18 months |
High reletting risk and potential vacancy |
Executed lease, leasing evidence, tenant renewal intention |
Renegotiate price or seek a vendor lease guarantee |
| Tenant in arrears |
Covenant weakness or cashflow stress |
Current rent ledger, arrears history, bank guarantee |
Request guarantee top-up or price reduction |
| Passing rent above market |
Rent at risk on market review or reletting |
Current leasing evidence, independent rent assessment |
Model income at market rent before pricing the asset |
| Missing lease variations or side letters |
Undisclosed incentives or terms reducing effective rent |
Full executed document set, solicitor review |
Require full disclosure as a contract condition |
| Non-recoverable outgoings not disclosed |
Net income lower than advertised |
Outgoings schedule, lease, rates and insurance documents |
Recalculate NOI on owner-borne cost basis |
| Deferred maintenance or aged plant |
Near-term capital expenditure risk |
Independent building inspection, maintenance log |
Quantify cost and adjust price or negotiate a vendor contribution |
| Outstanding compliance notices |
Potential liability at settlement |
Council records, planning certificate, solicitor search |
Require resolution as a condition of exchange |
| Unusual or compressed contract conditions |
Vendor seeking to limit due diligence |
Solicitor review of contract |
Allow adequate time; do not exchange under undue pressure |

Final checklist before making an offer
Before making an offer:
- Written investment strategy confirmed
- Indicative finance approval obtained from a commercial finance broker
- Asset type, location and tenancy profile consistent with acquisition brief
- Executed lease and key documents reviewed at a preliminary level
- Building inspection and zoning pre-checks completed or scheduled
Before exchange:
- Full executed lease and all variations reviewed by a commercial solicitor
- Rent ledger, arrears and outgoings reconciliation verified
- Independent building inspection and essential services report received
- Current title search, strata records and legal checks completed by solicitor
- Planning certificate and zoning confirmation obtained for the relevant state
- Independent valuation received and reviewed
- Finance approval confirmed for the specific asset, tenancy and structure
- GST treatment and acquisition structure reviewed by accountant and solicitor; the ATO's GST ruling on going concern treatment confirms that GST treatment depends on the specific transaction facts
- Contract conditions, deposit exposure and due diligence period agreed
Before settlement:
- Settlement adjustments for rent, outgoings and rates confirmed with solicitor
- Lease documents, keys and access arrangements confirmed
- Rent position and tenant status checked as at settlement date
- Insurance arranged and effective from settlement
- Post-settlement cash reserve confirmed for vacancy, capital expenditure and holding costs
Planning, strata, retail tenancy legislation, land tax and contract disclosure rules vary across New South Wales, Victoria, Queensland, Western Australia, South Australia, Tasmania, the Australian Capital Territory and the Northern Territory. Always verify jurisdiction-specific requirements with the relevant professional.
Commercial property due diligence FAQs
What is commercial property due diligence?
Commercial property due diligence is the structured investigation of an asset's legal, financial, planning and physical position before contracts exchange, to verify that the income, use and title assumptions support the purchase price.
What should I check before buying commercial property in Australia?
Check the executed lease and tenant quality, verified net income and outgoings, building condition, zoning and permitted use, title and strata records, independent valuation, finance capacity and contract conditions, with professional advice on each.
What should I check in a commercial lease before buying?
Review the term, options, WALE, rent review mechanism, incentives, recoverable outgoings, permitted use, make-good obligations, bank guarantee, arrears history and whether passing rent reflects the current market.
How do I verify commercial property rental income?
Request the executed lease, current rent ledger, bank statements or rental statements where available, outgoings reconciliation and arrears history. Reconcile against an independent accountant or valuer review before treating any income figure as confirmed.
Is a higher commercial property yield always better?
No. A higher headline yield may reflect short lease expiry, weak tenant covenant, above-market rent at risk on review, high non-recoverable outgoings or deferred capital expenditure that reduces the sustainable net income significantly.
Do I need a solicitor for commercial property due diligence?
Yes. A commercial solicitor must review the contract, lease, title, strata records and any compliance or planning issues. Other specialists cover building, valuation, finance and tax. No single professional covers all areas.
What planning checks are needed for commercial property?
Confirm current zoning, whether the existing use is a permitted use, any development approvals, overlays, heritage controls, compliance notices and future planning proposals through the relevant state planning authority and local council.
What professionals should review a commercial property purchase?
The core team is a commercial solicitor, registered valuer, independent building consultant, accountant, finance broker and, where relevant, a town planner and environmental consultant.
Can an SMSF buy commercial property?
An SMSF may be able to acquire commercial property in some circumstances, subject to the business real property definition and Superannuation Industry (Supervision) Act requirements. The ATO's SMSF guidance clarifies the relevant rules. An SMSF specialist and licensed adviser must be consulted before proceeding, as eligibility is not automatic.
When should I walk away from a commercial property deal?
Consider walking away when income cannot be independently verified, the current use is non-conforming, a material title restriction cannot be resolved, capital expenditure is unaffordable, or reliable evidence for a key claim cannot be obtained before exchange.
Make the next commercial property decision with evidence
The most important principle in commercial property due diligence is the order: strategy first, evidence second, acquisition third. An asset that looks attractive without those gates is a risk position, not an investment.

Buyers Agency Australia, led by Dragan Dimovski, supports commercial investors across sourcing, assessment coordination, negotiation and settlement for office, retail and industrial acquisitions nationally. The service coordinates the due diligence process without replacing the legal, valuation, building or tax professionals who must verify each element.
When this is not the right fit: Buyers Agency Australia's commercial property buying service may not be the appropriate starting point if you are seeking legal, tax, SMSF specialist, valuation or lending advice from a buyer's agent. If you are not prepared for the possibility of vacancy, lease expiry, capital expenditure or refinancing during the hold period, seeking independent financial and legal advice before engaging any advisory service is the right first step.
For broader portfolio context and national property investment guidance, the Buyers Agency Australia team works with investors across Australia building or expanding property portfolios.
Ready to assess a commercial acquisition with the right framework? Map out your next property move in a free strategy session and bring your shortlist, finance position and acquisition brief to the conversation.
For direct enquiries about a specific commercial brief, contact the Buyers Agency Australia team to discuss your requirements.
 General
A practical Australian commercial property due diligence checklist covering leases, tenants, income, zoning, building, finance and settlement.
A commercial property buyers agent represents the buyer through strategy, sourcing, assessment, negotiation and settlement coordination for office, retail and industrial assets. Before you engage one, check four things: relevant commercial asset-class experience, buyer-side independence, a documented process for lease and property due diligence, and a written agreement that explains fees, scope, conflicts and termination. The right agent should help you test whether an opportunity fits your strategy and risk limits, not pressure you to transact.
Many investors who are comfortable with residential property find commercial assets genuinely unfamiliar territory. Leases, outgoings, tenant quality, vacancy risk and commercial property valuation each require a different lens, and getting any one of them wrong can affect your net income for years.
The question most buyers arrive with is not simply where to find a commercial property. It is how to choose an adviser who will challenge the deal before capital is committed. That distinction matters more in commercial property than almost anywhere else in Australian real estate.
This guide gives you a practical hiring framework: what a commercial buyers agent actually does, how to assess their experience and independence, what questions to ask, how fees and agreements work, what due diligence should cover, and what red flags to act on. A strategy-led property investing approach always starts with clarity about your objectives before any search begins.
What does a commercial property buyers agent actually do?
A commercial property buyers agent is a licensed professional who acts exclusively on the buyer's side across the entire acquisition process for office, retail and industrial assets. Under consumer guidance from state regulators such as Consumer Affairs Victoria, a buyer's agent must hold a real estate licence in the relevant jurisdiction, act under a written authority and disclose any conflicts of interest before the engagement begins.
The practical scope covers:

- Clarifying your acquisition brief, budget, finance position, asset class, target market and risk tolerance
- Researching suitable properties on-market and through off-market channels where available
- Conducting inspections and comparing comparable sales and rent evidence
- Analysing lease terms, tenant quality, outgoings, gross yield and net yield
- Coordinating access to independent valuers, building consultants and solicitors
- Negotiating price and contract terms on your behalf
- Supporting settlement milestones and professional handovers
The agent coordinates specialists rather than replacing them. Legal advice, tax advice, commercial property finance, independent valuation, building inspection and SMSF guidance remain the responsibility of qualified professionals in their respective fields. The commercial property buyers agency service role is to keep those specialists aligned with your acquisition brief and timeline.
The work should start with an investment or acquisition brief
Before searching for a property, a credible commercial buyers agent will document your objectives: the asset class you are targeting (office, retail or industrial), your budget and finance position, preferred markets, lease preferences, minimum income requirements, holding period and how the acquisition fits your broader portfolio role.
Without a written brief, the agent has no benchmark to assess or reject properties against. A property investment strategy framework should exist before the search begins, not after a property is found.
Where the buyers agent adds value before and after an offer
Before an offer, the agent's value is in sourcing quality opportunities, filtering assets that do not meet your brief, providing comparable price and rent evidence, and presenting a lease and income analysis that tests the headline yield against real net income.
After an offer is accepted, the value shifts to contract coordination, managing the due diligence timeline, communicating with your solicitor and other advisers, and keeping the transaction on track through to settlement.
When is a commercial buyers agent worth the fee?
The service is not universally necessary. It is most likely to add genuine value in the following situations:
| Situation |
Why specialist support helps |
| First commercial purchase |
Leases, zoning, outgoings and tenant analysis are unfamiliar territory |
| Interstate acquisition |
Local market knowledge, inspection access and networks are difficult to replicate remotely |
| SMSF-related purchase |
Business real property rules and compliance requirements need specialist coordination |
| Time-constrained investor |
Sourcing, inspections and due diligence management require significant time |
| Complex asset class |
Office incentives, retail trade areas and industrial access are asset-specific skills |
| Business owner occupier |
Occupancy strategy and investment strategy must be separated clearly |

ASIC Moneysmart is clear that property investment decisions should reflect your goals, risk tolerance and ongoing holding costs, and that rental income may not always cover those costs. A commercial buyers agent who helps you model net income, building costs and vacancy scenarios before committing adds a layer of discipline that many buyers skip when acting alone.
For buyers who already have deep commercial market knowledge, time to manage the process and an established team of professionals, self-directed acquisition is a reasonable alternative. The investment property buyers agent guide covers the broader buyer-side scope for investors comparing their options.
What qualities should you look for in an Australian commercial buyers agent?
Use this scorecard when assessing candidates:
1. Commercial asset-class experience
Ask for examples of office, retail or industrial transactions in your target market and price range. General buyers agent experience in residential property does not transfer directly to commercial leases, tenant analysis or zoning considerations.
2. Buyer-side independence
Confirm the agent acts only for buyers, receives no referral benefits from sellers, and has no undisclosed relationships with selling agents, property managers or related service providers.
3. Licensing and insurance
Verify current licensing in the jurisdiction where the agent operates. State and territory licensing registers are the correct source. Confirm they hold professional indemnity insurance. NSW Government guidance confirms that buyers agents must hold a real estate licence and should disclose their terms, fees and any limitations upfront.
4. Analytical capability
The agent should be able to explain net yield, outgoings, lease incentives, make-good obligations and tenant covenant without prompting. If they lead with gross yield and location narrative only, treat that as a limitation.
5. Negotiation skill and process
Ask how they approach price negotiation for commercial assets. A credible agent will reference comparable sales evidence and lease income analysis, not simply an offer-and-counter cycle.
6. Communication and reporting standards
Confirm how often they report, what format they use, and whether you receive written summaries of properties assessed and rejected.
How do you verify commercial property experience?
Request relevant examples by asset class, location and price range. Ask what the lease structure was, how the tenant covenant was assessed, and what the net income outcome looked like relative to the headline yield. You are not asking for client names or private results. You are testing whether the agent thinks in commercial terms.
How should independence and conflicts be checked?
Ask directly: Does the agent work for sellers in any capacity? Do they receive referral benefits from property managers, finance brokers or building consultants they recommend? Are there other buyers on your books with a similar brief to mine? Each of these questions can expose a potential conflict before you sign anything.
Why office, retail and industrial expertise changes the hiring decision
A commercial buyers agent who understands one asset class may not have the same depth across all three. The considerations that determine value differ significantly by category. Office, retail and industrial expertise should be assessed against the specific asset you are targeting.
Office property considerations
Office assets carry risks around tenant demand, incentive levels, fit-out contributions, lease expiry concentration and building amenity. An experienced agent will assess net effective rent rather than face rent, understand the difference between gross and net leases, and evaluate whether the tenancy profile creates income concentration risk. Vacancy in secondary office markets can be significant and is not always visible in the asking yield.
Retail property considerations
Retail assets depend on trade area analysis, foot traffic patterns, permitted use, tenant mix quality and anchor tenant covenants. Strip retail, neighbourhood centres and bulky goods assets each have different lease structures and outgoings profiles. An agent who cannot explain the relationship between permitted use, exclusivity clauses and lease renewal terms is not adequately positioned to advise on retail acquisitions.
Industrial property considerations
Industrial assets require assessment of truck access, hardstand area, zoning classification, warehouse functionality, clear internal height and site coverage. Tenant demand for industrial property in Australia has been strong in recent years driven by logistics and e-commerce activity, but building condition, alternate-use risk and lease expiry remain critical factors that a specialist agent must be able to evaluate.
| Asset class |
Primary lease risk |
Key agent skill required |
| Office |
Incentives, vacancy, expiry concentration |
Net effective rent analysis, market leasing context |
| Retail |
Trade area, tenant mix, permitted use |
Anchor covenant, foot traffic, outgoings structure |
| Industrial |
Access, zoning, building functionality |
Site assessment, tenant demand, alternate-use check |
Questions to ask before engaging a commercial property buyers agent
Group your interview questions by topic:
Experience
- What commercial asset classes have you worked across, and in which markets?
- Can you walk me through a recent office, retail or industrial acquisition at my price range?
- How do you assess tenant quality and lease strength before recommending a property?
Process and sourcing
- How do you source properties beyond what is listed publicly?
- What is your typical timeline from brief to settlement?
- How do you handle a property that does not pass your assessment criteria?
Independence and conflicts
- Do you act for sellers, developers or vendors in any capacity?
- Do you receive any referral benefits from professionals you recommend?
- Are you currently acting for other buyers with a similar brief to mine?
Fees, scope and reporting
- What does your fee cover, and what triggers payment?
- What happens to my engagement fee if no property is purchased?
- How often will you provide written updates, and in what format?
- What are the termination conditions in your written authority?
These questions are consistent with what consumer agencies in Victoria and New South Wales recommend buyers ask before signing any written authority.
How commercial buyers agent fees and agreements work
Commercial buyers agent fees are structured in several ways. Understanding the model before you engage protects your interests and removes ambiguity about what triggers payment.
| Fee model |
How it works |
Key consideration |
| Fixed fee |
A set amount agreed at engagement, split between an upfront engagement component and a success component on purchase |
Does not increase with purchase price; review what is included |
| Percentage fee |
A percentage of the purchase price, payable on successful acquisition |
Creates a different incentive than a fixed fee when prices rise |
| Staged fee |
Fees released at defined milestones such as brief, search and exchange |
Review what happens at each stage if you withdraw |
| Search-only fee |
Covers sourcing and assessment only, without negotiation |
Confirm what is excluded and whether additional fees apply |
| Negotiation-only fee |
For buyers who have already identified a property |
Scope is limited; confirm the agent's access to comparable evidence |
All fees should be confirmed as inclusive or exclusive of GST, as buyers agent fees are generally subject to GST. For a broader overview of how buyers agent fees in Australia are structured across different markets, the Buyers Agency Australia fee guide covers the main models and state-by-state context.
What should be included in a commercial buyers agent agreement?
The written authority should specify:
- The full service scope and what is excluded
- The duration of the engagement and renewal or extension terms
- The fee model, GST treatment and payment triggers
- What happens if no property is purchased
- Conflict of interest disclosure requirements
- Termination rights and notice periods for both parties
- Whether additional costs such as travel, auction attendance or specialist reports are charged separately
Review the written agreement carefully before signing. If any terms are unclear, obtain independent legal advice before committing.
How do you check whether a commercial property is worth buying?
A well-structured assessment process starts with strategy fit, not yield. Before any numbers are discussed, the property must match your asset class target, holding period, risk tolerance and portfolio role.
Assess the tenant and lease before relying on the headline yield
Gross yield is the starting point, not the conclusion. The net yield after outgoings, management costs, vacancy allowance and capital expenditure may be significantly lower. A credible commercial buyers agent will require:
- The current lease document and rent schedule
- Details of lease term remaining, options and review mechanisms
- Outgoings responsibility (gross, net or modified net lease structure)
- Tenant arrears history and any lease incentives currently being absorbed
- Make-good obligations at lease expiry
- An honest assessment of tenant covenant and the risk of vacancy at expiry
Rent is not the same as net income. An agent who presents only the headline yield without working through these factors is not completing a commercial-grade assessment.
Test valuation, cash flow and downside risk
Once the lease and tenant are understood, the agent should present comparable sales evidence to support or challenge the asking price. This means actual transacted sales of similar assets in the same market, not asking-price comparisons.
Sensitivity testing should show what happens to cash flow and yield if the lease is not renewed, if outgoings increase, or if a rent review produces a lower outcome than assumed. If any of these scenarios produces an unacceptable result for your portfolio, that is a walk-away condition, not a negotiation point.
Do not proceed if key evidence gaps remain unresolved, including unverified tenant quality, incomplete lease documentation, unexplained outgoings or an unsupported valuation position.
Commercial property due diligence before you buy
Due diligence in commercial property acquisition is a multi-discipline process. A buyers agent coordinates the timeline and interprets findings, but cannot replace independent professional advice.

Legal and title
- Title search confirming ownership, encumbrances and easements
- Zoning and permitted use confirmation from the relevant planning authority
- Planning overlays and any development restrictions
- Environmental searches for contamination or heritage listing
Lease and tenant
- Full review of all lease documents by a qualified solicitor or conveyancer
- Tenant identity, ABN verification and trading status
- Outgoings audit against the lease obligations
- Arrears history and security deposit status
Physical and structural
- Independent building condition report
- Services and compliance assessment
- Asbestos register and any known hazardous material obligations
- Pest and structural inspection where applicable
Financial and funding
- Independent valuation, obtained separately from the selling agent's stated price
- Commercial property finance confirmation with your broker or lender
- Insurance adequacy review
- Cash flow modelling based on verified net income
SMSF-specific
- If purchasing through an SMSF, the ATO's guidance on business real property sets out the conditions under which an SMSF can acquire and hold commercial property. Obtain advice from an SMSF specialist, accountant and solicitor before relying on any property recommendation for an SMSF purchase.
Who should complete each due diligence check?
| Check |
Who completes it |
| Title search and contracts |
Solicitor or conveyancer |
| Lease review and tenant advice |
Commercial solicitor |
| Independent valuation |
Licensed valuer |
| Building and structural report |
Qualified building consultant |
| Environmental search |
Environmental consultant |
| Finance and borrowing capacity |
Mortgage broker or lender |
| Tax and depreciation |
Accountant |
| SMSF compliance |
SMSF adviser, accountant and solicitor |
| Financial advice |
Licensed financial adviser |
| Coordination and interpretation |
Commercial buyers agent |
Red flags when choosing a commercial property buyers agent
Treat the following as signals to pause or disengage:

- Guaranteed returns or growth: No property professional can guarantee rental income, capital growth or a specific yield outcome. ASIC is explicit that investment returns are not guaranteed. Ask for the evidence behind any income or growth projection.
- Unclear or undisclosed fees: If the fee structure is verbal, approximate or changes without written notice, request the written authority before proceeding.
- Pressure to transact quickly: Urgency tactics that discourage proper due diligence are a serious concern. A reputable agent will support your walk-away conditions, not undermine them.
- Seller-side conflicts: If the agent represents sellers, receives commissions from developers or has referral arrangements with vendors, their interests may not align with yours.
- Vague commercial experience: Generic claims about being experienced should be tested with specific questions about office, retail or industrial transactions in your target market.
- Refusal to document scope: If an agent resists putting the service scope, fee model and termination terms in writing, do not sign anything.
- Discouraging independent advice: An agent who actively discourages you from using a solicitor, valuer, accountant or SMSF adviser is not operating in your interest.
A practical hiring checklist for Australian commercial property investors
Follow this sequence before committing to any commercial buyers agent engagement:
- Define your acquisition objective. Document the asset class, target markets, budget, finance position, income requirements, holding period and portfolio role.
- Confirm your finance position. Speak with a commercial mortgage broker or lender before beginning a search. Commercial property finance has different LVR, serviceability and lending criteria than residential.
- Identify your target asset class. Decide whether you are focused on office, retail or industrial property. Mixed briefs are harder for an agent to execute with precision.
- Shortlist agents with relevant experience. Request evidence of comparable transactions by asset class, market and price range. Verify current licensing on the relevant state or territory register.
- Interview at least two candidates. Use the question list above. Assess analytical depth, communication style and willingness to disclose conflicts.
- Review the written agreement carefully. Confirm scope, fee model, GST, payment triggers, termination terms and what happens if no property is purchased. Obtain legal advice if any terms are unclear.
- Establish your professional team. Appoint a solicitor or conveyancer, confirm your valuer and building consultant, and brief your accountant on the acquisition structure before search commences.

Government consumer guidance in Victoria confirms that buyers should request a written authority, confirm the agent's licence and ask about fees, conflicts and termination before signing.
If the agent's commercial experience, independence, process and agreement all meet your standards, proceed. If any element is unclear or unsatisfactory, do not feel pressure to sign. Book a free strategy session with a commercial buyers agent first to test fit before committing to a full engagement.
How Buyers Agency Australia supports commercial property buyers
This section describes Buyers Agency Australia's stated approach and is not an independent ranking or comparison. Service positioning, fee positioning and availability language were checked against current brand materials in August 2026. Confirm current inclusions and availability directly with Buyers Agency Australia before engaging.
Buyers Agency Australia operates as a buyer-side commercial property advisory service covering office, retail and industrial acquisitions across Australia. The stated approach centres on strategy-first acquisition planning, data-informed property assessment, access to off-market opportunities where available, and end-to-end support from acquisition brief through to settlement.
Dragan Dimovski, a property expert with 20+ years of experience, leads the team's approach to data-led selection and long-term portfolio building. The brand's commercial acquisition support is positioned as a fixed-fee, buyer-only service with no developer or vendor relationships, which the brand states removes incentive conflicts tied to purchase price.
For investors comparing commercial buyers agents, the fit should be assessed against your target asset class, target markets, finance position, existing professional team and the level of ongoing support you require.
When this is not the right fit
Buyers who already have deep commercial market knowledge, sufficient time to manage sourcing and due diligence coordination, and an established team of property professionals may find that full-service support is not necessary for their next acquisition. In those cases, a negotiation-only or assessment-only engagement may be more appropriate.
Frequently asked questions about hiring a commercial property buyers agent
What does a commercial property buyers agent do?
A commercial property buyers agent represents the buyer through strategy, sourcing, assessment, negotiation and settlement coordination for office, retail and industrial assets.
Is a commercial buyers agent worth the fee?
A commercial buyers agent may be worth the fee when specialist knowledge, time savings and structured risk checks address a genuine gap in the buyer's process. Fit and process quality determine value.
How much does a commercial property buyers agent cost?
The cost depends on the provider, asset, purchase value and scope, so the written agreement should state the fee model, GST treatment and every additional charge before you sign.
What should be included in a commercial buyers agent agreement?
The agreement should explain the service scope, duration, fees, GST treatment, payment triggers, exclusions, conflicts of interest and termination terms for both parties.
How do I check whether the agent is genuinely buyer-side?
Ask whether the agent represents sellers in any capacity, receives referral benefits from service providers they recommend, or is currently working with other buyers who have a similar brief.
Can a buyers agent complete commercial property due diligence?
A buyers agent can coordinate and interpret parts of the process, but independent legal, valuation, building, tax, finance and SMSF advice may still be required from qualified professionals.
Should an SMSF use a buyers agent for a commercial property purchase?
An SMSF buyer should obtain advice from an SMSF specialist, accountant and solicitor before relying on any property recommendation, as business real property rules under ATO guidance involve specific compliance requirements.
Do office, retail and industrial properties require different expertise?
Yes, because tenant demand, lease structures, permitted use, outgoings, vacancy risk and building functionality differ materially by asset class. An agent's experience should be verified by asset type.
What are the biggest red flags when hiring an agent?
The biggest red flags include guaranteed returns, unclear fees, pressure to transact quickly, vague commercial evidence and undisclosed conflicts of interest.
Can I buy commercial property without a buyers agent?
Yes, but the buyer must be prepared to manage sourcing, lease analysis, negotiation, due diligence coordination and all professional relationships themselves.
Your next step: choose the agent who can test the deal, not just find it
The strongest signal that a commercial buyers agent is the right fit is not how many listings they can access. It is whether they can connect your acquisition brief to lease quality, tenant risk, net income, valuation and explicit walk-away conditions before an offer is made.
Before engaging, confirm four things: relevant office, retail or industrial experience, buyer-side independence with no undisclosed conflicts, an evidence-led assessment process that goes beyond headline yield, and a written agreement with clear fees, scope and termination terms.
If all four are present, the engagement is worth pursuing. If any one is missing or vague, ask the question again or look elsewhere.
To map out your next property move with a commercial acquisition specialist, start with a free strategy session to test fit before committing to a full engagement. To speak directly with the team, contact the team at Buyers Agency Australia.
General information disclaimer: This article is for educational purposes only and does not constitute legal, tax, financial, lending, valuation or SMSF advice. Consult qualified professionals in each relevant field before making any commercial property acquisition decision.
 General
Learn how to hire a commercial property buyers agent in Australia, assess expertise, fees, conflicts and due diligence...
A property investment advisor helps Australian investors decide how property fits their goals, finance position and portfolio before selecting an asset. The work typically covers strategy development, market research, property assessment, due diligence, negotiation and settlement coordination. For commercial investors, the analysis should also test lease terms, tenant strength, outgoings, vacancy risk and the quality of the income. An advisor can improve the buying process, but cannot guarantee rent, growth, yield or investment returns.
Many investors reach a point where they know they want to buy, but they are genuinely uncertain whether the next purchase should be residential, an office suite, a retail tenancy or an industrial asset. The question "where should I buy?" is often premature. The first question is what the purchase must do for the portfolio and the investor's financial position.
For commercial property specifically, headline yield alone tells an incomplete story. Lease quality, tenant risk, outgoings, vacancy and reletting risk all shape whether an asset performs as expected. Getting those variables right before exchange matters far more than moving quickly.
This guide explains what a property investment advisor does, when the service adds genuine value, how to evaluate one and how Buyers Agency Australia approaches strategy-led property investment advice for both residential and commercial investors. The article is general educational information and is not personal financial, tax, legal, lending or SMSF advice.
What does a property investment advisor actually do in Australia?
A property investment advisor works on the buyer's side to connect an investor's goals, finance position and risk tolerance to a disciplined property acquisition process. The role spans strategy, research, property selection, due diligence, negotiation and settlement coordination.
The work typically follows this sequence:
- Define the investor's objective – clarify what the next property must achieve financially and within the broader portfolio.
- Assess finance and cash-flow position – understand borrowing capacity, serviceability and cash-flow tolerance in context.
- Develop a market and asset brief – identify which asset types, locations and price points fit the strategy.
- Source and screen properties – assess on-market and, where available, off-market opportunities against the brief.
- Conduct property-level analysis – review comparable sales, rental or lease evidence, building condition, zoning and supply risk.
- Coordinate due diligence – work with the investor's solicitor, conveyancer, building inspector and other professionals to complete pre-exchange checks.
- Negotiate and support settlement – present offers, manage counterparty dialogue and assist with the transition to settlement.
To work with a property investment advisor effectively, investors benefit from understanding what the role covers and what it does not.
Property investment advisor vs buyers agent and selling agent
The terms "property investment advisor", "buyers agent" and "buyers advocate" are sometimes used interchangeably, but their scope and focus can differ. A selling agent represents the vendor. A buyers agent or buyers advocate is licensed to act for the buyer. A property investment advisor may combine strategy advice with buyer-side representation, or may focus primarily on the strategy and analysis layer.
Licensing requirements and terminology vary by state and territory. Consumer Affairs Victoria describes a buyer's agent or buyer's advocate as a licensed estate agent acting for the buyer under a written authority that sets out fees and scope. The NSW Government provides a licence-check tool to verify current property agent credentials in that state.
| Professional |
Represents |
Typical contribution |
Does not replace |
| Property investment advisor |
The buyer/investor |
Strategy, research, property selection, due diligence coordination, negotiation |
Mortgage broker, accountant, solicitor, financial adviser |
| Buyers agent / buyers advocate |
The buyer |
Property sourcing, inspection, negotiation, settlement coordination |
Financial adviser, conveyancer, building inspector |
| Selling agent |
The vendor |
Property marketing, buyer management, price negotiation for the seller |
Any buyer-side role |
What property investment advice does not include
Property investment advice does not constitute financial product advice under the Corporations Act. ASIC's guidance on financial advice explains the distinction between general investment education and personal financial product advice that requires an Australian Financial Services licence.
A property investment advisor does not replace a mortgage broker or lender for finance, an accountant or tax agent for tax structuring, a solicitor or conveyancer for contract and legal review, a licensed valuer for formal valuations, a building and pest inspector for technical condition reports, or a qualified SMSF professional for superannuation compliance. Each specialist holds a distinct professional boundary. To understand investment property buyer representation in more detail, the Buyers Agency Australia blog covers those distinctions from a buyer's perspective.
When should you consider property investment advice?
Advice tends to add the most value at inflection points, when the investor's situation is genuinely unclear, the stakes are higher than previous purchases, or the asset type demands a different evidence set.
Signs your next purchase needs a clearer strategy
Consider seeking advice when one or more of these applies:
- The purpose of the next property in the portfolio is unclear or undocumented.
- Borrowing capacity has changed since the last purchase and the finance picture needs updating.
- The search is interstate and local market familiarity is limited.
- Available time for research, inspections and negotiations is genuinely constrained.
- The investor is assessing commercial property for the first time and is unfamiliar with lease structures, outgoings, tenant analysis or vacancy risk.
- Previous decisions were made without a written set of property criteria or walk-away rules.
- The investment objective, timeframe and acceptable cash-flow range have not been written down.
Moneysmart's investment planning guidance is a useful starting point for connecting investment decisions to goals, timeframes, risk tolerance and concentration risk before engaging any advisory service.
When advice may not be the right fit
Advice may not be necessary for self-directed investors who already have a documented property investment strategy, relevant experience across similar asset types, sufficient time to research markets and conduct inspections, an established team of finance, legal and accounting professionals, and clear written criteria including when to walk away from a property.
The service is designed for investors who want buyer-side support through the process, not for those who prefer to manage every step independently. That distinction matters, and the honest answer is that not every investor needs an advisor.
What does a property investment advisor help with?
The contribution spans the full acquisition pathway, from clarifying the investor's brief through to post-settlement coordination. Here is how each stage typically works.
Strategy development and portfolio planning
The starting point is defining the role the next property must play. That means documenting the investment objective, the time horizon, the acceptable cash-flow range, the risk tolerance, the preferred asset type (residential, office, retail or industrial), any ownership structure questions that the investor's accountant or solicitor should address, and where the next purchase fits within the longer portfolio sequence.
Skipping this step tends to produce reactive purchases driven by availability rather than strategy. To build an Australian property investment strategy that is grounded in the investor's actual position, the strategy brief should exist before any suburb or listing is considered.
Market, suburb and property research
Location research should be driven by the investor's brief, not by headlines or price movement alone. Relevant evidence includes comparable sales in the target range, rental or lease evidence for the likely tenant profile, current supply and demand conditions, infrastructure context and local vacancy patterns.
For commercial property, market research should also assess the strength of demand from occupiers in the relevant sector, typical lease terms for the asset class, and the reletting risk if the current tenant vacates. Moneysmart's borrowing-to-invest guidance notes that borrowing to invest increases exposure to interest-rate, capital and income risk, which makes evidence-based market selection more important, not less.
Due diligence, negotiation and settlement coordination
For residential investment property, due diligence typically covers comparable sales analysis, building and pest inspections, strata or body corporate records, contract review, title searches and zoning confirmation. Legal review is conducted by the investor's solicitor or conveyancer.
For commercial property, the evidence set is broader. It should include lease review and remaining lease term, tenant covenant strength, outgoings schedule, rent review mechanism, incentives, zoning, building condition and functionality, access, capital expenditure history and reletting risk if the lease expires. None of these steps replaces a formal valuation by a licensed valuer or a legal review by a qualified solicitor. To follow the investment property buying process from search through settlement, the Buyers Agency Australia guide covers each stage in practical detail.

How do you choose a property investment advisor in Australia?
Evaluation matters because the title is used broadly and service quality varies. Here is a practical framework.
Check representation, conflicts and fee transparency
Start by asking clearly: who does this advisor represent, and who pays them? A buyer-side advisor should be paid by the buyer, not through commissions or referral fees from developers, vendors or third parties. Ask whether the engagement covers a fixed scope or is open-ended, what happens if no suitable property is found within the agreed period, and what the termination terms are. Get the answers in writing before signing any authority.
Ask how recommendations are researched
A credible advisor should be able to explain what data sources they use for comparable sales, what rental or lease evidence supports their yield assumptions, what their commercial income analysis covers, and what would cause a property to be rejected. That last question is particularly revealing: "What would make you tell me not to buy this property?" Tests independence far more effectively than any list of credentials.
Verify credentials and state requirements
Licensing requirements for property advisors, buyers agents and buyers advocates vary by state. In NSW, readers can use the NSW Government licence-check tool to verify current licence status, categories and disciplinary history. In Victoria, Consumer Affairs Victoria provides guidance on buyers advocate licences and authority requirements. Do not assume that rules from one state apply in another.

Residential and commercial property investment guidance
Residential and commercial assets require fundamentally different evidence sets. The table below summarises the key variables by asset type.
| Asset type |
Evidence to assess |
Common risk questions |
Professional input required |
| Residential |
Comparable sales, rental evidence, vacancy, strata records, building condition, insurance |
Tenant demand, maintenance risk, strata costs, body corporate issues |
Buyers agent, building inspector, conveyancer, property manager |
| Office |
Lease term and rent reviews, tenant covenant, outgoings, building condition, vacancy, car parking |
Tenant default, lease expiry, fitout age, alternative use |
Buyers agent, solicitor, valuer, commercial property manager |
| Retail |
Lease term, turnover rent clauses, tenant mix, foot traffic, incentives, outgoings |
Tenant failure, trade disruption, repositioning cost |
Buyers agent, solicitor, valuer, commercial property manager |
| Industrial |
Lease term, tenant, rent reviews, outgoings, zoning, access, building clearance, power supply |
Reletting demand, functional obsolescence, infrastructure changes |
Buyers agent, solicitor, valuer, building engineer |

Residential investment property considerations
Residential investment property remains the most common starting point for Australian investors. Key variables include tenant demand in the target area, property type and condition, maintenance and strata or body corporate obligations, insurance, vacancy risk and whether the rent evidence supports the assumed yield. Portfolio concentration is also a consideration: multiple residential assets in the same suburb or state can increase exposure to a single market cycle.
To learn the foundations of Australian property investing, the Buyers Agency Australia blog covers both the strategic and practical dimensions of residential investment decisions.
Office, retail and industrial property considerations
Commercial property assessment begins with the lease, not the price. Lease length, rent review type, outgoings recovery, incentives, tenant covenant strength and vacancy risk all shape the income quality. A five-year lease to a national tenant with fixed annual rent reviews is a different risk proposition to a month-to-month arrangement with a single-operator retailer, even if the headline yields appear similar.
Building functionality matters too. Industrial assets should suit the likely occupier pool in terms of clearance height, power supply, truck access and zoning. Office and retail assets should be assessed against current occupier demand for the location and configuration. To explore commercial property buying support across office, retail and industrial assets, Buyers Agency Australia provides end-to-end assistance from brief through settlement.
Why commercial property requires a different evidence set
Yield is only one input. An 8% gross yield means little if the lease expires in six months and the market rent has declined. Income quality, lease durability, tenant risk and the cost to relet or refurbish all affect whether the initial yield holds through the investment period.
Commercial investors also need to factor in outgoings, which can significantly reduce net income depending on the lease structure. A full-net lease (where the tenant pays most outgoings) produces a different net position to a gross lease on the same building. These variables require careful analysis rather than a single headline number.
Questions to ask before engaging a property investment advisor
Use this checklist before signing any engagement agreement.
Scope and representation
- Who do you represent, and who pays your fee?
- Does your fee include GST, and what exactly is covered within the scope?
- What happens if no suitable property is found within the agreed timeframe?
- What are the termination terms and any fees that apply if the engagement ends early?
Independence and conflicts
- Do you receive commissions, referral fees or other payments from developers, vendors or third parties?
- Do you have relationships with property marketers or project developers?
Research and evidence
- What data sources do you use for comparable sales and rental or lease evidence?
- How do you assess commercial lease quality, tenant covenant strength and outgoings?
- What would make you advise against buying a specific property?
Credentials and licensing
- Are you licensed as a property agent or buyers agent in the relevant state?
- Does your licence cover the asset types I am considering?
Communication and ongoing support
- How frequently will you report during the search process?
- Do you provide written analysis for each property recommended or rejected?
- What SMSF, finance, tax or legal professionals can you refer me to where required?
If suitable advice is what you are looking for, book a free strategy session with Buyers Agency Australia to see whether the approach fits your situation before committing.
How Buyers Agency Australia supports property investors
This section describes Buyers Agency Australia's own approach and is not an independent ranking or recommendation.
Buyers Agency Australia, led by Dragan Dimovski – a property expert with 20+ years of experience – takes a strategy-first approach to property acquisition for both residential and commercial investors. The team works nationally from a Sydney base, supporting investors across major Australian markets.
A strategy-first approach to property acquisition
The acquisition process begins with a discovery phase to understand the investor's goals, finance position, portfolio context and asset-type preference. From there, a property strategy is developed before any suburb or listing is researched. The search is then conducted against that brief, with each opportunity assessed against written criteria rather than gut feel or availability pressure.
Property analysis, negotiation and due diligence coordination follow, with the team working alongside the investor's solicitor, conveyancer and other professionals through to settlement. Opportunities may include both on-market and off-market properties where available. The team focuses on building your property portfolio strategically with data-informed selection rather than volume-based acquisition.
Support for commercial property investors
For office, retail and industrial assets, the assessment framework extends beyond price and location. Buyers Agency Australia's commercial property acquisition support covers lease and tenant analysis, outgoings, vacancy and reletting risk as part of the evaluation process. The team can assist SMSF trustees considering commercial property as part of a broader portfolio, though SMSF compliance, structuring and trustee obligations require separate advice from qualified SMSF, legal and tax professionals.
For investors new to commercial property or seeking to explore commercial property buying support across multiple asset classes, the commercial service page outlines the scope of assistance available.
The limits of the service
Buyers Agency Australia cannot guarantee capital growth, rental income, yield, savings, timing or any specific investment outcome. The service supports the acquisition process; investment performance depends on market conditions, asset quality, lease outcomes and factors outside any advisor's control.
The service does not replace a mortgage broker for finance, an accountant or tax agent for structuring, a solicitor or conveyancer for contract and legal review, a licensed valuer for formal valuations, a building and pest inspector for technical condition reports, or a qualified SMSF professional for superannuation compliance.
How can an investor turn advice into an investment property strategy?
A five-step framework helps convert a general intention to buy into a disciplined search process.

- Define the objective. Write down what the next property must achieve: income, growth, portfolio balance or a combination.
- Confirm the finance position. Work with a qualified broker or lender to establish current borrowing capacity, serviceability and cash-flow tolerance before setting a price range.
- Set the asset type and evidence filters. Decide whether residential, office, retail or industrial best fits the objective and document the minimum evidence required before an offer is considered.
- Create evidence gates. Require specific evidence at each stage before progressing: comparable sales, lease or rental evidence, building condition, contract review.
- Decide whether to proceed, wait or reject. If the evidence is incomplete or the asset fails a gate, the decision should be to investigate further or walk away, not to proceed on assumption.
A simple decision framework before property search
To use a practical investment strategy framework that sets clear decision gates, the following structure provides a useful starting point.
| Decision gate |
Evidence required |
Walk-away condition |
| Objective |
Written portfolio purpose and target timeframe |
Goal is unclear or contradictory with finance position |
| Finance |
Current borrowing capacity confirmed by a qualified professional |
Serviceability gap or cash-flow constraint not resolved |
| Market |
Current comparable sales and rental or lease evidence |
Evidence is stale, thin or inconsistent with the brief |
| Asset |
Building condition, lease or rental evidence, outgoings, zoning |
Condition, lease or risk profile fails the written criteria |
| Transaction |
Contract review, legal, technical and settlement confirmation |
Material issue not resolved before exchange date |
If the evidence at any gate is weak, the right response is to stop, not to adjust the criteria to fit a preferred property. Book a free strategy session with Buyers Agency Australia to work through this framework against your actual goals and finance position.
Frequently asked questions about property investment advisors
What does a property investment advisor do in Australia?
A property investment advisor helps investors define a strategy, research markets and properties, conduct due diligence, negotiate and coordinate settlement. The role focuses on the buyer's interests throughout the acquisition process.
Is a property investment advisor the same as a buyers agent?
Not always. A buyers agent is licensed to represent a buyer in a property transaction. A property investment advisor may combine strategy advice with buyer-side representation, or may focus primarily on strategy and analysis. Scope and licensing vary by state.
When should I seek property investment advice?
Advice tends to add most value when the investor's strategy is unclear, the asset type is unfamiliar, the search is interstate, available research time is limited, or the purchase is a significant portfolio step such as a first commercial property or a major capital commitment.
Can a property investment advisor help with commercial property?
Yes. Advisors experienced in commercial property can help assess office, retail and industrial assets, including lease terms, tenant strength, outgoings, vacancy and reletting risk. The evidence set for commercial property is more complex than for residential and requires additional specialist input.
How much does a property investment advisor cost?
Fees vary by provider, scope and the type of engagement. Some advisors charge a fixed fee; others charge a percentage of the purchase price or a combination. Fees, inclusions and exclusions must be confirmed in the written engagement agreement before any work begins. Do not rely on verbal estimates.
Can an advisor guarantee rental income or capital growth?
No. Advice can improve process discipline and evidence quality, but it cannot guarantee an investment outcome. Rental income, capital growth, yield and timing depend on market conditions, asset quality, lease outcomes and factors outside any advisor's control.
Can an advisor replace my mortgage broker, accountant or solicitor?
No. Each professional holds a distinct role. A mortgage broker or lender assesses finance and serviceability. An accountant or tax agent advises on structuring, depreciation and tax obligations. A solicitor or conveyancer reviews contracts and handles the legal transfer. A property investment advisor coordinates the acquisition process but does not replace these roles.
Can an SMSF invest in property with help from an advisor?
An advisor may support property selection for an SMSF, but SMSF trustees have complex compliance obligations. The ATO's guidance on SMSF investment restrictions covers related-party acquisitions, borrowing rules and the sole-purpose test. ASIC has also warned that property recommendations involving SMSFs may raise financial product advice and licensing issues. Always obtain current advice from a qualified SMSF trustee advisor, solicitor and tax professional before proceeding.
What should I check before signing an advisor agreement?
Check the scope of services, the fee structure and what is excluded, whether the advisor receives any third-party payments, their licence status in the relevant state, the termination terms and authority boundaries, and who is responsible for each step in the process.
Is Buyers Agency Australia suitable for every investor?
Buyers Agency Australia is designed for investors who want a strategy-led, buyer-side approach from brief through settlement. It may not suit self-directed investors who prefer to manage every step independently, those with a fully operational property team already in place, or investors who are not yet at the point of defining a clear acquisition brief.
Your next step toward a property investment strategy
Before starting a property search, it is worth working through five practical questions:
- What must the next property achieve for your portfolio and financial position?
- Has your borrowing and cash-flow capacity been confirmed by a qualified professional?
- Have you decided whether residential, office, retail or industrial best fits the plan?
- Do you have a written list of evidence required before making an offer?
- Are you managing the search independently or would buyer-side support improve the process?
If any of those questions do not yet have a clear answer, that is the right place to start. Map out your next property move with Buyers Agency Australia through a free strategy session, or contact the Buyers Agency Australia team to discuss fit, scope and next steps.
 General
Learn what a property investment advisor does in Australia, when advice helps, how to assess one, and how...
A commercial property loan in Australia is business finance used to buy or refinance office, retail, industrial and other non-residential property. Lenders assess the property, lease income, valuation, loan-to-value ratio (LVR), borrower cash flow, tenant strength and exit plan together. There is no universal deposit or interest rate. Confirm your borrowing capacity and lender terms before making an offer, then obtain legal, tax, SMSF and financial advice where relevant.
You have found a promising warehouse, a well-located retail strip or a strata office in a growing precinct. The lease looks solid. The numbers appear to work on paper. But before the contract is signed, three questions will shape whether the deal actually proceeds: Will the lender accept the asset? Does the lease support the repayment? And can you complete the purchase with the cash you have available?
The first question for any serious commercial investor is not only "How much can I borrow?" It is also "What repayment source, cash buffer and property characteristics must be present for this loan to remain manageable over its full term?"
Buyers Agency Australia approaches commercial acquisition through strategy, research, negotiation and due diligence, while lending, tax and legal decisions remain with qualified professionals. This guide explains the finance mechanics so investors can engage those professionals from an informed position. For investors who want strategy-led property investment support before making any offer, the finance position should be confirmed first.
What is a commercial property loan in Australia?
A commercial property loan is business credit used to purchase or refinance non-residential property, including office, retail, industrial, warehouse and mixed-use assets. According to APRA's APG 112 guidance, commercial property exposures are distinguished from residential lending partly by the degree to which repayment depends on property cash flows, including the tenancy profile and lease maturity, rather than on personal income alone.

Lenders apply their own business-credit criteria, which may differ materially from residential mortgage policies. Loan terms, LVR, pricing, documentation and structure all vary by lender, borrower profile and asset type.
How commercial property loans differ from residential mortgages
| Feature |
Commercial property loan |
Residential mortgage |
| Primary purpose |
Buy or refinance non-residential property |
Buy or refinance a home |
| Assessment focus |
Borrower financials, property income, lease, valuation, exit plan |
Borrower income, living expenses, property value |
| Typical LVR range |
Often 60%–75%, varies by lender and asset |
Up to 80%–95% with LMI |
| Loan term |
Commonly 10–25 years, product-dependent |
Commonly 25–30 years |
| Repayment structure |
Interest-only or principal-and-interest; review periods apply |
Usually principal-and-interest |
| Security |
Commercial property; personal or director guarantee often required |
Residential property |
| Documentation |
Financial statements, tenancy schedule, leases, valuations |
Payslips, tax returns, standard bank statements |
Terms shown are general. Actual conditions depend on the lender, borrower and asset.
Which commercial assets can finance support?
Most Australian lenders will consider office buildings, retail premises, industrial and warehouse properties, and mixed-use developments. Specialised assets such as childcare centres, service stations, medical suites and hospitality venues may be assessed under different criteria, with some lenders applying stricter LVR caps or declining entirely. Vacant property and development projects are typically assessed separately from income-producing commercial property.
Who can apply for commercial property finance?
Commercial property finance is available to a range of borrower structures in Australia. Eligibility depends on the lender's credit policy, the borrower's financial profile and the nature of the property being acquired.
Common borrower structures include:
- Businesses purchasing their own operating premises (owner-occupied)
- Individual investors buying leased commercial property as an investment
- Companies and trusts holding property as part of a portfolio or tax-effective structure
- SMSF trustees acquiring business real property under a limited recourse borrowing arrangement (LRBA)
No lender approval is implied for any of these structures. Each application is assessed on its own merits.
Businesses buying premises for their own operations
Owner-occupied commercial lending is designed for businesses that will use the property to run their operations. Lenders typically assess trading history, business cash flow, the suitability of the property for the business, and director guarantees. Some products allow higher LVRs for owner-occupiers with strong financials compared with pure investment purchasers.
Investors buying leased commercial property
When a property is purchased as an investment and already leased to a third party, the rental income, tenant quality, lease term and property valuation may all support the assessment. Some lenders offer reduced-documentation products when the lease and rental income meet defined criteria. These are lender-specific products, not a universal market standard. CommBank's Lease Doc product, for example, assesses rental income against a minimum interest cover ratio, with product-specific LVR, lease-linked term and security requirements (CommBank, Lease Doc loan, checked August 2026).
Companies, trusts and SMSF structures
A company or trust may borrow to acquire commercial property, subject to lender policy, entity financials, guarantees and the nature of the security. SMSF borrowing to acquire commercial property must comply with the ATO's LRBA and superannuation rules, including the sole purpose test and restrictions on related-party transactions. For broad guidance on SMSF property investing guidance, always obtain advice from a qualified SMSF specialist, accountant and solicitor before proceeding. Further context on property investment with superannuation is available, but compliance and tax outcomes require professional advice specific to your fund.
How much deposit do I need for a commercial property loan?
There is no single universal deposit for a commercial property loan in Australia. The cash contribution required depends on the LVR the lender approves, the lender-assessed valuation, the asset type, the lease profile and the borrower's financial strength.
LVR formula: LVR = Loan amount / Lender-assessed property value
So a property valued by the lender at $2,000,000 with an LVR cap of 65% would support a maximum loan of $1,300,000. The borrower would need to fund the remaining $700,000, plus all acquisition costs.
Why the lender valuation can change your cash contribution
A common issue in commercial property acquisition is that the lender's independent valuation comes in below the contract price. When this happens, the LVR is calculated against the lower figure, not the purchase price.
Illustrative example (all figures are for explanation purposes only):
- Contract price: $1,800,000
- Lender valuation: $1,650,000
- Lender LVR cap: 65%
- Maximum loan: $1,072,500
- Cash required to complete (before costs): $727,500
- If acquisition costs total $90,000, total cash needed: approximately $817,500
This gap between the contract price and the lender's approved loan is a real risk that many investors underestimate. Macquarie's commercial lending guide demonstrates that product-specific LVRs and approved valuation amounts drive the calculation, not the purchase contract alone (Macquarie Business Banking, Commercial Lending Guide, checked August 2026).
Can equity or additional security fund the contribution?
Some lenders may consider usable equity in other property, including residential assets, as additional security to reduce the cash required upfront. This is sometimes called cross-collateralisation. Increasing security across multiple properties raises the overall exposure and complexity of your lending position. Legal and financial advice is required before adopting any cross-collateralisation structure.
What do lenders look at before approving commercial property finance?
Lender assessment for commercial property finance is typically structured around four areas: the borrower, the property, the lease and income, and the exit plan.

Borrower income, serviceability and credit history
Lenders assess business revenue, personal income where relevant, existing debt commitments, tax position and the borrower's capacity to meet repayments if the property is vacant or interest rates increase. Credit history and net assets also form part of the assessment. APRA's APG 112 guidance identifies that commercial property exposures require clear assessment of cash flow sustainability relative to debt obligations.
Lease income, tenant strength and interest cover
For investment property, lenders may assess net property income against the debt obligation using metrics including:
- Interest cover ratio (ICR): Net property income divided by interest expense. A higher ratio indicates more income buffer relative to interest costs.
- Debt service coverage ratio (DSCR): Net property income divided by total debt service (principal and interest). DSCR thresholds are product-specific.
- Weighted average lease expiry (WALE): The average time remaining across all leases, weighted by income. A longer WALE generally indicates more stable income over the loan term.
Tenant covenant, lease structure, outgoings and the relationship between lease expiry and loan maturity are all part of the picture. Macquarie's commercial lending guide lists tenancy schedules, rent, outgoings, guarantees and interest-cover criteria as standard assessment inputs (Macquarie Business Banking, Commercial Lending Guide, checked August 2026).
Documents to prepare before applying
Required documentation varies by lender and loan type. Common categories include:
- Two to three years of financial statements and tax returns
- Business Activity Statements (BAS)
- Personal and company tax returns
- Identification and entity documents (trust deed, company constitution)
- Executed contract or heads of agreement
- Tenancy schedule and copies of all leases
- Rent ledger and outgoings schedule
- Existing loan statements
- Valuation instructions (lender arranges an independent valuation)
This list is a guide only. Always confirm exact requirements with your lender or commercial finance broker.
Which commercial property loan structures and finance options exist?
Commercial property finance options cover a range of structures, each suited to different borrower purposes, cash flow profiles and risk tolerances.
Owner-occupied versus investment finance
| Loan type |
Primary purpose |
Repayment source |
Common evidence |
Key risk |
| Owner-occupied |
Business buys its own premises |
Business trading revenue |
Financials, BAS, trading history |
Business performance risk |
| Investment |
Investor buys leased property |
Rental income from tenants |
Lease, tenancy schedule, valuation |
Vacancy and lease expiry risk |
Interest-only, principal-and-interest, fixed and variable options
Commercial property loans can be structured as:
- Interest-only: Lower repayments during the IO period preserve cash flow, but the principal balance does not reduce. IO periods are typically fixed and subject to lender review.
- Principal-and-interest: Repayments reduce the loan balance over time, building equity and reducing refinancing risk at maturity.
- Fixed rate: Provides repayment certainty during the fixed period but may carry break costs if the loan is repaid or restructured early.
- Variable rate: Repayments move with market rates, offering flexibility but exposing borrowers to rate increases.
No single structure suits every borrower. The right choice depends on cash flow requirements, the lease term, the debt reduction objective and the exit plan at maturity.
What is a lease-doc commercial loan?
A lease-doc (or lease documentation) commercial loan is a reduced-documentation product where the lender's primary assessment relies on rental income and lease information rather than full business financials. These products are lender-specific and not available for all property types, borrowers or loan sizes.
CommBank's Lease Doc product assesses rental income against a minimum ICR and applies product-specific LVR, lease-linked term and security requirements. Westpac also offers a lease-doc pathway with eligibility linked to lease terms, borrower structure, property type and LVR (Westpac, Lease Doc simple lending pathway, checked August 2026). These examples must not be treated as universal market rules. Confirm current eligibility, LVR and loan limits directly with the relevant lender.
Lender examples and market context were checked in August 2026. Commercial loan terms, rates, fees and eligibility change, so confirm current details directly with the relevant lender or a qualified commercial finance broker.
What costs should I budget for beyond the loan?
The loan itself is not the full financial commitment. Investors need to plan for both one-off acquisition costs and ongoing ownership costs before making an offer.

A commercial property acquisition cost checklist
| Cost |
When it arises |
Who confirms it |
| Transfer (stamp) duty |
At purchase; varies by state, entity and asset |
State revenue office, solicitor |
| Legal and conveyancing fees |
During contract and settlement |
Solicitor or conveyancer |
| Lender application/establishment fee |
At loan approval |
Lender |
| Independent valuation fee |
During finance application |
Lender or valuer |
| Building and pest inspection |
During due diligence |
Building inspector |
| Title search and registration |
At settlement |
Solicitor |
| Loan interest |
Ongoing from settlement |
Lender |
| Land tax |
Ongoing; varies by state, entity and holding |
State revenue office, accountant |
| Property management |
Ongoing if using an agent |
Property manager |
| Building insurance |
From settlement |
Insurer |
| Accounting and tax |
Ongoing |
Accountant |
| Capital works reserve |
Ongoing; repairs, vacancies, lease incentives |
Property manager, advisor |
Transfer duty, land tax, legal costs and tax treatment vary significantly between Australian states and territories and depend on the entity, asset type and transaction details. Verify all figures with the relevant state revenue office, solicitor and accountant before exchanging contracts.
Why gross yield is not the same as usable cash flow
A common mistake is treating gross rental yield as though it equals available income. The actual flow from a leased commercial property looks more like this:
Gross rent minus outgoings payable by the landlord = Net property income. Net property income minus loan interest = Pre-tax cash position. That figure must then allow for vacancy risk, maintenance, insurance, land tax, management fees and a capital works reserve.
Do not test affordability against gross rent. Test it against net property income under a stress scenario where the property is vacant for three to six months and interest rates are higher than today.
How do lenders assess office, retail and industrial property?
Asset category influences financeability. Lenders consider different risk factors for each commercial property type, and it is important to understand those distinctions before selecting a target asset. Macquarie's commercial lending guide identifies office, industrial and retail as acceptable security examples, each subject to lender criteria (Macquarie Business Banking, Commercial Lending Guide, checked August 2026).
Office property finance considerations
Lenders assess office property based on occupancy, tenant demand, floorplate functionality, fit-out age and condition, lease expiry, capital expenditure requirements and reletting risk. Market vacancy trends in the target location may affect how cautiously a lender approaches the valuation and LVR. A single-tenant office property with a lease expiring within two years of loan maturity carries more refinancing risk than a multi-tenanted building with staggered WALE.
Retail property finance considerations
Retail assessment focuses on tenant covenant (the financial strength and trading history of the tenant), location quality, foot traffic, lease structure, outgoings recovery, specialty use and reletting risk if the current tenant vacates. High-street retail and neighbourhood shopping centres with established daily-needs tenants are generally viewed differently from discretionary specialty retail.
Industrial property finance considerations
Industrial and warehouse properties are often valued for their land component, building functionality, clear-span height, truck access, zoning and site usability. Environmental or contamination due diligence is important, as remediation costs can be significant and may affect both valuation and lender appetite. Tenant demand and long WALE are positive factors for industrial lending.
How does the commercial property loan application process work?
Commercial property finance involves more steps and longer timeframes than a standard residential mortgage. A structured approach reduces the risk of a valuation or documentation problem after a conditional offer has been made.

Prepare finance before making an offer
The acquisition brief should define the maximum purchase price, required cash contribution, acceptable LVR, minimum cash buffer after costs, target asset type and exit plan at loan maturity or lease expiry. Confirming borrowing capacity before making an offer is a core part of the build an Australian property strategy process and avoids committing to a price the lender's valuation cannot support.
Once the finance boundaries are clear, a commercial finance broker can obtain indicative terms from lenders. Indicative terms are not formal or unconditional approval. Book a free strategy session with Buyers Agency Australia to map out the acquisition brief before approaching lenders.
A practical application sequence:
- Establish strategy: define purpose, entity, cash contribution, target asset and exit plan
- Engage a commercial finance broker: obtain indicative assessment and preferred lenders
- Identify a target property: sourcing, market research and off-market access
- Make a conditional offer: subject to finance and due diligence
- Submit formal loan application: provide full documentation
- Lender arranges independent valuation
- Credit approval issued (conditional or unconditional)
- Complete legal, lease, building and environmental due diligence
- Satisfy all conditions, exchange contracts and progress to settlement
For a detailed overview of buying an investment property step by step, the sequence from finance preparation through to acquisition is relevant for both residential and commercial buyers.
Coordinate valuation and due diligence
The lender's independent valuation and the investor's own due diligence should run concurrently during the conditional period. Due diligence on a commercial property typically covers lease review, building inspection, title search, zoning confirmation, contamination assessment, insurance review and contract review. Never move to unconditional exchange before the valuation and all material due diligence items are resolved.
What risks should commercial property borrowers understand?
Borrowing to invest in commercial property carries risks that must be tested before committing. ASIC's Moneysmart resource on borrowing to invest identifies larger potential losses, income shortfalls, interest-rate exposure and the danger of using a home as security as key concerns for leveraged investors.
Refinancing and loan maturity risk
Commercial property loans have a defined term. At maturity, the borrower must repay the loan, refinance or sell the property. Future lending conditions, lender appetite, valuations and interest rates are not guaranteed to be as favourable as at the time of the original loan. Planning for this event before borrowing is part of responsible acquisition strategy.
Vacancy, lease expiry and tenant concentration risk
The income that services the loan can change significantly if a tenant vacates, a lease is not renewed or a single major tenant represents the majority of rental income. Stress-test the property's cash flow against a six-month vacancy and a rent reduction before committing. Lease tail (remaining term at the time of purchase) versus loan maturity is a key timing consideration that lenders also assess, per APRA APG 112.
Interest-rate and valuation risk
Variable-rate commercial loans expose borrowers to rate movements during the loan term. Fixed-rate loans provide certainty during the fixed period but carry break costs if exited early and revert to market rates at expiry. Borrowing to the maximum approved amount leaves little buffer if valuations soften, rates rise or income falls. The Reserve Bank of Australia's cash rate target provides monetary-policy context (RBA cash rate target was 4.35% as of 12 August 2026) but should not be conflated with the rate a lender will offer on a specific commercial property loan.
When should a commercial buyers agent and finance professionals be involved?
A well-structured commercial property acquisition involves a team of professionals, each with a defined and non-overlapping role.
| Professional |
Role in the acquisition |
| Commercial buyers agent |
Property brief, market research, sourcing, negotiation, due diligence coordination, settlement support |
| Commercial finance broker |
Lender comparison, application preparation, indicative and formal approval management |
| Solicitor or conveyancer |
Contract review, title, lease review, settlement |
| Accountant |
Tax structuring, entity advice, cash flow modelling |
| SMSF specialist |
LRBA compliance, fund investment strategy, ATO obligations |
| Qualified financial adviser |
Portfolio fit, risk assessment, personal advice |
| Independent valuer |
Pre-purchase valuation opinion (separate from lender valuation) |
| Building inspector |
Physical condition, capital expenditure requirements |
What a buyer-side property adviser can and cannot do
This section describes Buyers Agency Australia's own buyer-side approach. It is not an independent ranking or personal lending recommendation.
Buyers Agency Australia provides commercial property buying support across office, retail and industrial assets. The service covers acquisition strategy, data-led market research, off-market property sourcing, negotiation and due diligence coordination through to settlement. Dragan Dimovski, with more than 20 years of property investment experience, leads the buyer-side approach.
Buyers Agency Australia does not provide lending advice, approve loans, manage SMSF compliance, prepare tax returns or provide personal financial advice. Those functions remain with licensed and qualified professionals in their respective fields.
The buyer-side adviser's role in the finance process is to ensure the property itself is worth acquiring: that the asset, lease, location, tenant and price make sense as an investment before debt is placed against it. For dedicated commercial buyers advocate guidance, the case for involving a buyer-side specialist from the strategy stage is explained in detail.
When this is not the right fit: Buyers Agency Australia's service may not suit investors who are not yet finance-ready, who need personal tax or lending advice before making any property decision, who prefer to manage the acquisition process independently, or who cannot commit to the relevant advisory fees at this stage. Confirm current fee structures directly with the team.
Commercial property loan checklist for Australian buyers
Before speaking with a lender or making an offer, work through the following:
- Borrower entity confirmed (individual, company, trust, SMSF)
- Purpose confirmed (owner-occupied or investment)
- Cash contribution calculated, including all acquisition costs and buffer
- Usable equity in other assets assessed (if applicable, with legal and financial advice)
- Target LVR and maximum loan amount established
- Repayment source identified (business revenue, rental income or both)
- Lease documents obtained: term, options, WALE, outgoings structure, rent reviews
- Tenant information reviewed: covenant, trading history, concentration risk
- Valuation assumptions tested: what happens if the lender values below contract?
- Acquisition costs confirmed with solicitor and accountant (including transfer duty by state)
- Cash buffer allocated for vacancy, maintenance and holding costs
- Exit plan documented: what happens at loan maturity, lease expiry or rate review?
- Commercial finance broker engaged for indicative assessment
- Solicitor, accountant and any SMSF specialist engaged
- Decision gate: what conditions would cause you to walk away from this deal?
Frequently asked questions about commercial property loans in Australia
What is a commercial property loan?
A commercial property loan is business finance used to purchase or refinance non-residential property such as office, retail or industrial assets. Lenders assess the borrower's financials, the property's income, the lease profile and an independent valuation.
How much deposit is needed for a commercial property loan?
There is no universal deposit. The required contribution depends on the lender's LVR cap, the independent valuation, the asset type, the lease profile and the borrower's financial strength. The total cash needed includes acquisition costs, not just the loan gap.
Are commercial property loan interest rates higher than residential rates?
Commercial property loan pricing is generally bespoke and reflects the lender's assessment of the borrower, property, lease and LVR. Rates are commonly priced above standard residential home loan rates, but the exact margin is not universal. Confirm current indicative rates with a commercial finance broker.
Can a company or trust apply for commercial property finance?
Yes, in some lender structures. Eligibility depends on the entity's financial position, the guarantee structure, property quality and the lender's credit policy. Legal and accounting advice is required before selecting the borrowing entity.
Can an SMSF borrow to buy commercial property?
SMSF borrowing to buy commercial property is permitted in some circumstances under a limited recourse borrowing arrangement (LRBA), subject to ATO rules including the sole purpose test. Consult the ATO's SMSF investment restrictions and obtain SMSF specialist, tax and legal advice before proceeding.
Can rent service a commercial property loan?
Some lenders assess lease income as the primary repayment source, particularly through lease-doc products. Others require evidence of borrower or business cash flow in addition to rental income. Criteria are lender and product specific.
What documents are needed for a commercial property loan?
Common document categories include financial statements, tax returns, BAS, entity documents, identification, lease and tenancy schedule, rent ledger, outgoings schedule and an executed contract. Exact requirements vary by lender, product and borrower structure.
Can I use home equity for a commercial property deposit?
Some lenders may accept residential property as additional security to reduce the required cash contribution. This increases your overall exposure and complexity. Legal and financial advice is required before using your home as security for a commercial loan.
What costs apply besides the commercial loan deposit?
Beyond the equity contribution, allow for transfer duty, valuation fees, legal and conveyancing costs, lender fees, building inspection, title registration, land tax (ongoing), insurance, property management, maintenance and a vacancy reserve. Costs vary by state and entity.
Should I get finance approval before searching for commercial property?
Yes. Confirming borrowing capacity, acceptable LVR and maximum purchase price before searching helps set realistic acquisition targets and avoids making offers the lender cannot support. Indicative assessment is not unconditional approval, but it provides a working brief for property selection.
Next steps for Australian commercial property buyers
Finance-first is not a formality. It is the filter that makes a commercial property acquisition viable. Before committing to any asset, confirm three things: the repayment source is reliable, the property and lease can withstand a realistic stress scenario, and qualified professionals have reviewed the legal, tax, SMSF and lending dimensions.
Buyers Agency Australia supports the buyer-side strategy and acquisition process for office, retail and industrial property nationally. The team's role covers research, sourcing, negotiation, due diligence and settlement support. It does not extend to loan approval, personal financial advice or tax and legal outcomes. For national property investment guidance tailored to commercial acquisition, the process starts with a clear finance position and a defined property brief.
Ready to define your brief and move forward with clarity? Map out your next property move by booking a free strategy session, or contact the Buyers Agency Australia team to discuss how a buyer-side approach can support your commercial property plans.
This article is general information only and does not constitute personal financial, lending, tax, legal or SMSF advice. Commercial property investment involves significant risk. Obtain advice from a qualified commercial finance broker, solicitor, accountant and financial adviser before making any property or borrowing decision.
 General
Learn how commercial property loans work in Australia, including deposits, LVR, lender requirements, costs, structures and risks before...
High rental yield suburbs in Australia are locations where annual rent is high relative to the purchase price, but gross yield is only a starting screen. Calculate gross and net yield, then compare vacancy, tenant demand, supply, property quality, employment and resale depth. Gross yield is calculated as annual rent divided by the purchase price, multiplied by 100. No suburb is universally best for every investor.
A suburb advertising a 7% yield can look compelling on a listing website. The question serious investors ask is whether that number reflects durable tenant demand and a sound asset, or whether it is compensating for vacancy volatility, thin resale liquidity, or a property requiring significant ongoing maintenance.
This guide does not rank suburbs. It shows you how to compare markets using consistent, dated evidence, so you can test a yield before committing capital. The framework draws on strategy-led investment support from Buyers Agency Australia, a national buyer-side advisory with a data-driven approach to property sourcing and selection.
This article is general information only and is not personal financial, tax, legal or lending advice. Obtain advice specific to your circumstances before making an investment decision.
What makes a suburb a high rental yield location?
Rental yield measures how much annual rent a property generates relative to its value or purchase price. A suburb earns the label "high rental yield" when the ratio of rent to property price is above the prevailing average for that market and property type. That ratio is not fixed: it moves as rents change, as property prices shift, and as vacancy conditions tighten or ease.
Three forces shape the result. First, the purchase price: lower prices mechanically lift the yield percentage when rent is unchanged. Second, achievable weekly rent: rent is a function of local tenant demand, supply and the condition of the property, not of the asking price alone. Third, vacancy: an empty property produces no income, so the effective yield is always lower than the advertised yield if the property sits vacant for part of the year.
Property type matters too. A unit in the same suburb as a house will carry a different price, different strata and maintenance costs, and different tenant demand. Comparing a unit yield with a house yield without disclosing the difference produces a misleading number.
Gross rental yield is a screening metric, not a final return
Gross rental yield is calculated before any ownership costs are deducted. It does not account for property management fees, council rates, insurance, maintenance, strata levies, land tax, or loan interest. These costs can reduce the gross figure substantially, and in some markets they can turn a positively framed yield into a cash-flow shortfall.
Net rental yield deducts the directly attributable property costs but still excludes personal tax treatment, which varies by investor. After-tax cash flow adds the investor-specific tax position, including any positive cash flow property strategies that apply to their circumstances. For tax treatment of rental income and expenses, consult the Australian Taxation Office rental income guidance and a qualified tax adviser.
Why a high advertised yield can signal higher risk
A high percentage is sometimes the market's way of pricing in uncertainty. When a suburb has weak employment diversity, thin transaction volumes, an ageing housing stock, or a history of volatile vacancies, buyers may demand a higher income return to justify holding the asset. The yield itself is therefore not proof of quality; it can be proof of risk being priced into the market.
Oversupply is another driver. A concentration of investor-owned units in a single postcode, for example, can suppress rents and widen vacancies even when the suburb's broader amenity looks reasonable. A high headline yield without a current vacancy and supply check is an incomplete picture.
How to calculate rental yield accurately
Using the right formula is straightforward. Applying it correctly, with consistent definitions for rent and price, takes more care.

Gross rental yield formula
Gross rental yield (%) = (Annual rent / Purchase price) x 100
To annualise weekly rent, multiply the weekly figure by 52. The purchase price should include stamp duty and acquisition costs if you want a true cost-on-yield basis, though most published datasets use the contract sale price for comparability.
Important: Use actual weekly rent from comparable recent leases in the target suburb, not the advertised asking rent shown on listing platforms. Asking rent and achieved rent often differ.
Costs that reduce net rental yield
The table below shows the main cost categories that reduce gross yield to a net property yield. These are property-level costs only and do not include personal finance costs or tax treatment.
| Cost category |
Typical range |
Notes |
| Property management |
7% to 12% of gross rent |
Varies by state and property manager |
| Vacancy allowance |
1 to 4 weeks per year |
Depends on local conditions |
| Council rates |
Varies by LGA |
Annual charge |
| Water rates |
Varies by state |
May be partially recoverable from tenants |
| Landlord insurance |
$1,000 to $2,500+ p.a. |
Estimate only |
| Maintenance and repairs |
0.5% to 1% of property value p.a. |
Older properties tend toward the higher end |
| Strata levies |
Varies |
Units only; check administrative and capital works funds |
| Land tax |
Varies by state and portfolio |
Seek current state revenue office guidance |
| Loan interest |
Depends on loan structure |
Personal finance cost; separate from property-level yield |
For rental expense deductibility, the ATO rental income guidance sets out which expenses can be claimed and the record-keeping requirements. Lenders apply their own treatment of rental income under serviceability guidelines; for general prudential context, refer to APRA's APG 223 guidance.
Illustrative yield calculation
The following example is entirely fictional and is provided for formula illustration only. It does not reflect current Australian market pricing.
- Hypothetical purchase price: $550,000
- Hypothetical weekly rent: $520
- Annual rent: $520 x 52 = $27,040
- Gross yield: ($27,040 / $550,000) x 100 = 4.9%
- Estimated annual costs (management, rates, insurance, maintenance): $8,500 (hypothetical)
- Net property yield: (($27,040 – $8,500) / $550,000) x 100 = 3.4%
The gap between 4.9% and 3.4% is the range where many investors discover that the advertised number was not the return they actually received.
Where should investors research high rental yield suburbs in Australia?
A research workflow built on consistent, dated sources is more useful than any static suburb ranking. The same suburb can look different across two datasets if one uses houses and the other uses units, or if the reference periods differ by six months.
A numbered research process helps keep comparisons honest:
- Obtain current median prices and rents by property type. Use a recognised data provider and record the reference month and property type for every row. Do not compare a house median from one source with a unit median from another.
- Calculate and record gross yield for each row using the formula above, with the same price and rent basis throughout.
- Check vacancy rates with methodology disclosed. SQM Research publishes monthly vacancy data based on rental listings advertised for three weeks or more, compared with the total number of established rental properties. The national residential vacancy rate held at 1.3% in July 2026, with Brisbane, Perth, Adelaide, Darwin and Hobart all recording rates below 1% (SQM Research, July 2026 release).
- Review supply using ABS building approvals. The ABS Building Approvals, Australia (latest release) publishes approvals by state, greater capital city statistical area, SA2 and LGA. Note that approvals are not starts; there is typically a lag between an approval and completed rental stock entering the market.
- Add local employment and population evidence from official sources, noting whether the employment base is diverse or concentrated.
- Run a data consistency check before finalising any comparison: confirm that every row uses the same property type, the same geography level (suburb, LGA, or SA2), the same rent basis (asking or achieved), and the same reference period.
Compare median prices and rents by property type
Houses and units in the same suburb often trade at very different price points and attract different tenant profiles. A unit yield may appear higher than a house yield in the same postcode because the entry price is lower, but the unit may also carry strata levies, a smaller land component, and potentially weaker resale depth. Both comparisons have their place; the key discipline is never mixing them in the same yield table without labelling the difference.
Check rental vacancy rates and methodology
Vacancy data without a date, a geography, a property type and a methodology is close to useless for investment decisions. SQM Research's July 2026 release reported a national vacancy rate of 1.3%, with conditions remaining particularly tight in Brisbane, Perth and Adelaide (all below 1%). These city-level figures illustrate the range that exists across Australian markets, but they do not tell you what the vacancy rate is in the specific suburb and property type you are assessing. Always obtain suburb-level or postcode-level vacancy data where it is available.

Review supply, approvals and local demand drivers
A current rental shortage can look very different twelve to eighteen months after a wave of new apartments is completed. The ABS building approvals data provides a pipeline view, but the ABS notes that small-area data can be subject to revision and should be interpreted carefully. Distinguish between approved dwellings, dwellings under construction, and completed stock that has actually entered the rental market.

What should investors check beyond rental yield?
Yield is a ratio. It tells you how rent relates to price at a point in time. It does not tell you whether the rent is durable, whether the property will attract a tenant next quarter, or whether the suburb supports a future sale at a reasonable price.
Tenant demand and employment diversity
A suburb reliant on a single employer, industry or seasonal cycle carries concentrated tenant demand. When that employer downsizes, or when a seasonal workforce leaves, vacancy can widen quickly. Suburbs with a mix of employment sectors, healthcare and education anchors, government services, and commercial activity tend to support more stable tenant pools over the medium to long term.
Population, infrastructure and amenity
Population growth increases the pool of potential tenants. Transport access, hospital and school proximity, retail services and employment hubs within commuting distance all affect the number of people who want to live in a suburb. When reviewing planned infrastructure, distinguish between a funded, approved project with a construction timeline and an announcement without a budget allocation. Only the former should influence your suburb assessment.
Property quality and resale depth
A strong suburb can still contain an unsuitable property. Condition, layout, land component, strata exposure, flood or hazard risk, and the number of comparable sales in the past twelve months all form part of the asset-level assessment. A high yield from a suburb with ten comparable sales per year is a thinner data point than the same yield from a suburb with a hundred comparable sales. Resale depth gives you an exit pathway; without it, a yield-focused purchase can become illiquid.
How should investors balance rental yield and capital growth?
The right balance depends on the investor's cash-flow capacity, time horizon and portfolio role. There is no universally correct answer, and a strategy that fits one investor's circumstances may be unsuitable for another.
For a deeper framework on property investment strategy in Australia, including how income and growth objectives interact across different market cycles, Buyers Agency Australia's blog covers this in detail.
| Strategy focus |
Suits investors who… |
Key trade-offs |
| Income-focused (higher yield) |
Need cash flow now, have borrowing constraints, or prioritise vacancy resilience |
May sacrifice capital growth and resale depth; higher-yield markets can carry more employment or supply risk |
| Growth-focused (lower yield) |
Can fund a cash-flow shortfall, have a long hold horizon, and prioritise equity creation |
Requires serviceability capacity; lower current income, but stronger owner-occupier demand and scarcity tend to support values over time |
| Balanced |
Seeking a property that contributes positively to cash flow while participating in moderate growth |
Requires careful suburb and property selection; neither yield nor growth may be maximised |
When an income-focused strategy may make sense
If serviceability is under pressure and you need properties that contribute positively to your borrowing capacity, a higher-yield asset can reduce the cash-flow drag that makes a second or third purchase difficult. The caution is that the suburbs producing the strongest gross yields sometimes carry the weakest resale depth, the most volatile vacancies, or the highest maintenance profiles. Define your minimum acceptable net yield after all costs before shortlisting markets.
When a growth-focused strategy may make sense
If you have the capacity to fund a moderate cash-flow shortfall over a medium to long hold period, a growth-oriented market may build equity faster than a high-yield location. Owner-occupier demand, land scarcity, and proximity to employment and amenity tend to support values over time. No capital growth outcome is guaranteed, and a property in a growth-focused market can still underperform if the asset is poorly selected or the timing is wrong.
Why do some high-yield suburbs carry more risk?
Yield can be thought of as a compensation signal. When a market produces a higher income return than comparable markets, that premium often reflects something about the risk the buyer is accepting: weaker employment diversity, thinner transaction volumes, older housing stock, higher maintenance demands, or uncertain future supply.

Mining, agriculture and single-industry exposure
Regions with one dominant employer or one commodity cycle can produce high yields during strong periods. When production scales back, the workforce shrinks, vacancy rises and rent falls. The same conditions that made the yield look attractive can make the exit difficult. Any assessment of a single-industry market should include current employment figures, recent vacancy trends, and a realistic picture of the buyer pool if you need to sell.
Oversupply and changing rental demand
A suburb with a high proportion of investor-owned units and a recent wave of new completions can see vacancy rates move sharply in a short period. Changing tenant preferences, such as a shift toward larger dwellings after extended working-from-home adoption, can also reduce demand for certain property types. Checking the ABS building approvals pipeline against current vacancy trends gives a clearer picture of the supply risk.
Thin transaction volumes and resale liquidity
A published yield based on a small number of sales or rental listings is a less reliable data point than one drawn from a deeper transaction set. If a suburb records only a handful of sales per quarter, the median price can shift substantially with one or two outlier transactions, and your ability to exit at a reasonable price is constrained. Require a minimum sample-size disclosure when reviewing third-party suburb data.
How can investors compare Sydney, Melbourne, Brisbane, Adelaide and Perth?
Each capital city has its own vacancy profile, price range, supply pipeline and tenant demand characteristics. Comparing them using a consistent template is more useful than declaring a winner. SQM Research's July 2026 data illustrates why the date and geography of vacancy figures matter: markets like Brisbane, Perth and Adelaide recorded vacancy rates below 1%, while Sydney and Melbourne showed different conditions, reflecting different supply and demand dynamics in each city.
Use a consistent suburb comparison table
The table below is a template. Populate it using current, source-attributed data with consistent property type and reference periods across every row.
| Column |
What to record |
Why it matters |
| Market / suburb |
Name and state |
Ensures geography is consistent |
| Property type |
House, unit, townhouse |
Yield comparisons must use the same type |
| Median sale price |
Dollar figure, source, month |
The price base for yield |
| Median weekly rent |
Dollar figure, source, month |
Achieved rent, not asking rent |
| Gross yield |
% calculated from above |
Screening metric only |
| Vacancy rate |
% with source, month, methodology |
Demand signal |
| Rent trend (12 months) |
Up / stable / down, source |
Durability indicator |
| Supply pipeline |
Approvals in pipeline, source |
Future competition for tenants |
| Tenant drivers |
Employment sectors, amenity, population |
Demand durability |
| Comparable sales depth |
Annual sales volume |
Exit and valuation reliability |
| Risk note |
Single-industry, oversupply, hazard |
What could invalidate the yield |
| Source and checked date |
Named source and month/year |
Reproducibility and freshness |
What are the common mistakes when chasing high rental yields?
Many of the costly errors in yield-focused property investment share the same root: treating a single number, at a single point in time, as a complete answer. For a broader look at these errors in context, see common property investment mistakes that Australian investors make across all strategies.
- Using gross yield as the final return. Gross yield excludes vacancy, management, maintenance, rates and other holding costs. Always model the net position.
- Accepting advertised rent without comparable leases. Asking rent on a listing site can differ from what a property actually achieves. Request recent comparable lease evidence from a local property manager.
- Using stale data. A yield calculated from prices and rents twelve months old may not reflect the current market. Record the date of every figure you use.
- Ignoring vacancy. A property vacant for six weeks per year produces a materially different return than the gross yield implies. Use a realistic vacancy allowance in your calculations.
- Overlooking strata and maintenance. Units with poorly funded capital works or older houses with deferred maintenance can absorb a disproportionate share of rental income. Check strata records and conduct a building inspection.
- Confusing positive gearing with positive cash flow. A positively geared property produces more rental income than its deductible expenses, but it may still produce negative cash flow after non-deductible costs. These are different measures.
- Overestimating tax benefits. The ATO rental income guidance sets out what can be claimed and the conditions that apply. Tax outcomes depend on each investor's personal circumstances. Do not use a projected tax benefit to justify a purchase that does not stack up before tax.
- Buying in a thin market. A high yield that is difficult to sell is not a liquid investment. Assess the buyer pool before you commit.
- Choosing a suburb before defining the strategy. The suburb shortlist should follow the portfolio objective, not precede it.
What should I check before buying in a high-yield suburb?
A structured pre-purchase checklist reduces the chance that a yield that looks attractive on paper becomes a problem after settlement. For a step-by-step buying process, buying an investment property step by step covers the acquisition sequence in detail.

The suburb and property validation checklist
- Define the portfolio objective. Income, equity growth, or a balance? Set a maximum cash-flow shortfall you are comfortable carrying and a minimum holding period.
- Confirm your finance position. Know your borrowing capacity, likely interest rate, and the deposit and acquisition costs required before shortlisting markets. APRA's prudential guidelines shape how lenders assess rental income and expenses.
- Shortlist markets using the comparison template above. Use consistent property type, date and source for every row.
- Validate rent with local evidence. Obtain a current rental appraisal from a local property manager based on comparable leases, not suburb medians.
- Check vacancy and supply. Use the most current vacancy data available with its methodology stated, and review the ABS building approvals pipeline for the local area.
- Inspect the actual property. Condition, layout, flood or hazard exposure, strata records, and maintenance history can all affect net yield and resale value. A building and pest inspection is a standard step.
- Complete financial, legal and contract due diligence. Obtain legal advice on the contract, confirm title, and check for caveats, easements or planning overlays that could affect the property.
- Negotiate within a documented limit. Know the maximum you will pay based on comparable sales, not on the asking price.
- Confirm the settlement pathway. Ensure finance is formally approved, insurance is arranged, and the property management plan is in place before settlement.
After completing each step, make an explicit decision: proceed or stop. A yield that looks attractive is not sufficient reason to skip a step.
If shortlisting, researching, and validating markets is more than you want to manage alongside an existing work and life schedule, book a free strategy session to test your suburb shortlist against your goals and borrowing position before committing to a search.
When does professional property acquisition support add value?
A buyers agent operates on the buyer's side exclusively. Their role is to define the investment brief, research suitable locations, source properties that fit the criteria, conduct due diligence, negotiate and support the buyer through to settlement. That process is distinct from the selling agent's role, which is to achieve the best outcome for the vendor.
How Buyers Agency Australia approaches yield-led property selection
Buyers Agency Australia applies a strategy-first process that connects the investor's goals, borrowing position and risk tolerance to a shortlist of markets and properties before any search begins. Dragan Dimovski, with 20+ years of experience in Australian property investment, leads the advisory team. The brand's approach includes off-market and under-market property access, property-level due diligence, negotiation, and full support from strategy through to settlement.
For investors assessing high rental yield suburbs, the value of this approach lies in connecting the suburb-level data to the actual property, the actual rent achievable, the realistic cost stack, and the portfolio role the acquisition is intended to fill.
When this is not the right fit
Buyers Agency Australia is not the right fit for investors who want a free static suburb list, are not yet finance-ready, have not defined their risk tolerance, or expect a guaranteed yield or capital growth outcome. Property investment carries risk, and no buyers agent can guarantee a specific return, a specific price, or off-market access to a property that exactly matches a brief.
Frequently asked questions about high rental yield suburbs in Australia
What is considered a high rental yield in Australia?
There is no universal threshold because the result depends on property type, location, costs and investor strategy. Gross yield must always be disclosed with a date, property type and source before it is meaningful for comparison purposes.
How do I calculate rental yield on an investment property?
Calculate gross rental yield by dividing annual rent by the purchase price and multiplying by 100. Multiply weekly rent by 52 to annualise it. Deduct property costs to arrive at net yield, and account for your personal tax position separately.
Is a high rental yield better than capital growth?
Neither is automatically better because the right balance depends on cash-flow capacity, risk tolerance and the portfolio's purpose. Income-focused and growth-focused strategies each suit different investor circumstances.
Can a high-yield property still lose money?
Yes. A property can show a high gross yield and still produce negative cash flow after vacancy, interest and ownership costs are deducted. The gross-to-net gap is where most investors encounter surprises.
What vacancy rate is good for an investment property?
A lower vacancy rate indicates stronger rental demand, but the figure must be assessed with its methodology, property type and local supply context. SQM Research reported Brisbane, Perth, Adelaide, Darwin and Hobart all below 1% vacancy in July 2026, compared with higher rates in Sydney and Melbourne.
Are regional suburbs better for rental yield?
Regional suburbs can offer higher yields in some periods, but they may also carry greater employment concentration, thinner resale liquidity, supply volatility and weaker comparable-sales depth. Higher yield in a regional market often reflects these risks being priced in.
What costs reduce rental yield?
Management fees, vacancy allowance, council rates, water rates, landlord insurance, maintenance, strata levies, land tax and loan interest are the main cost categories. The ATO rental income guidance explains which expenses are deductible and the conditions that apply.
Should I compare houses and units using the same yield benchmark?
No. Houses and units should be compared separately because their prices, rents, strata costs, maintenance profiles and tenant demand differ. Mixing them in the same yield table produces misleading comparisons.
How current should rental yield data be?
Use the newest credible data available and record the month, property type, geography, methodology and reference period alongside every figure. In a fast-moving rental market, data that is six months old may not reflect current conditions.
Can Buyers Agency Australia help assess a high-yield suburb?
Buyers Agency Australia can help investors connect suburb research with strategy, property selection, due diligence, negotiation and settlement support, subject to the investor's circumstances and chosen service. Buyers Agency Australia service details are current as of August 2026.
A practical decision framework for your next investment property
A high percentage is a starting point, not a recommendation. Before acting on any yield figure, work through the following five decisions:
- Define the portfolio objective. Does this property need to produce income now, build equity, preserve borrowing capacity, or diversify an existing portfolio?
- Set a maximum cash-flow shortfall and reserve buffer. Know the most you can comfortably carry as a holding cost per month before you shortlist any market.
- Compare suburbs using consistent, dated data. Apply the comparison template above with the same property type, the same source, and the same reference month across every row.
- Validate the actual property. Rent appraisal, condition, strata, hazard exposure, comparable sales, contract and finance all need separate confirmation. Suburb-level data does not substitute for asset-level due diligence.
- Proceed only when suburb and asset fit the portfolio plan. If either element fails the test, stop rather than adjusting the criteria to make the numbers work.
For Buyers Agency Australia investment guidance on how to connect these steps to a real search brief, the team offers a structured process from strategy to settlement. If you are ready to map out your next property move, a free strategy session is the logical starting point before committing to any suburb or property type.
To discuss your specific situation and goals, contact the team about your strategy.
This article is general information only and is not personal financial, tax, legal or lending advice. Obtain advice specific to your circumstances before making an investment decision.
 General
Learn how to compare high rental yield suburbs in Australia using gross and net yield, vacancy, tenant demand,...
Neither commercial nor residential property guarantees better long-term ROI. Commercial property can offer stronger income potential through leases and recoverable outgoings, while residential property often offers broader tenant demand, more standardised finance and easier resale. The better choice depends on your net return, capital growth expectations, vacancy tolerance, borrowing capacity, liquidity and overall portfolio strategy. All comparisons in this article are Australia-specific. Tax, lending and SMSF decisions require qualified advice from the relevant licensed professional.
Imagine you are weighing up a leased industrial unit in a metro fringe precinct against an established house in a high-demand suburb. Both have a plausible case on paper. The commercial asset advertises a 6.5% yield; the house offers 3.5% with a track record of steady capital appreciation. But the headline yield alone does not settle the decision.
Long-term ROI is a composite: income after costs, capital growth, vacancy exposure, finance serviceability, liquidity on exit, and how the asset fits the rest of your portfolio. Strip away the marketing and those factors look very different across asset classes.
That is the core of the Australian property buying approach that Buyers Agency Australia takes with every investor. The asset-class decision comes before the property search, not after it.
Long-term ROI is not an asset-class verdict. It depends on whether the investor buys an asset with durable income, defensible demand and manageable risk that fits the portfolio's next move.
Commercial vs residential property investment: the key differences
Commercial property in Australia covers income-producing, non-residential assets occupied by businesses. Residential property covers houses, units and townhouses held for rental income and long-term capital growth. Both can generate wealth; neither is universally superior.

This article compares both asset classes across eight criteria: net income and yield, capital growth potential, lease and tenant structure, vacancy and reletting risk, finance and equity requirements, tax and ownership complexity, liquidity and resale, and investor and portfolio suitability. This is an educational comparison, not personal financial advice, a forecast or a guarantee.
| Criterion |
Commercial property |
Residential property |
| Gross yield range |
Typically higher, varies by asset, location and lease |
Typically lower; 3%–5% range is commonly cited for Australian capital cities |
| Net yield |
Can be stronger where tenants cover outgoings |
Lower after landlord-paid rates, insurance, maintenance |
| Capital growth |
Driven by lease income and tenant strength |
Driven by demand, land scarcity and owner-occupier competition |
| Lease terms |
Often 3–10 years with rent reviews |
Typically 6–12 months; state tenancy laws apply |
| Tenant pool |
Business tenants; sector and location dependent |
Broad household demand |
| Finance |
Assessed on lease, asset type, borrower strength; higher deposits common |
Standardised residential lending; more lenders compete |
| Vacancy risk |
Reletting can take longer; fit-out costs are material |
Lower typical vacancy in supply-constrained markets |
| Resale liquidity |
Smaller buyer pool; lease expiry affects sale conditions |
Larger buyer pool including owner-occupiers |
What counts as commercial property investment in Australia?
Commercial property spans three primary sectors. Office property includes CBD towers, suburban office parks and strata suites. Retail property covers supermarket-anchored centres, strip shops and neighbourhood retail. Industrial property includes warehouses, logistics facilities, manufacturing premises and last-mile distribution units.
Each sector has its own demand drivers, lease norms and risk profile. Industrial assets, for example, have attracted strong investor interest due to supply chain trends and e-commerce growth, while some office markets have faced structural headwinds from hybrid working patterns. Treating commercial property as one uniform asset class is a common and costly mistake.
In commercial property, the lease, tenant covenant and income profile are central to how the asset is valued. A building with a strong tenant on a long lease is fundamentally different from the same building vacant or leased to a weak covenant tenant on a short term.
What counts as residential property investment?
Residential investment property includes houses, units and townhouses held primarily for rental income and long-term capital growth. Demand is driven by population growth, housing supply, employment hubs and owner-occupier competition, particularly in established urban markets.
Residential property is not automatically the safer or simpler option. A unit with high strata levies, a history of special levies and tight vacancy can underperform a well-located house with lower ongoing costs and stronger resale demand. Asset selection matters as much in residential as it does in commercial.
How do commercial and residential property returns compare over the long term?
Comparisons between commercial and residential investment property returns must distinguish between gross yield, net yield, capital growth and total return. Blurring these metrics leads to poor decisions.
Gross yield is annual rental income divided by purchase price, expressed as a percentage. It ignores every cost of ownership.
Net yield subtracts landlord-paid outgoings, management fees, insurance, rates and vacancy allowance from rental income before dividing by purchase price. Net yield is the number that actually matters for cash flow planning.
Capital growth is the change in asset value over the holding period. It is separate from income and is not guaranteed in either asset class.
Total return combines income and capital growth after costs, finance and tax. It is the most complete measure of investment performance but the hardest to project accurately.
For a deeper breakdown of how advertised yield can mislead, the gross yield versus net return analysis from Buyers Agency Australia is worth reading before comparing any two assets.
Why commercial property can produce stronger rental income
Australian commercial leases typically run 3 to 10 years, with built-in rent reviews often tied to CPI or fixed annual increases. Against residential leases of 6 to 12 months, the contractual income certainty can be materially different.
Many commercial leases are structured as net or semi-net leases, meaning the tenant is responsible for council rates, water, insurance and, in some cases, body corporate levies. This outgoings recovery can significantly improve the landlord's net income position compared to a residential investment where all outgoings fall on the owner.
That said, higher advertised commercial yield often reflects higher risk. A practical commercial property investment guide can help investors understand what drives those yield differences before committing capital.
Why residential property may offer broader growth and resale demand
Residential property benefits from a deep and liquid market. Owner-occupiers compete alongside investors, which supports prices even in softening conditions. In supply-constrained capital city markets, tight vacancy has historically supported both rental growth and asset value appreciation.
CBRE projects apartment vacancy to fall from 1.8% in 2025 to 1.1% by 2030, reflecting structural housing undersupply that continues to support residential rental demand. This depth of demand is not automatically replicated in commercial markets, where sector, location and lease terms drive value more directly than population trends.
Residential capital growth is not uniform. Markets, asset types, locations and property quality all produce different outcomes. Claiming that residential always delivers stronger capital growth than commercial is not supported by evidence across all periods, sectors and locations.
Why net return matters more than advertised yield
Consider two illustrative examples using clearly labelled assumptions:

Illustrative Example A (Commercial): A $1.5 million suburban industrial unit generates $105,000 gross rent per annum (7% gross yield). The tenant covers outgoings under a net lease. After management fees and a conservative 8% vacancy allowance, net income is approximately $88,000, giving a net yield of around 5.9%.
Illustrative Example B (Residential): A $900,000 house generates $36,000 gross rent per annum (4% gross yield). After rates, insurance, property management and maintenance, net income drops to approximately $25,200, giving a net yield of around 2.8%.
These are hypothetical examples using assumed inputs only. Actual outcomes will vary by asset, location, lease, tenant, finance and market conditions. The point is that the gap between gross and net return can be substantial in both directions, and the asset with the higher headline yield is not always the stronger net income performer.
Which is better for long-term ROI in Australia, commercial or residential property?
The honest answer is conditional. Neither asset class is universally superior. The better option depends on the investor's required return, risk budget, borrowing capacity, time horizon and portfolio structure.
Commercial property may suit investors who prioritise income, can tolerate longer vacancy periods and leasing complexity, and have the equity and borrowing capacity to meet commercial lending requirements. Residential property may suit investors who prioritise broader demand, more standardised finance, or resale flexibility, particularly those building a portfolio over time.
A blended portfolio combining both asset classes is an option for some investors, but it is not automatically better than holding quality assets in one class. Diversification only adds value when each asset is selected on its own merits.
| Investor objective |
Lean toward commercial |
Lean toward residential |
| Maximise net income |
Where lease, tenant and outgoings support it |
Less common at current yield levels |
| Capital growth priority |
Depends on lease and sector demand |
Stronger owner-occupier competition supports prices |
| Finance simplicity |
More complex; lender-specific assessment |
More standardised; more lenders compete |
| Exit flexibility |
Smaller buyer pool; lease affects salability |
Larger buyer pool; owner-occupiers expand the market |
Commercial property advantages and risks investors need to price in
Commercial property offers genuine advantages for the right investor with the right asset. It also carries risks that are often underestimated until they materialise.
| Advantage |
Offsetting risk |
| Longer lease terms provide contractual income certainty |
Lease expiry can trigger extended vacancy and reletting costs |
| Tenant may cover outgoings under net lease |
Outgoings recovery depends on lease structure; not universal |
| Defined rent reviews built into lease |
Incentives and market conditions affect effective rent at renewal |
| Higher gross yield potential |
Higher yield often reflects higher vacancy or covenant risk |
| Tenant fit-out reduces landlord capital spend |
Make-good obligations and fit-out costs apply at lease expiry |
| Sector diversification (office, retail, industrial) |
Each sector has distinct demand drivers and due diligence requirements |
For investors seeking commercial property buyer-side support in assessing these trade-offs, a strategy-first approach to due diligence makes a material difference to outcomes.
How leases, tenant covenant and outgoings affect commercial returns
A commercial lease is the primary document driving asset value and income. Passing rent, rent review mechanisms, outgoings obligations, lease options, bank guarantees, permitted use clauses and make-good provisions all affect what the investment actually returns.
Tenant covenant quality matters as much as lease term. A long lease to a weak covenant tenant is not the same as a shorter lease to a financially strong business with demonstrable trading history. Assessing covenant strength requires financial analysis of the tenant, not just a reading of the lease.
Bank guarantees and personal guarantees can partially mitigate tenant default risk, but they do not eliminate it. Any commercial investment should be reviewed by a solicitor and assessed by a qualified accountant before proceeding. See the practical commercial property investment guide for a more detailed due diligence framework.
Why commercial vacancy can have a larger financial impact
When a residential tenant vacates, reletting typically takes weeks and costs are limited to advertising, cleaning and a short vacancy period. When a commercial tenant vacates, reletting can take months or longer depending on asset type, location and market conditions.
Reletting a commercial property often requires lease incentives such as rent-free periods, fitout contributions or reduced rent for an initial term. These incentives reduce effective net income for the period they apply. In a weak leasing market, an investor who is also servicing debt on the asset can face simultaneous vacancy, capital expenditure and refinancing pressure. This interaction between vacancy and finance is a risk that many generic comparisons understate.
The due diligence process for any commercial acquisition must include a scenario that models what happens if the asset is vacant for six to twelve months immediately after purchase.
Residential property advantages and risks investors need to understand
Residential investment property is broadly accessible, well understood by lenders and supported by deep tenant and buyer demand across Australian capital cities. Those are genuine structural advantages, but they do not make residential property risk-free.
| Advantage |
Offsetting risk |
| Broad tenant pool supports low vacancy |
Residential vacancy can still occur, particularly in oversupplied segments |
| Standardised lending; more lenders compete |
LVR, serviceability and policy changes affect access over time |
| Owner-occupier demand supports resale |
High prices compress yields and increase reliance on capital growth |
| Lower entry costs in some markets |
Rising prices in sought-after markets increase capital requirement |
| Simpler property management |
Landlord obligations under state tenancy laws are significant |
When residential property may suit a growth-focused strategy
Established locations with strong owner-occupier competition, constrained supply and employment anchors have historically supported capital growth. For investors building a portfolio over the medium to long term, residential property in these markets offers a combination of broad demand depth and resale optionality that commercial assets in secondary locations cannot match.
For investors focused on positive cash flow property strategy, residential property in certain markets can also deliver adequate income alongside growth potential, particularly where yields have improved relative to acquisition prices.
Portfolio scalability is another consideration. Residential assets are generally more divisible and easier to finance sequentially. An investor building from one property to several can typically move through lender assessment processes more predictably in residential than in commercial.
Where residential investment can disappoint
Gross residential yields in major capital cities sit in the 3%–5% range for many asset types, and net yields are lower still after rates, insurance, property management, maintenance and strata levies. In high-value markets, investors are effectively relying on capital growth to justify the investment, which increases the risk exposure to market cycles.
Strata-titled properties carry additional complexity. Body corporate levies, special levies, sinking fund adequacy and strata committee decisions all affect the cost of holding the asset. These are not risks that disappear because the property is residential.
The gross yield versus net return analysis covers this gap in detail and is worth reviewing before purchasing any residential investment property based on advertised rent.
Financing, tax and ownership considerations in Australia
This section is general information only. It does not replace personal financial, tax, legal, lending or SMSF advice. Investors should obtain qualified advice from licensed professionals before making any financial or property decision.
Finance, tax and ownership structures for commercial and residential investment are governed by different rules, assessed by lenders on different criteria, and carry distinct compliance obligations. The section below identifies the key differences and the professional checks each requires.
| Issue |
What may differ |
Professional check required |
| Deposits and LVRs |
Commercial lending often requires larger deposits; LVRs vary by lender, asset type and lease |
Finance broker or commercial lender |
| Serviceability |
Commercial income from a lease is assessed differently to residential rental income |
Lender or mortgage broker |
| GST |
Commercial property transactions may involve GST depending on use and registration |
Accountant and ATO guidance |
| Land tax |
Rates, thresholds and exemptions vary by state and ownership structure |
State revenue authority and tax adviser |
| Depreciation |
Both asset classes allow depreciation claims; commercial may offer additional allowances |
Quantity surveyor and accountant |
| CGT |
Both classes are subject to CGT; concessions depend on holding period, structure and use |
Accountant and tax adviser |
| Negative gearing |
Available for both classes subject to ATO rules; policy debate has not eliminated it for residential |
ATO and tax adviser |
Commercial and residential finance are assessed differently
Commercial lending is more lender-specific than residential lending. There is no universal commercial deposit percentage that applies across all lenders, asset types and lease situations. APRA has clarified that commercial property lending requires lenders to apply risk-sensitive, asset-specific assessment. Investors should speak with a commercial finance broker rather than applying residential lending assumptions to a commercial purchase.
Residential investment lending is more standardised but still subject to serviceability buffers, income verification and LVR requirements that shift with interest rate cycles and regulatory settings.
GST, land tax, depreciation and capital gains tax
Commercial property transactions may be subject to GST depending on whether the property is used for business purposes and whether the seller is registered. The ATO's guidance on GST and property should be reviewed with an accountant before any commercial purchase.
Land tax thresholds, rates and ownership-structure rules vary by state and territory. Tax outcomes depend on the asset, the ownership entity and the investor's specific circumstances. Always obtain advice from a registered tax agent or accountant.
Can an SMSF invest in residential or commercial property?
An SMSF can invest in both residential and commercial property, but the rules differ significantly and the compliance obligations are material. According to Moneysmart, Australian Government, SMSF property investment involves costs, liquidity risks and borrowing restrictions that trustees must understand before proceeding.
Key SMSF rules include: the sole purpose test (the fund must exist solely to provide retirement benefits), the related-party rule (residential property cannot be leased to related parties), and the business real property exception (a commercial property can be leased to a related party if it is used wholly and exclusively in a business at arm's length commercial terms).
Borrowing within an SMSF requires a Limited Recourse Borrowing Arrangement (LRBA), a regulated structure with lender-specific criteria and strict documentation requirements. ASIC notes that recommending the use of an SMSF to invest in real property can constitute financial product advice requiring appropriate AFS licensing. All SMSF investment decisions should involve a licensed financial adviser, SMSF specialist and solicitor.
Which property type suits different Australian investor profiles?
Matching the asset class to the investor's objectives and constraints is more useful than declaring one class universally better. The matrix below is a starting guide, not personal advice.
| Investor profile |
Considerations |
Direction |
| First-time investor |
Simpler finance, broader resale demand, lower entry in some markets |
Residential may reduce complexity; still requires careful asset selection |
| Business owner |
May investigate business real property through SMSF or direct ownership to stabilise occupancy costs |
Commercial may be relevant with specialist legal, tax and finance advice |
| SMSF trustee |
Sole purpose test, related-party rules, LRBA restrictions and liquidity requirements apply |
Both classes available; requires licensed financial, SMSF and legal input |
| Income-focused investor |
Net yield, lease structure, outgoings and vacancy exposure all matter |
Commercial where lease supports income; residential in high-yield markets |
| Portfolio builder |
Consider sector, tenant, geography and lease-expiry concentration before adding any asset |
Diversification between classes can add resilience; not automatically better |
| Growth-focused investor |
Owner-occupier demand, land scarcity and supply constraints drive residential growth |
Residential in established, high-demand locations; supported by manufactured growth in property portfolios strategies |
If you are working through this decision and want to model it against your specific situation, book a free strategy session with the Buyers Agency Australia team before committing capital.
What should you compare before choosing commercial or residential property?
The asset-class decision is the start of a process, not the end of it. Before selecting a property in either class, investors need to work through a structured framework that covers strategy, capital, income evidence, risk and exit.
A practical eight-step property investment comparison checklist
- Define your investment objective. Are you prioritising income, growth, tax efficiency, portfolio diversification or capital preservation? The answer shapes every subsequent decision.
- Confirm your borrowing capacity. Speak with a commercial or residential finance broker early. Do not select an asset class based on yield before understanding what a lender will fund and on what terms.
- Set a realistic cash buffer. Model what happens if the asset is vacant for three to six months and interest costs continue. Your buffer needs to absorb that scenario without forcing a distressed sale.
- Define asset quality criteria. For commercial: lease term remaining, tenant covenant strength, outgoings structure, building condition, permitted use and zoning. For residential: location quality, asset condition, strata health and comparable rental evidence.
- Verify income evidence. For commercial, obtain the executed lease, rent ledger, outgoings schedule and any incentives offered. For residential, obtain comparable rental evidence from a licensed property manager, not from the selling agent.
- Stress-test vacancy and rate scenarios. Run the numbers if the tenant leaves or interest rates move. If the asset cannot survive a realistic negative scenario, reconsider.
- Conduct legal and physical due diligence. Engage a solicitor for lease, title and contract review. Commission a building and pest report. Confirm zoning, planning controls and any encumbrances. Do not rely on vendor representations.
- Plan the exit before you buy. Who will buy this asset in five, ten or fifteen years? A commercial property with a short lease expiry or a residential unit in an oversupplied market both carry exit risk that is visible before purchase.

How Buyers Agency Australia can support the decision
Buyers Agency Australia operates as a strategy-first buyer-side advisory service across commercial and residential investment property. The process begins with defining the investment brief: income targets, capital constraints, risk tolerance, time horizon and portfolio fit. Only then does property sourcing begin.
For commercial acquisitions across office, retail and industrial assets, commercial acquisition strategy and negotiation forms the core of the service. This includes off-market sourcing, lease and covenant analysis, due diligence coordination and purchase negotiation. For residential investment, the same strategy-first methodology applies.
Dragan Dimovski, the principal behind Buyers Agency Australia, brings over 20 years of experience across both commercial and residential property markets. That depth of judgment is relevant when the asset-class decision itself carries material financial consequences.
Buyers Agency Australia service details checked August 2026.
This article is educational. Buyers Agency Australia provides buyer-side property advisory services and does not replace legal, tax, lending, valuation or financial advice.
When buyer-side property support is not the right fit
Buyer-side support from Buyers Agency Australia does not replace a solicitor, registered valuer, accountant, tax adviser, finance broker or licensed financial adviser. Investors who need personal SMSF advice, legal advice on a specific contract, a formal valuation, tax structuring advice or formal finance approval must obtain those services from the relevant qualified professional.
The service also does not guarantee a particular purchase price, rental return, capital growth outcome or vacancy rate. Property investment carries risk, and no buyer-side service eliminates it.
Commercial vs residential property investment FAQs
1. Is commercial property better than residential property for long-term ROI?
Neither is universally better. Commercial may offer stronger net income; residential may offer broader demand and simpler finance. The better option depends on the investor's objectives, capital and risk tolerance.
2. Which property type usually has the higher rental yield?
Commercial property typically advertises higher gross yields than residential, reflecting higher vacancy and leasing risk. Net yields depend on outgoings structure, lease and vacancy allowance and cannot be compared on headline figures alone.
3. Is residential property safer than commercial property?
Residential has a broader tenant pool and more standardised finance, but it is not risk-free. Commercial carries different risks around vacancy, lease complexity and tenant concentration. Neither class is categorically safer; risk depends on the specific asset.
4. Is commercial property harder to finance?
Generally, yes. Commercial lending is more lender-specific and typically requires larger deposits, with serviceability assessed on the lease and asset type. Speak with a commercial finance broker rather than applying residential lending assumptions.
5. How much deposit do you need for commercial property?
There is no universal figure. Commercial deposits vary by lender, asset type, lease, tenant covenant and borrower strength. APRA does not set a fixed consumer deposit rate for commercial lending. Obtain current lender quotes before budgeting.
6. How do commercial leases affect investment returns?
Commercial leases determine passing rent, outgoings obligations, rent review frequency, options and make-good requirements. A strong lease with a financially sound tenant can support both income and asset value. A weak lease expiring soon reduces both.
7. Can an SMSF buy commercial or residential property?
Yes, but strict rules apply. The sole purpose test, related-party restrictions, LRBA requirements and liquidity obligations all apply. Business real property can be leased to a related party at arm's length. Personal SMSF advice requires a licensed financial adviser. Refer to Moneysmart and the ATO for general guidance.
8. Should a first-time investor start with residential property?
Residential lending is generally more accessible and the resale market is broader, but there is no universal starting point. Asset selection quality, location, borrowing capacity and strategy matter more than the asset class label.
9. Can investors combine commercial and residential property?
Yes. A blended portfolio can add diversification across income sources, tenant types and market cycles. Each asset must still be selected on its own merits, and the combination should not increase sector or lease-expiry concentration unnecessarily.
10. What matters more than a high advertised yield?
Net yield after all costs, lease quality and remaining term, tenant covenant strength, vacancy risk, finance serviceability, exit liquidity and how the asset fits the investor's broader portfolio strategy all matter more than the headline gross yield figure.
The practical long-term ROI decision
The right asset class is the one whose income, costs, growth drivers, risk profile and exit path fit the investor's strategy, not the one with the highest advertised return. Before committing to either commercial or residential property, validate finance, tax structure, legal obligations, lease terms and building condition with qualified professionals.

If you are ready to define your brief and compare your options with a strategy-led approach, map out your next property move with the Buyers Agency Australia team. For a direct conversation about a specific acquisition or portfolio decision, contact the Buyers Agency Australia team to get started.
 General
Compare commercial and residential property investment in Australia across ROI, yield, risk, finance, leases, tax and investor suitability.
A buyers agent in Inner West Sydney represents you, the buyer, through every stage of the property purchase process. They help define your brief, assess suburbs and property types, coordinate due diligence, negotiate with the selling agent, and support the transaction through to settlement.
For an investor, the useful question is not simply whether a property looks attractive. It is whether the asset fits the purchase strategy, budget, risk limits, cash flow needs and longer-term portfolio plan. For a home buyer, it is whether the decision will hold up after the auction pressure fades.
Buying in Sydney's Inner West can feel relentless. You may be inspecting apartments after work, trying to decode auction guides, piecing together comparable sales from limited public data, or attempting to buy from interstate without the ability to walk every street.
Inner West buying involves more than naming a suburb. Property type, condition, strata obligations, zoning, transport access, price evidence and your intended use can all reshape the decision. That is why a disciplined, evidence-led approach matters before any offer is made.
Buyers Agency Australia takes a strategy-led, buyer-side approach to property search, assessment, negotiation and settlement support. This guide explains how the process works, what buyers should assess, and how to decide whether professional representation is right for your brief.
What does an Inner West Sydney buyers agent do?
A buyers agent, sometimes called a buyers advocate, is appointed by and works exclusively for the purchaser. Their role is to represent your interests, not the vendor's, throughout the buying process. To understand what a buyers agent does in practice, it helps to separate their role from the selling agent's role.
How buyer-side representation differs from working with the selling agent
The selling agent is engaged by and legally obligated to the vendor. According to NSW Government guidance on using a real estate agent to buy property, a selling agent cannot act in the buyer's interests without a conflict. A buyers agent, by contrast, is appointed under a separate buyers agency agreement and owes their duty to you.

This distinction matters in a competitive market. When you negotiate directly with a selling agent, you are negotiating with someone whose fee depends on completing the vendor's sale at the highest possible price.
What support may be included in a buyers agency service
A buyers agency service typically covers some or all of the following, depending on the scope agreed in writing:
- Buyer brief, strategy and finance-readiness check
- Suburb selection and property type assessment
- Property sourcing across advertised and private channels
- Physical inspections and shortlist assessment
- Comparable sales and price analysis
- Due diligence coordination, including referrals to solicitors, conveyancers, building inspectors and strata specialists
- Negotiation on price and terms via private treaty or auction bidding
- Settlement liaison and handover coordination
The buyers agent does not replace your solicitor or conveyancer for legal and contract advice, your mortgage broker for finance, or your building inspector and strata specialist for technical reports. Each of those professionals provides services that require their own qualifications and licences.
Why buyers choose a buyers agent for Inner West Sydney property
Sydney's Inner West is a competitive, fast-moving market. Listings can attract multiple registered bidders at auction, while private treaty properties can move from first inspection to exchange within days. For buyers who are time-poor, unfamiliar with local pricing, or emotionally invested in specific streets or suburbs, that pace creates real risk.
When local representation can reduce buying friction
Common friction points that buyer-side representation can help address include:
- Time pressure: Attending multiple inspections per week while managing work and family obligations
- Agent communication: Maintaining consistent contact with selling agents across several listings simultaneously
- Pricing uncertainty: Interpreting auction guides, comparable sales and property condition without a reference framework
- Emotional pressure: Making clear-headed decisions at auction or during fast-moving private treaty negotiations
- Interstate buying: Assessing streets, building condition and suburb character without regular physical access
Representation does not guarantee a specific outcome or price. What it can provide is structured evidence review and clearer decision gates before any offer is made.
How the service differs for home buyers and investors
For owner-occupiers, the brief tends to centre on location, lifestyle fit, school catchments, property character and long-term liveability.
For investors, the filters shift toward rental demand, holding costs, asset quality, strata risk, land value, portfolio concentration and the relationship between the purchase and a broader property investment strategy. The assessment questions are different, and so is the tolerance for certain risks.
Which Inner West Sydney suburbs and property types should buyers consider?
Buyers searching Sydney's Inner West encounter a boundary issue that affects suburb comparisons. "Inner West" as a market description and "Inner West Council" as a local government area are not identical, and confusing them can lead to inaccurate assumptions about governance, planning rules and services.

According to Inner West Council, the council area covers approximately 186,000 residents across suburbs including Annandale, Balmain, Balmain East, Birchgrove, Dulwich Hill, Enmore, Haberfield, Leichhardt, Lewisham, Lilyfield, Marrickville, Petersham, Rozelle, Stanmore, St Peters, Summer Hill, Sydenham, Tempe and parts of Ashbury, Camperdown, Croydon, Croydon Park, Hurlstone Park and Newtown.
For the Inner West buyers agent service offered by Buyers Agency Australia, buyers should confirm the specific suburbs covered in their brief at the point of engagement.
Core Inner West Council markets
Several suburbs within the Inner West Council area are consistently relevant to buyer searches:
- Balmain and Balmain East: Heritage workers cottages, terraces and apartment conversions on a peninsula with harbour access. Questions worth investigating include heritage overlays, flood-free street positioning, strata levy levels and parking availability.
- Leichhardt: Federation and inter-war housing with proximity to the Italian Forum precinct and Parramatta Road. Buyers should assess traffic noise exposure and any commercial zoning near residential streets.
- Marrickville: A diverse mix of terraces, semi-detached homes and purpose-built apartments with ongoing urban renewal. Industrial pockets and proximity to Sydney Airport flight paths are worth checking for individual sites.
- Newtown: High-density terrace and apartment market with strong pedestrian amenity. Strata quality, shared wall conditions and proximity to King Street commercial activity vary significantly by street.
- Annandale: Larger Victorian and Federation homes on wider lots with strong owner-occupier appeal. Buyers should assess flood risk near Johnston's Creek and proximity to Parramatta Road.
These are examples of buyer questions to investigate, not suburb rankings or recommendations. Each street and property requires its own evidence review.
Broader Inner West markets including Five Dock and Concord
Five Dock and Concord are suburbs within the City of Canada Bay Council, not Inner West Council, even though they are widely discussed as part of Sydney's broader inner-west property market.
This council boundary distinction affects planning rules, rates, development applications and local services. Buyers considering Five Dock or Concord should check the applicable local environmental plan and development controls through the City of Canada Bay, not Inner West Council, before drawing conclusions about planning flexibility or development risk.
Houses, terraces, apartments and investment properties
| Property type |
Typical buyer |
Key questions to assess |
| Freestanding house |
Owner-occupier or land investor |
Land area, zoning, boundary setbacks, heritage overlay |
| Terrace or semi-detached |
Owner-occupier or residential investor |
Shared walls, party wall condition, title type, strata or Torrens |
| Apartment or strata unit |
Investor or first buyer |
Strata levies, special levies, sinking fund, by-laws, defect history |
| Mixed-use or commercial |
SMSF or commercial investor |
Lease terms, tenant quality, outgoings, zoning, yield analysis |
What investors should check beyond suburb appeal
Suburb appeal does not equal investment suitability. Before committing to a property, investors should assess realistic rent against holding costs (mortgage, rates, strata levies, management fees, insurance and maintenance), vacancy risk based on tenant demand in that specific street and building, land value relative to total purchase price, and how the asset fits within their existing portfolio.
Building a sound property investment strategy before searching prevents the common mistake of selecting a property that looks good but conflicts with cash flow, tax position or long-term portfolio goals.
When office, retail or industrial property requires a different assessment
For SMSF trustees or sophisticated investors considering commercial property in or near Sydney's inner west, the assessment framework differs substantially from residential buying. Lease terms, tenant quality and covenant strength, outgoings allocation between landlord and tenant, vacancy risk during lease expiry periods, zoning and permitted use, building condition and capital works requirements, and gross versus net yield analysis all require specialist assessment. For buyers pursuing office, retail or industrial assets, commercial property buying support requires a different brief, different due diligence and different professional referrals.
How does the Inner West buyers agent process work?
A structured buying process reduces the risk of emotional decisions and helps buyers avoid committing to properties that do not meet their brief. The typical process runs through six stages.
1. Buyer brief, finance position and purchase strategy
Before any search begins, the buyers agent needs to understand the buyer's confirmed budget and finance status, purchase timeframe, intended use (owner-occupier, residential investment or commercial acquisition), location preferences, property type, must-haves, deal-breakers and risk tolerance. Without a clear brief, the search has no filter.
2. Search across advertised, pre-market and off-market opportunities
The search phase combines public listings with the buyers agent's relationships with local selling agents and any private sourcing channels available to them. Buyers should understand that off-market access depends on the agent's existing relationships and that no specific level of private access can be guaranteed in any engagement. To understand how off-market property searches work in practice, the scope should be discussed and documented in the engagement agreement.
3. Inspections, shortlist assessment and due diligence coordination
The buyers agent attends inspections, reviews comparable sales, assesses property condition and street context, and coordinates the professional reports the buyer needs before exchange. This includes referrals to a qualified solicitor or conveyancer for contract review, a licensed building and pest inspector, a strata specialist if the property is in a strata scheme, and any other qualified professional relevant to the asset. According to NSW Government strata guidance, buyers should review strata records, by-laws, levies, special levies and defect history before exchange.
4. Negotiation, private treaty or auction bidding
The buyers agent prepares a price position based on comparable sales and property assessment, then negotiates via private treaty or represents the buyer at auction. In NSW, a successful auction bid creates a binding contract with no cooling-off period, as confirmed by NSW Government auction guidance. Buyers should ensure finance is unconditional, building and pest reports are complete, and the contract has been reviewed by a qualified legal professional before auction day.
5. Contract exchange, settlement and handover
After exchange, the buyers agent can coordinate with the buyer's solicitor or conveyancer, financial institution, property manager and other parties to support a smooth settlement. They do not replace legal, lending or valuation advice, and buyers should maintain direct communication with their own solicitor throughout the settlement period.
How should a buyers agent assess an Inner West property?
A property that looks right in a suburb can still be a poor purchase at a specific price, in a specific condition, on a specific title. Assessment should work through a structured framework before any offer is made.

Location fundamentals and property-specific context
Location assessment should cover street character and noise sources, proximity to train lines, light rail, buses and arterial roads, flood and stormwater risk for that specific lot, flight path exposure where relevant (particularly for Marrickville and surrounding suburbs), future planning controls or rezoning proposals, and the relationship between the property's position and its intended use.
Comparable sales and price positioning
Comparable sales analysis looks at recent transactions for similar property type, land or internal area, aspect, improvements, parking, sale method and condition. Every property comparison is illustrative until validated against actual sales data for that specific street, building and period. A buyers agent should be able to show you the evidence behind any price position, not simply assert a value.
Building, pest, strata, title and contract risks
For any Inner West property, buyers should obtain a licensed building and pest inspection and, for strata properties, a comprehensive strata report covering levies, sinking fund balance, outstanding special levies, by-laws, defect notices and any known building defects. Title searches and contract review by a qualified NSW solicitor or conveyancer are not optional. Buyers can verify that an agent or conveyancer holds a current NSW licence through the Verify NSW licence-check tool before engaging them.

Rental, holding-cost and portfolio considerations
For investors, the assessment must include a realistic rent estimate (not an optimistic one), vacancy assumptions based on tenant demand in that building and street, management fees, strata levies, rates, insurance, maintenance provisions and financing costs. The asset should be assessed against the buyer's overall portfolio concentration and long-term financial plan. This article does not constitute financial advice; buyers should obtain independent financial and tax advice relevant to their circumstances.
What a buyers agent does not replace
A buyers agent is not a substitute for a solicitor or conveyancer (legal and contract advice), a mortgage broker (lending and finance structuring), a licensed building and pest inspector (structural and pest assessment), a strata specialist (owners corporation records and risk assessment), a registered valuer (formal market valuation), or a financial adviser (investment, tax and SMSF compliance guidance). Each of these professionals provides advice within a regulated scope that requires their own licence or registration.
Are off-market properties better than advertised listings?
Off-market and pre-market are distribution terms, not quality ratings. Understanding the difference helps buyers set realistic expectations before searching.
Off-market versus pre-market property
| Term |
What it means |
| Off-market |
A property being sold without public advertising. The vendor has chosen not to list on real estate portals. |
| Pre-market |
A property that is being prepared for listing but has not yet been publicly advertised. The selling agent may share it with select buyers or buyers agents ahead of launch. |
What access can and cannot mean for buyers
Access to off-market or pre-market property may create an earlier conversation or a wider search field. It does not guarantee a lower price, a better-condition property, an exclusive opportunity, or a successful purchase. The vendor sets the price, and due diligence requirements are identical to those for any advertised property.
Understanding how off-market property searches work is useful context before assuming private access equals better value.
How much does a buyers agent cost in Sydney's Inner West?
Buyers agent fees in Sydney are not set by law and vary based on the service scope, agreement structure and individual engagement. According to NSW Government guidance, fees may be structured as a fixed amount or as a percentage of the purchase price, and must be disclosed in a written agency agreement before any search begins.
No current official fee schedule has been verified for Buyers Agency Australia at the time of drafting. Buyers should confirm the current fee structure, GST treatment, payment timing and all inclusions directly with the agency before signing an agreement. For general context on how Sydney buyers agent fees explained vary by scope and market, the brand's fees blog provides a useful starting framework.
Fee structures and service scope to understand
Before signing a buyers agency agreement, confirm the following:
- Is the fee fixed or a percentage of the purchase price?
- Does the fee include GST?
- What is the payment trigger (exchange, settlement or another milestone)?
- Is the full search included, or is this a negotiation-only or auction-only engagement?
- Are third-party report costs (building, pest, strata) included or additional?
- What happens if no suitable property is found within the agreed period?
- Are there any referral fees, commissions or other income received from third parties?
- What are the termination rights and notice requirements for both parties?
What to check in a NSW buyers agency agreement
Under NSW Government guidance, a buyers agency agreement must set out the services to be provided, the fee and when it becomes payable, the term and termination provisions, any conflicts of interest, and the authority given to the agent to act on your behalf. Read the agreement carefully and obtain independent legal advice if any term is unclear before signing.

Questions to ask before engaging an Inner West buyers agent
Asking the right questions before signing an agreement protects the buyer and helps identify whether the agent's scope, experience and process suit the specific brief.
| Question |
Why it matters |
| Do you hold a current NSW real estate agent licence? |
Licensing is a legal requirement. Verify the licence through Verify NSW before engaging. |
| Do you act exclusively for buyers, or do you also sell property? |
Dual agency creates a conflict of interest that must be disclosed and managed. |
| What is your specific experience in Inner West Sydney? |
General Sydney experience is different from active knowledge of Inner West Council suburbs and City of Canada Bay markets. |
| What does your service scope include, and what is excluded? |
Confirm whether inspections, due diligence coordination, auction bidding and settlement support are all included. |
| How do you handle a property you assess as unsuitable? |
A genuine buyers agent should document the reasons for passing on a property, not just present options. |
| Who pays for building, pest and strata reports? |
Confirm cost responsibility before instructing reports. |
| Do you receive any referral fees or commissions from third parties? |
NSW legislation requires disclosure of any referral payments. |
| How do you communicate and how often will I receive updates? |
Agree on the reporting cadence, format and response time expectations before starting. |
| What are the termination terms if the engagement is not working? |
Understand the notice period, any fees payable on termination and what happens to incomplete due diligence. |
Is an Inner West Sydney buyers agent right for you?
Professional buyer representation suits some buyers and situations well. It does not suit all buyers or all briefs.

A buyers agent may suit buyers who
- Are too time-constrained to attend multiple inspections each week
- Are buying from interstate or overseas without consistent local access
- Want structured, evidence-based property assessment before any offer
- Are auction-averse or unfamiliar with competitive bidding in a NSW context
- Are building a residential investment portfolio and want each asset connected to a broader strategy
- Are considering a commercial property acquisition (office, retail or industrial) that requires a different assessment framework
- Have a complex brief involving strata, heritage, zoning or off-market requirements
A buyers agent may not be the right fit when
- You want to manage your own search, inspections and negotiation from start to finish
- You have not yet confirmed finance or defined a clear purchase brief
- The service fee is not proportionate to your budget or the value of the transaction
- You are at an early exploration stage and are not yet ready to commit to buying
Buyers who are not finance-ready should resolve their lending position before engaging a buyers agent. Most agencies require a confirmed budget before beginning an active search.
How Buyers Agency Australia supports Inner West Sydney buyers
Work with Buyers Agency Australia and you engage a buyer-side advisory service that connects your property brief to a structured search, evidence-based assessment, negotiation and settlement support. Dragan Dimovski, a property expert with 20+ years of experience, leads the approach at Buyers Agency Australia with a focus on strategy, data-informed selection and end-to-end buyer support.
This article describes Buyers Agency Australia's own buyer-side service and is not an independent ranking or comparison.
Strategy-led support from property brief to settlement
The brand's approach centres on aligning the buyer's goals, asset type, risk limits and portfolio plan before identifying properties to assess. That means the brief comes first, the suburb and property type follow, and the evidence chain from comparable sales through to due diligence reports sits between assessment and any offer. The aim is to avoid a situation where a buyer commits to a property that looks right but conflicts with their financial position, risk profile or long-term strategy.
Residential and commercial buying support
For residential buyers and investors, the focus is on securing the right asset at a supportable price with appropriate due diligence. For buyers considering commercial property, the assessment shifts to lease and tenant analysis, outgoings, yield, vacancy risk and zoning. For that scope, the brand's commercial property acquisition service is the relevant starting point.
Book a strategy conversation
If your brief is forming and you want to understand how buyer-side support could work for your Inner West search, book a free strategy session to discuss your goals, budget and property type with the team.
Frequently asked questions about Inner West Sydney buyers agents
What is a buyers agent in Inner West Sydney?
A buyers agent in Inner West Sydney is a licensed property professional appointed by and working exclusively for the buyer. They manage property search, assessment, negotiation and settlement coordination on the buyer's behalf.
What suburbs can an Inner West Sydney buyers agent help me buy in?
Suburbs commonly covered include Balmain, Leichhardt, Marrickville, Newtown and Annandale within Inner West Council, and Five Dock and Concord within the City of Canada Bay. Confirm specific service coverage with the agency before signing an agreement.
Can a buyers agent help me find an off-market property?
Yes, where the agent has relevant selling-agent relationships or private sourcing channels. Access depends on existing relationships and is not guaranteed to produce a lower price or exclusive opportunity.
How much do buyers agents charge in Sydney?
Fees vary by service scope and are set out in the written agency agreement. They are not regulated to a fixed rate. Confirm the structure, GST treatment and payment trigger directly with the agent before engaging.
Do I still need a solicitor or conveyancer?
Yes. A buyers agent does not provide legal or contract advice. Independent legal review of the contract of sale by a qualified NSW solicitor or conveyancer is required before exchange.
Can a buyers agent bid at auction for me?
Auction representation may be included in the full-search service or available as a standalone engagement, subject to the written agreement and the buyer granting clear bidding authority. Confirm this scope before auction day.
What should I ask before hiring a buyers agent?
Confirm their NSW licence, whether they act exclusively for buyers, their specific Inner West experience, exact service scope, fee structure, third-party report costs, referral disclosures, communication cadence and termination terms.
Is a buyers agent useful for an investment property?
It can be, particularly where asset selection needs to be connected to cash flow, risk tolerance, holding costs and portfolio strategy rather than suburb appeal alone. The service is most useful when the buyer has a defined brief and confirmed finance.
Does Buyers Agency Australia work with interstate buyers?
Buyers Agency Australia presents a national service footprint. Interstate buyers considering Inner West Sydney property should confirm the specific service coverage and process for remote buyers at the strategy conversation stage.
Next steps for buying property in Sydney's Inner West
Before engaging any buyers agent for Inner West Sydney property, work through the following checklist:
- Confirm your finance position. Have formal pre-approval or conditional approval before beginning a search.
- Define your purchase goal. Decide whether you are buying a home, a residential investment property or a commercial asset.
- Set your suburb and property-type criteria. Use the council boundary information above to clarify which Inner West markets are actually relevant to your brief.
- Identify which professional advisers you need. Solicitor or conveyancer, mortgage broker, building and pest inspector, strata specialist and, where relevant, a financial adviser or tax specialist.
- Review the buyers agency agreement carefully. Check the scope, fee, payment trigger, conflicts, term and termination rights before signing.
- Decide whether professional representation fits your situation. Use the decision framework above to assess whether buyer-side support matches your time, budget and brief.
Buyers Agency Australia buyer guidance is available for buyers who want to discuss how a strategy-led approach applies to their specific Inner West brief.
If you are ready to define your brief and start the process, map out your next property move with a free strategy session, or contact the Buyers Agency Australia team to discuss your requirements directly.
 General
Learn what a buyers agent in Inner West Sydney does, which suburbs they cover, how the process works,...
Commercial property investment in Australia means buying real estate used by businesses, such as office, retail or industrial property, to earn rental income and potentially build long-term equity. The decision should be based on the lease, tenant strength, true net income, location, building quality, finance and exit options, not headline yield alone. Obtain independent legal, valuation, building, tax and finance advice before committing capital.
You see an advertised commercial property yield and it looks compelling. But before you act on that number, it is worth asking what the lease actually says, who the tenant is, what outgoings are recoverable, and what happens when the lease expires. Office, retail and industrial assets operate in different markets, attract different tenants, and carry different risks. The lease often matters as much as the building itself.
This guide moves from definitions to asset selection, yield analysis, lease review, finance, due diligence and the buying process. Where strategy-led property investment support can make a material difference, we explain why. If you are assessing your first commercial acquisition or broadening a residential portfolio into commercial assets, the commercial property buyers agent service offered by Buyers Agency Australia is designed specifically for that transition.
What Is Commercial Property Investment in Australia?
Commercial property investment means acquiring real estate that is used for business purposes, including office, retail, industrial and mixed-use premises, with the goal of earning rental income and, over time, capital growth. Unlike residential property, a commercial asset is assessed as both a physical building and an income-producing interest. Its value is directly influenced by the lease in place, the strength of the tenant, and the reliability of the income stream.
The Australian Property Institute describes valuation as an evidence-based process that considers rental income, outgoings, condition, location, supply and demand. That framework applies directly to commercial property assessment: a building that looks identical on paper can have materially different value depending on whether the lease is secure, the tenant is financially sound, and the outgoings are recoverable.
How commercial property differs from residential investing
The two asset classes share the same legal framework for ownership but diverge significantly in how income is generated, how tenants operate, and what due diligence is required.
| Factor |
Commercial Property |
Residential Property |
| Tenant type |
Businesses and organisations |
Individuals and families |
| Lease term |
Typically 2 to 10+ years with options |
Usually 6 to 12 months |
| Outgoings |
Often recoverable from tenant (net lease) |
Generally borne by owner |
| Vacancy risk |
Longer periods between tenants |
Usually shorter re-let periods |
| Finance |
Higher deposit, asset-specific LVR assessment |
Standardised residential lending |
| Due diligence |
Lease review, tenant covenant, building, planning |
Building inspection, pest, title |
| Liquidity |
Fewer buyers, longer sale campaigns |
Broader buyer pool |
| Management |
Agent or self-managed with lease obligations |
Property manager typical |
One distinction that many investors underestimate is that commercial leases can require the tenant to carry specific outgoings, such as council rates, insurance, land tax and maintenance, reducing the owner's net cost burden. But that structure depends entirely on the lease wording. Never assume outgoings are recoverable without reading the executed document.
The Main Types of Commercial Property in Australia
Australia's commercial sector is not a single market. Office, retail and industrial assets respond to different economic drivers, attract different tenants, and carry different risks for investors. According to KPMG's June 2026 commercial property market update, Australia's commercial property market is entering a phase of increasing divergence, with retail outperforming, industrial stabilising on structural demand, and office continuing to adjust to hybrid work and AI-driven change. Understanding those distinctions before selecting an asset class is essential.
Office property
Office assets range from single-tenancy suburban buildings to multi-tenancy CBD towers. Tenant demand is influenced by employment conditions, hybrid work policies, building quality, fit-out, accessibility and proximity to transport. Vacancy is a real and ongoing consideration in the office sector, particularly for older or poorly located stock.
A strong office investment typically has a long lease, a financially capable tenant, a well-serviced building with current compliance, and a location that supports reletting if the tenant departs. Building age, environmental ratings, and accessibility under the Disability Discrimination Act all affect both tenant demand and reletting cost.
Retail property
Retail assets include strip shops, convenience centres, neighbourhood shopping centres and mixed-use premises. Tenant demand depends on foot traffic, trade area population, visibility, parking, access and the consumer spending patterns of the surrounding catchment.
Tenants providing essential services, such as medical, childcare, grocery and food, have historically shown more resilience during demand downturns than discretionary retail. Retail tenancy legislation varies by state and territory, and lease obligations around permitted use, fit-out, and make-good can be complex. Obtain state-specific legal advice before committing.
Industrial property
Industrial assets cover warehouses, logistics facilities, manufacturing premises and trade-related buildings. Tenant demand is driven by supply chain requirements, access to arterial roads and freight networks, hardstand area, clear internal height, loading configurations and zoning.
Industrial property has attracted significant investor attention due to structural demand from e-commerce and logistics. However, supply pipelines in some markets have grown, and investors should assess competing stock, tenant usability and whether the building can attract more than one type of occupier before buying.
Which commercial asset profile may suit an investor?
| Factor |
Office |
Retail |
Industrial |
| Lease complexity |
High |
High (retail tenancy law) |
Moderate |
| Tenant concentration risk |
Moderate to high |
Low to moderate |
Moderate to high |
| Vacancy period risk |
Higher |
Moderate |
Lower (current cycle) |
| Income visibility |
Strong if secure lease |
Moderate |
Moderate to strong |
| Management complexity |
Moderate |
Moderate to high |
Lower |
| Exit flexibility |
Narrower buyer pool |
Moderate |
Broader investor demand |
| Minimum capital required |
Higher (CBD) |
Variable |
Variable |
No single asset class is universally superior. The right fit depends on an investor's capital, risk tolerance, income requirements, hold period and capacity to manage lease and vacancy events.
Why Do Investors Consider Commercial Property?
Commercial property can provide income characteristics that differ from residential assets. With a qualified tenant in place and a long lease, investors may benefit from more predictable cash flow, contracted rent reviews, and a business tenancy arrangement where the tenant often has a stronger incentive to maintain the premises.
Portfolio diversification is another consideration. Investors who hold only residential property are exposed to residential market cycles, rental market conditions and residential lending policy. Adding a commercial asset can introduce a different income and capital-growth profile, though that outcome depends heavily on the specific asset, market and lease.
Potential benefits exist alongside real conditions. A long lease provides income visibility only if the tenant remains financially solvent. Rent reviews provide growth only if the review mechanism is favourable and the market rent supports it. The Moneysmart borrowing to invest guidance from the Australian Government makes clear that borrowing to invest is high risk and that income, interest-rate, capital and liquidity risks all apply to commercial property.
What Are the Main Risks of Commercial Property Investment?
Commercial property risks are real and can significantly affect cash flow and capital value. The table below maps core risks to what they look like in practice and what evidence an investor should check.
| Risk |
What it looks like |
Evidence to check |
Mitigation direction |
| Vacancy |
Property is unleased after tenant departs |
Market vacancy rates, historical re-let periods, leasing advice |
Model cash flow with vacancy buffer |
| Tenant default |
Rent arrears or tenant insolvency |
Rent ledger, financial statements, bank guarantee, personal guarantee |
Require documented security |
| Lease expiry |
Tenant does not renew; income stops |
Remaining lease term, option provisions, reletting market |
Run a lease-expiry stress test |
| Incentives at reletting |
Free rent, fit-out contribution required to attract new tenant |
Leasing market evidence, agent advice |
Include in cash-flow model |
| Non-recoverable outgoings |
Outgoings that cannot be charged to the tenant |
Outgoings schedule, lease wording |
Verify recoverability clause by clause |
| Location obsolescence |
Falling demand in the surrounding market |
Local planning, competing supply, employment or population data |
Assess alternate-use potential |
| Liquidity |
Asset cannot be sold quickly |
Comparable sales, days on market, buyer pool depth |
Hold adequate cash reserves |
| Interest rate risk |
Loan repayments rise; income does not |
Finance structure, fixed or variable rate |
Stress test at higher interest costs |
| Capital expenditure |
Major building repairs or compliance upgrades |
Building condition report, services audit |
Commission independent building report |
| Obsolescence |
Building no longer meets tenant requirements |
Building age, services, energy rating, accessibility |
Check current and future tenant standards |
Lease expiry stress test: Before buying, model the property as if the tenant leaves at lease expiry. Include estimated downtime (the period with no rental income), marketing costs, leasing agent fees, rent-free incentive periods, and any fit-out contribution required to secure a replacement tenant. That number is the actual downside exposure, and the investor needs the cash reserves to cover it.
How Do You Assess a Commercial Property Investment Before Making an Offer?
Assessing a commercial property investment requires a structured approach that begins with strategy, not the advertised yield. Starting with the headline number and working backward often leads to confirmation bias, where evidence is selected to justify a predetermined purchase.

A practical assessment sequence moves from strategy fit to location, tenant, lease, building, income, valuation and exit. The Australian Property Institute's valuation guidance describes market rent and valuation quality as processes that require appropriate investigation and physical inspection. That same standard applies to investor-led assessment.
A property investment strategy framework should define the asset type, income requirements, risk limits, hold period and exit pathway before any specific property is shortlisted. Without that anchor, it is easy to be drawn to an available asset rather than the right one.
For national property investment guidance covering multiple markets and asset classes, Buyers Agency Australia supports investors in defining those parameters before searching.
Assess the location and tenant demand
For office assets, consider proximity to public transport, employment density, and the quality of the surrounding precinct. For retail assets, assess the trade area population, traffic counts, visibility and access. For industrial assets, review road access, freight networks, hardstand area and zoning compatibility with the tenant's operations.
Check current and planned competing supply. A well-located property with strong existing tenant demand can still face reletting pressure if a new industrial estate or office development is approved nearby.
Assess the building and future usability
A strong tenant cannot fully offset an obsolete, poorly located or difficult-to-relet building. The building must be assessed independently of the current occupancy. Commission a building condition report, review services and mechanical plant, check compliance with current fire, accessibility and environmental standards, and identify capital expenditure likely within the hold period.
Ask specifically whether the building can attract more than one type of tenant, and whether the permitted use, zoning, access and configuration support future sale or reletting at a realistic cost.
Assess price against income and comparable evidence
Passing rent (what the tenant currently pays) may differ from market rent (what a new tenant would pay today). Where passing rent exceeds market rent, the risk increases significantly at lease expiry. Review the outgoings schedule to identify what costs are recoverable and what the owner carries regardless of occupancy. Compare the agreed purchase price to comparable sales of similar assets in the same market, using evidence from a qualified valuer or recognised data source.
What Matters More Than the Advertised Commercial Property Yield?
The advertised yield is a starting point, not a conclusion. The lease and net income matter more than the headline yield because the brochure figure is almost always a gross yield calculated on passing rent before expenses, and it rarely reflects the true income available to an investor.

Gross yield versus net yield
Gross yield is the annual passing rent divided by the purchase price, expressed as a percentage. It makes no adjustment for outgoings, vacancy, management, or capital expenditure.
Net yield adjusts for the expenses the owner actually carries. Because outgoings recoverability varies by lease, net yield calculations can differ significantly between properties with similar headline figures.
Hypothetical example (illustrative only):
- Purchase price: $2,000,000
- Annual passing rent: $140,000
- Gross yield: 7.0%
- Owner-borne outgoings (non-recoverable): $25,000
- Net operating income (NOI): $115,000
- Net yield: 5.75%
The difference between 7.0% and 5.75% is material over a five-year hold. Any yield comparison must state whether it is gross or net, which outgoings are included, and whether it is based on passing rent or market rent.
How rent reviews, incentives and outgoings change income
Face rent is the headline figure in the lease. Effective rent is the actual income after accounting for incentives such as rent-free periods or fit-out contributions. Where a new or renewed lease includes a significant rent-free period, the effective income in the first 12 to 24 months may be substantially below the face rent.
Rent review mechanisms vary. Fixed-percentage reviews, CPI-linked reviews, and market rent reviews each carry different income implications over the lease term. A lease with annual fixed-rate reviews above CPI can look attractive but may carry reletting risk if the face rent rises well above market at expiry.
For commercial property buying support that includes income analysis and lease-level assessment, Buyers Agency Australia provides end-to-end acquisition support covering sourcing, assessment and negotiation.
Commercial Lease Due Diligence Checklist
The lease is the income engine of a commercial investment. Every material term has a cash-flow consequence. The checklist below groups the key items an investor and their advisers should review before exchanging contracts. The Australian Property Institute's due diligence guidance notes that leased property requires detailed lease review and expert legal advice.

Lease terms:
- Commencement date and expiry date (calculate exact remaining term)
- Option periods: number, notice requirements, eligibility conditions
- Rent review mechanism: fixed, CPI, market or ratchet
- Base rent and any stepped rent schedule
- Security bond, bank guarantee or personal guarantee amount and conditions
- Make-good obligations: what the tenant must restore at expiry
- Permitted use: whether the approved use matches your reletting expectation
- Assignment and subletting rights
- Repair and maintenance obligations by party
Outgoings and financials:
- Outgoings schedule: which costs are recoverable from the tenant
- Rent ledger: at least 24 months of payment history
- Current arrears, payment disputes or rent abatements
- Incentive schedule: any current or outstanding rent-free, fit-out contribution or other incentives
Documents to request:
- Executed lease and all registered variations
- Disclosure statement (where required by state law)
- Outgoings reconciliation for the prior financial year
- Tenant correspondence file and dispute history
Questions to ask about the tenant
Do not assess tenant quality based on brand recognition alone. A nationally known brand can still be a financially stressed tenant, and a smaller local business may have an excellent payment record.
Ask for: the last two to three years of financial statements or trading accounts; the full rent ledger showing payment dates and any short payments; evidence of the security instrument (guarantee, bond); the tenant's business history at the subject property; and whether the tenant occupies the whole building or is one of several occupants creating expiry concentration risk.
Questions to ask about the lease
- What is the remaining term and how many options remain?
- What is the rent review mechanism and when does the next review occur?
- Who is responsible for each category of outgoing?
- What is the make-good obligation and what is the estimated cost?
- Is the security instrument current and legally enforceable?
- Is the permitted use broad enough to attract an alternative tenant?
- Are there any registered encumbrances, caveats or disputes?
- Has the tenant exercised or waived any prior options?
When should lease risk stop the transaction?
Treat the following as review triggers that require either renegotiation, price adjustment or independent expert input before proceeding:
- Passing rent materially above current market rent with no option remaining
- Remaining term of less than two years with no exercised option
- Security instrument that is inadequate relative to the reletting exposure
- Unresolved arrears or active rent dispute
- Make-good obligation likely to cost more than the security instrument covers
- Permitted use so narrow that only one tenant type can legally occupy
These are assessment triggers, not legal advice. Obtain specialist commercial property legal advice before making any decision to proceed or withdraw.
Commercial Property Finance and Ownership Considerations
Commercial lending differs from residential lending in several important respects. Lender assessment considers not only the borrower's financial position but also the asset quality, lease security, tenant strength, property location and valuation. There is no universal deposit or loan-to-value ratio (LVR) that applies across all commercial transactions. Lender policies vary, and individual assessments will depend on the complete transaction picture.
The APRA commercial property lending guidance identifies that authorised deposit-taking institutions must manage commercial property lending risk, including underwriting quality, interest cover and LVR controls. This is regulator guidance for lenders, not a personal lending rule, but it reflects why commercial lenders assess serviceability and interest cover more conservatively than residential lenders in many cases.
Deposits, lender requirements and cash reserves
Commercial borrowers typically need a larger deposit than residential buyers, but the exact requirement depends on the lender, asset type, location, lease security, valuation and borrower profile. Beyond the deposit, investors should model a downside scenario that includes vacancy income loss, major capital expenditure, interest rate increases above the current rate, and delayed settlement costs.
The Moneysmart borrowing to invest guidance makes clear that borrowing to invest is high risk and that investors should ensure they have adequate cash reserves to cover income interruption and cost increases. This applies directly to commercial property, where a vacant period can eliminate income entirely for months or years.
Always obtain advice from a qualified finance broker and solicitor before committing to a finance structure.
Ownership structures and tax considerations
Commercial property can be held by an individual, a company, a trust or a self-managed super fund (SMSF). Each structure has different tax, liability, GST, capital gains tax (CGT) and estate planning implications. This guide does not provide tax or legal advice. Obtain advice from a registered tax agent, accountant and solicitor before selecting a structure, as the right answer depends entirely on the investor's personal circumstances, portfolio, and objectives.
Can an SMSF buy commercial property in Australia?
An SMSF may be eligible to acquire certain commercial property where it qualifies as business real property under superannuation legislation. The Australian Taxation Office identifies business real property and related-party acquisition restrictions that apply to SMSF trustees considering commercial property.
General information only: business real property acquired by an SMSF must meet strict conditions, including the sole purpose test and investment strategy requirements. SMSF trustees must obtain advice from a licensed financial adviser, registered tax agent and solicitor before proceeding. For broader SMSF property investment guidance, the Buyers Agency Australia blog covers key considerations for superannuation property strategies.
The Commercial Property Buying Process in Australia
A disciplined buying process reduces the chance of acquiring the wrong asset under pressure. The numbered stages below reflect a general process; timeframes and requirements vary by state, territory, asset type and transaction complexity. Always confirm the process with a qualified solicitor or conveyancer in the relevant jurisdiction.
| Stage |
Key activity |
Adviser required |
| 1. Set investment brief |
Define asset type, market, budget, income requirements, risk limits, hold period, exit and ownership structure |
Buyers agent, accountant, solicitor |
| 2. Arrange finance pre-approval |
Confirm borrowing capacity, lender appetite, deposit and structure |
Finance broker, accountant |
| 3. Source and shortlist |
Identify on-market, off-market and pre-market opportunities |
Buyers agent, selling agent |
| 4. Inspect and assess |
Physical inspection, lease review, tenant assessment, preliminary yield analysis |
Buyers agent, building consultant |
| 5. Commission valuation |
Independent market valuation from a registered valuer |
Registered valuer |
| 6. Conduct full due diligence |
Legal, lease, building, planning, finance, tax, outgoings and environmental checks |
Solicitor, building consultant, accountant |
| 7. Negotiate and make offer |
Agree price, conditions, settlement terms, access and lease documents |
Buyers agent, solicitor |
| 8. Exchange contracts |
Solicitor reviews contract; conditions satisfied |
Solicitor |
| 9. Settlement |
Final checks, finance drawdown, title transfer |
Solicitor, lender |
Set the investment brief and finance position
Before shortlisting any property, define the asset class, target market, income requirements, maximum vacancy tolerance, ownership structure, hold period and preferred exit pathway. Confirm your finance pre-approval so you know the realistic budget and understand how the lender will assess the specific asset type.
Source and shortlist opportunities
Opportunities come through selling agents, commercial property portals, direct approaches to owners and, where a buyers agent is engaged, off-market and pre-market channels. Apply the same evidence standard to every opportunity, regardless of how it is sourced. An off-market deal is not inherently better value without comparable evidence to support the price.
For a broader view of the step-by-step investment buying process that applies across asset classes, the Buyers Agency Australia blog covers the core stages in detail.
Inspect, value and complete due diligence
Physical inspection must cover the building structure, services, access, compliance, and condition relative to the tenant's use and the re-let standard required. Commission an independent building condition report. Obtain a formal valuation from a registered valuer, not an indicative desktop estimate. Complete legal due diligence covering the lease, title, planning, outgoings and any encumbrances.
Negotiate, exchange and settle
Price is one variable in the negotiation. Conditions, settlement timing, access provisions, lease document completeness and allocation of risk between buyer and seller are all negotiable. Ensure every agreed item is reflected in the contract before exchange. Do not assume verbal agreements will be honoured.
If you would like support defining a commercial acquisition brief and assessing opportunities with discipline, book a free strategy session to discuss your objectives and current position.
When Should an Investor Use a Commercial Property Buyers Agent?
A commercial buyers agent acts exclusively for the buyer. They have no obligation to the vendor, the selling agent or the property. Their role includes helping the investor define an acquisition strategy, identify suitable markets and assets, assess income quality, coordinate due diligence professionals, negotiate terms and manage the transaction to settlement.
For investors who are new to commercial property, interstate, time-constrained, or facing a complex lease situation, a specialist buyers agent can reduce the risk of buying the wrong asset, overpaying, or misreading the income evidence. Understanding what a buyers agent does in detail helps investors assess whether that support is appropriate for their situation.
What Buyers Agency Australia can support
Buyers Agency Australia provides commercial property strategy and sourcing support for investors seeking office, retail or industrial assets. The service is led by Dragan Dimovski, who has over two decades in the commercial property market, and covers strategy-led selection, data-led research, commercial property sourcing, negotiation and end-to-end acquisition support.
This guide includes information about Buyers Agency Australia, the publisher of this article. Service information checked August 2026. Confirm current inclusions and engagement terms before proceeding.
The team applies a research-driven process to market selection, asset shortlisting, income analysis and price negotiation. Buyers Agency Australia operates with a national service footprint and a Sydney base, supporting commercial investors across major Australian markets.
When a commercial buyers agent may not be the right fit
A commercial buyers agent may not be necessary for an investor who already has a clearly defined acquisition strategy, direct relationships with selling agents in the target market, adequate time to source and assess opportunities, and an established team of finance, legal, tax, valuation and building professionals. Self-directed investors with relevant commercial property experience and the capacity to manage the process may prefer to handle the acquisition independently. That is a legitimate choice, and this guide is designed to support investors in either path.
Commercial Property Investment Questions to Ask Before Buying
These questions are designed to expose gaps in the investment case before capital is committed. Each question should have a documented answer backed by evidence, not assumption.
Strategy and objectives:
- Does this asset type, market and income profile fit within your stated investment strategy?
- What ownership structure will you use, and has an accountant and solicitor confirmed it suits your circumstances?
- What is your planned hold period and exit pathway?
Tenant and lease:
- Who is the tenant, what is their business, and what evidence supports their financial capacity?
- How much rent is in arrears, and has it been fully explained?
- What is the remaining lease term, and what does the option structure look like?
- What are the make-good obligations, and what is the estimated cost?
Income and cash flow:
- Is the passing rent above, below or at market rent?
- What is the true net yield after all non-recoverable outgoings?
- Have you modelled the cash flow with vacancy, higher interest costs and capital expenditure?
Finance and capital:
- Has a finance broker confirmed lender appetite for this specific asset?
- Do you have sufficient cash reserves to cover vacancy, repairs and a delayed re-let?
Professional advice:
- Have you obtained independent legal, building, tax, valuation and finance advice?
Exit:
- If the tenant leaves and the rent falls to market, what is the likely sale price?
- What is the worst-case scenario if the property cannot be leased for 12 months?
Frequently Asked Questions About Commercial Property Investment
What is commercial property investment in Australia?
Commercial property investment means buying real estate used by businesses, such as office, retail or industrial premises, to earn rental income and potentially grow equity over time. The main asset classes in Australia are office, retail and industrial property.
Is commercial property investment riskier than residential property investment?
The risks are different rather than simply higher. Commercial property can involve more complex leases, single-tenant concentration, longer vacancy periods and higher due diligence requirements, but it can also offer longer lease terms and more predictable income when the asset and tenant are sound.
What is a good commercial property yield?
There is no universal good yield. A yield must be assessed together with tenant strength, lease security, outgoings recoverability, vacancy assumptions and comparable market evidence. A high yield on a weak lease may represent more risk than a lower yield on a long, secure lease.
What is the difference between gross and net commercial property yield?
Gross yield divides annual passing rent by the purchase price before any expense deductions. Net yield adjusts for the expenses the owner actually carries. The calculation basis must always be stated, as the difference can be substantial.
What should I check in a commercial property lease?
Key items include the remaining term, option periods, rent review mechanism, outgoings recoverability, security instrument, make-good obligations, permitted use, assignment rights, arrears history and any outstanding incentives.
How much deposit do I need to buy commercial property in Australia?
There is no universal deposit amount. Lender requirements vary by borrower financial position, asset type, location, lease security, valuation and individual lender policy. Obtain advice from a finance broker experienced in commercial lending.
Can an SMSF buy commercial property?
An SMSF may acquire certain business real property subject to strict superannuation rules, including sole purpose, investment strategy and related-party restrictions. SMSF trustees must obtain advice from a licensed financial adviser, registered tax agent and solicitor before proceeding.
What does a commercial property buyers agent do?
A commercial buyers agent acts exclusively for the buyer and can support strategy definition, market selection, opportunity sourcing, income analysis, due diligence coordination, negotiation and transaction management, subject to the agreed service scope.
When is commercial property not suitable for an investor?
Commercial property may not suit someone without adequate cash reserves, professional adviser support, capacity to manage lease and vacancy events, sufficient risk tolerance or time to conduct thorough due diligence.
Final Takeaway for Australian Commercial Property Investors
Commercial property investment is not simply a higher-yield version of residential property. It is a lease-backed operating asset where purchase price, tenant covenant, lease security, effective income, building quality and exit usability must all be assessed together before capital is committed.

The most common mistake is beginning with the advertised yield and working backward. A disciplined process starts with strategy, moves to location and asset quality, examines the lease and tenant thoroughly, models the true net income and downside scenario, and confirms that the building can be leased and sold to more than one buyer profile.
Three questions that should have clear, documented answers before any commercial transaction proceeds:
- Does the asset fit the strategy? Asset type, market, income profile, hold period and ownership structure should all align with the investor's wider plan.
- Is the income supported by documents? Lease, rent ledger, outgoings schedule, tenant evidence, valuation and building report should all be reviewed and understood.
- Can the investor withstand the downside case? Model vacancy, rent reduction, higher interest costs, capital expenditure and a delayed exit. If the cash position does not survive that scenario, the risk is too concentrated.
For investors ready to apply this framework to a specific commercial acquisition, the data-led property investment approach at Buyers Agency Australia is built around exactly these considerations: strategy first, evidence always, and professional coordination throughout.
To map out your next property move with a specialist who understands office, retail and industrial assets, book a free strategy session and bring your current brief, finance position and target market to the conversation.
Or contact the team about your plans and discuss how commercial property acquisition support may fit your timeline and objectives.
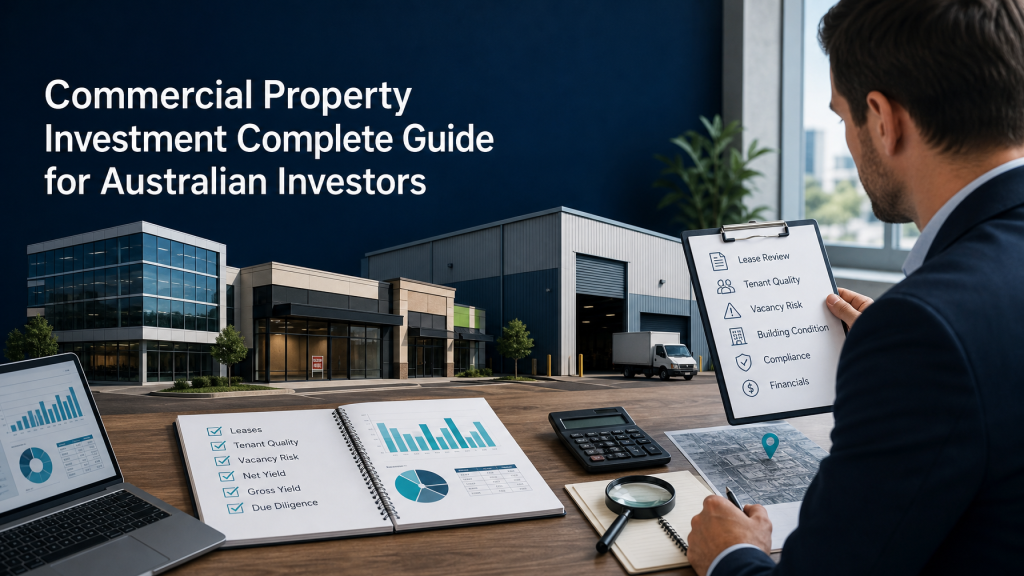 General
Learn how commercial property investment works in Australia, from office, retail and industrial assets to yields, leases, due...
A buyers agent in Sydney's Eastern Suburbs represents the buyer through property strategy, suburb research, sourcing, inspections, value assessment, negotiation, auction bidding and settlement coordination. Buyers Agency Australia presents its Eastern Suburbs service as a strategy-led, data-informed approach for home buyers and investors. In NSW, auction buyers should complete finance, contract, building, pest and strata checks before bidding, because a successful auction bid leads to an immediate contract with no cooling-off period.
If you are weighing up Bondi, Coogee, Randwick, Woollahra or another Eastern Suburbs location, you are probably balancing price range, property type, lifestyle priorities, commute and investment objectives, all at the same time. Add auction pressure and competing buyers to that mix, and decisions can move faster than the evidence allows.
The real question is not simply whether to buy in the Eastern Suburbs. It is how to define a clear brief, test the value of each property before you commit, and build a buying process that holds up under pressure.
This guide covers the buyers agent role, local property types and locations, sourcing, due diligence, auction readiness, and the hiring questions worth asking before signing anything. It also explains how the Buyers Agency Australia investment approach is structured for Eastern Suburbs buyers.
Why Use a Buyers Agent in Sydney's Eastern Suburbs?
Sydney's Eastern Suburbs property market is varied, competitive and, in many pockets, tightly held. Property type changes street by street: freestanding houses, strata apartments, converted terraces and prestige homes all carry different evidence requirements, risk profiles and contract considerations.
Auctions remain a common selling method across the region. Under NSW Government guidance, a buyers agent acts exclusively for the purchaser. The selling agent represents the vendor. Having someone on the buyer's side whose role is to source, assess, negotiate and coordinate, rather than sell, changes the dynamic of every transaction.
Time is a real constraint. Tracking listings, attending inspections, reading contracts, obtaining reports and researching comparable sales across multiple suburbs is a significant commitment, particularly for buyers who are working or managing an existing portfolio.
| Buyers Agent Role |
How It Helps Eastern Suburbs Buyers |
| Buyer-side representation |
Acts only for the purchaser, not the vendor |
| Brief and strategy |
Translates goals, budget and priorities into a defined search |
| Suburb research |
Assesses location fit against brief, not headlines |
| Property sourcing |
Reviews on-market listings and explores other channels |
| Value assessment |
Applies comparable sales and condition analysis before any offer |
How Does a Buyers Agent Help Eastern Suburbs Buyers?
A buyers agent helps by first developing a clear acquisition brief. That brief captures budget, finance position, preferred property type, target locations, risk tolerance and intended use (owner-occupier, residential investment or otherwise). From that point, the agent researches and sources suitable properties, arranges and attends inspections, assesses value against comparable sales data, and manages negotiation or auction bidding with a written walk-away limit.
Through to settlement, the agent coordinates with solicitors, conveyancers, building and pest inspectors, and other qualified professionals, while those professionals remain responsible for their specialist advice. To understand what a buyers agent actually does across each stage, the process is more structured than many buyers expect.
When Might a Buyers Agent Not Be the Right Fit?
Buyers who have the time, direct market knowledge, professional support and a very narrow brief may choose to manage parts of the process themselves. A buyers agent adds most value when the brief is complex, the market is competitive, the property type requires detailed due diligence, or the buyer lacks time to run a thorough process. For some buyers, a negotiation-only or auction-bidding service may be a better scope than full search support.
What Does a Buyers Agent Do for Eastern Suburbs Buyers?
The buyer-side process covers more stages than most buyers realise before they start.
| Stage |
Buyer Decision |
Support Provided |
| Strategy |
Define goals, budget, type, location |
Brief development and target setting |
| Search |
Identify suitable properties |
On-market review and broader sourcing |
| Inspection |
Assess condition and fit |
Attended or represented inspections |
| Value assessment |
Estimate fair price range |
Comparable sales and condition review |
| Negotiation |
Agree price and terms |
Written authority and walk-away position |
| Auction |
Bid with a defined maximum |
Pre-auction checks and bidding representation |
| Legal and finance |
Review contract and confirm finance |
Coordination with solicitor and lender |
| Settlement |
Complete the purchase |
Settlement follow-through and final checks |
Each stage has a decision gate. A buyer can pause, revise the brief or decline to proceed if the evidence does not support the property. No buyers agent can guarantee any particular outcome, and specialist advice from solicitors, valuers, inspectors and mortgage professionals remains essential throughout.
From Property Brief to Shortlist
A useful brief goes beyond suburb preference. It captures the budget ceiling, borrowing position, deposit and acquisition-cost assumptions, preferred dwelling type (house, apartment, townhouse or prestige home), non-negotiables, timeframe and who the key decision-makers are.
Investment buyers add a layer: intended rental use, holding period, tax-structure considerations (which should be referred to a qualified accountant), and how the property fits an existing or planned portfolio. Residential investment-specific thinking is covered in more depth at how a buyers agent helps Sydney investors.
The brief shapes everything that follows. A vague brief produces a scattered search. A clear brief with defined parameters produces a more disciplined shortlist and faster, cleaner decisions.
From Shortlist to Offer or Auction
Once a property reaches shortlist stage, the agent applies comparable sales research using publicly available NSW property sales information from the NSW Valuer General, cross-referenced with condition, land size, aspect and contract terms. A written walk-away limit is agreed before any offer is made or auction bid is placed.
Negotiation authority is defined in the buyers agency agreement. The agent negotiates on price, terms and conditions within that authority. For off-market or pre-market opportunities, the same evidence discipline applies: access to a property through a private channel does not change the need for thorough assessment. Strategy-led property buying support means the shortlist is built on evidence, not availability.
Which Eastern Suburbs Sydney Locations and Property Types May Suit Your Brief?
The Eastern Suburbs span a range of settings, price points and property types. Suitability depends on the buyer's brief, not on a ranking. The confirmed Eastern Suburbs buyers agent service covers the following locations, among others.
Eastern Suburbs Locations to Consider by Buyer Priority
| Buyer Priority |
Locations to Consider |
Property Types Common to Area |
| Coastal access and beach lifestyle |
Bondi, Coogee, Bondi Junction surrounds |
Apartments, townhouses, some freestanding homes |
| Harbour-side or prestige setting |
Vaucluse, Rose Bay, Darling Point, Double Bay |
Prestige houses and apartments, waterfront |
| Village character and terrace homes |
Paddington, Woollahra |
Terraces, semi-detached homes, boutique apartments |
| Apartment concentration, transport, university proximity |
Randwick, Bondi Junction |
Strata apartments, townhouses |
Planning context for local government areas including Randwick, Waverley and Woollahra sits within the NSW Eastern City District Plan, administered by the NSW Department of Planning. Verify any specific zoning, development or infrastructure claim through the relevant council or NSW Planning Portal before treating it as a buying decision.
Houses, Apartments, Townhouses and Investment Property
Freestanding houses in the Eastern Suburbs require a building and pest inspection, a title search and a comparable-sales review tied to recent street-level sales, not suburb-wide medians. Strata apartments and townhouses require those same checks plus a full strata report covering by-laws, levies, sinking fund, meeting minutes and any special levies. Prestige properties require additional evidence: a licensed valuation is worth considering where comparable sales are limited.
For investment buyers, rental assumptions, strata levies and holding costs need to be tested realistically and referred to a qualified accountant or financial adviser before committing. Do not base an investment decision on estimated yield figures that have not been independently verified.
How Does the Property Search and Buying Process Work?
A structured Eastern Suburbs buying process runs through seven stages.

- Initial strategy session. Clarify the brief, budget, finance position and intended use. Identify priority locations and property types.
- Finance preparation. Confirm borrowing capacity with a lender or mortgage broker. Know your maximum before searching.
- Active search. Review on-market listings. Explore relevant channels for properties that may not yet be publicly listed.
- Inspection and shortlisting. Attend inspections. Filter properties against the brief and condition before progressing.
- Due diligence. Commission building and pest inspections. Review the contract with a solicitor or licensed conveyancer. Obtain a strata report where applicable.
- Negotiation or auction. Make an evidence-based offer or bid within a written maximum. Do not proceed without completed due diligence.
- Settlement coordination. Coordinate with the solicitor, lender and other professionals through to settlement and handover.
The ready-to-proceed checkpoint before stage six is not optional. Committing before finance, contract review and inspections are complete is the most common source of regret for buyers in this market.
What Should Buyers Prepare Before Engaging a Buyers Agent?
Before your first conversation with a buyers agent, confirm your budget ceiling, borrowing position (speak to a lender or mortgage broker), deposit amount, estimated stamp duty and acquisition costs, preferred property type, non-negotiables, realistic timeframe and who needs to be involved in decisions. Tax structure and lending questions should be referred to a qualified accountant and mortgage professional respectively. Arriving prepared shortens the strategy session and speeds up the search considerably.
How Are On-Market and Off-Market Property Opportunities Found?
On-market properties are listed publicly through major portals and selling agents. A buyers agent monitors these listings systematically and filters against the brief, saving the buyer from reviewing unsuitable properties. Beyond public listings, buyers agents may identify pre-market or off-market opportunities through relationships with selling agents and direct outreach.
What Does Off-Market Property Access Really Mean?
An off-market property is one that is available for sale but has not been publicly advertised. Access to off-market opportunities depends on the seller's circumstances, the selling agent's relationship with the buyers agent, the property's location and timing. It is a channel, not a guarantee.
Private access does not automatically mean the property is available at a discount, in better condition or exclusively offered. Every off-market property requires the same due diligence as a public listing: comparable sales review, building and pest inspection, strata report where applicable, contract review and finance confirmation. "May identify" is the honest framing for off-market access, not "guaranteed access."
What Due Diligence Matters Before Buying in the Eastern Suburbs?
Due diligence in the Eastern Suburbs covers five areas. Work through each before any unconditional commitment.
Suburb and comparable sales evidence
- Review recent comparable sales from NSW Valuer General property sales data
- Assess price against condition, land size, aspect, floor plan and street
- Walk away if comparable sales do not support the asking price or reserve
Property condition
- Commission a qualified building and pest inspector
- Walk away if structural defects, pest damage or significant maintenance items are identified that the vendor will not address
Legal and title
- Have a solicitor or licensed conveyancer review the contract under NSW Fair Trading guidance
- Check title, easements, covenants and encumbrances
- Walk away if title issues cannot be resolved before exchange
Financial assumptions
- For investment properties, stress-test rental assumptions rather than accepting estimated yields at face value
- Walk away if holding costs at realistic vacancy and interest rates make the investment unviable
Risk and environmental
- Check flood mapping, heritage overlays and zoning through the NSW Planning Portal and relevant council
- Walk away if insurability, development restrictions or environmental risk is unacceptable
A thorough property investment due diligence checklist covers each of these categories in more depth. Once your due diligence is complete, book a free strategy session to work through the results before committing.
What Should Apartment and Townhouse Buyers Check?
Appartment and townhouse buyers in the Eastern Suburbs should request and review the full strata report before making any offer. Under NSW Government strata guidance, key items to check include:

| Strata Item |
What to Look For |
Walk-Away Trigger |
| Strata plan and by-laws |
Lot boundaries, permitted use, renovation rules |
Restrictions inconsistent with intended use |
| Levies and sinking fund |
Current quarterly levies, fund balance |
Underfunded sinking fund suggesting future special levies |
| Meeting minutes (2 years) |
Disputes, planned works, committee decisions |
Unresolved building defects or legal disputes |
| Special levies |
Any outstanding or upcoming special levies |
Large unbudgeted cost not disclosed by vendor |
| Building condition report |
Cladding, waterproofing, structural matters |
Defects that affect safety or are costly to remediate |
| Owners corporation records |
Insurance, contractor reports, compliance |
Lapsed insurance, major compliance failures |
| Parking and storage |
Lot entitlement vs actual allocation |
Parking not included in lot title |
Distinguish a lot-level issue (affecting your unit only) from a building-wide issue (shared liability across all owners). Building-wide defects can generate special levies affecting every lot.
What Should Buyers Know Before Bidding at Auction?
Auctions in NSW carry specific legal consequences. Under NSW Government auction rules, the successful bidder must sign the contract and pay the deposit on the day. There is no cooling-off period. If you cannot complete the contract, you will lose your deposit and may face additional liability.

Do not bid until you have:
- Written finance pre-approval with a confirmed maximum
- A reviewed and acceptable contract (solicitor or licensed conveyancer)
- A completed building and pest inspection report
- A strata report for apartments and townhouses
- A written maximum bid agreed with your buyers agent in advance
- Confirmed registration with the selling agent (name, address, proof of identity required in NSW)
A buyers agent can bid at auction on your behalf where appropriately authorised and licensed, and where a written bidding authority and maximum price have been agreed in advance. Auction strategy, including when to bid and when to walk away, is agreed before the auction starts, not during it.

How Do You Choose the Right Buyers Agent for Eastern Suburbs Sydney?
Choosing the right buyers agent requires more than checking their suburb knowledge. Use these questions before signing a buyers agency agreement.
Questions to Ask Before Signing a Buyers Agency Agreement
- Licence status. Is the agent licensed under NSW property laws? Check Service NSW for current licence details.
- Buyer-side only. Does the agency act exclusively for buyers, or does it also list properties for sale? Dual-agency arrangements can create conflicts.
- Local experience. What is their direct experience buying in the specific Eastern Suburbs locations relevant to your brief?
- Service scope. Does the agreement cover strategy, full search, inspections, negotiation and auction? Or only some stages? Confirm what is included.
- Fee basis. How is the fee calculated? When is it payable? What happens if no property is purchased? Buyers Agency Australia's fee arrangements should be confirmed directly with the team before engagement, as no specific fee amounts have been independently verified for this guide.
- Conflict disclosure. How are conflicts of interest identified and disclosed? Is there a referral relationship with any selling agent or property marketer?
- Auction authority. Who sets the maximum bid? Who attends and bids on the day? Is this covered in the written agreement?
- Due diligence responsibility. Which checks does the agent coordinate, and which require separate engagement of inspectors, valuers, solicitors or conveyancers?
- Reporting and communication. How often will you receive updates? In what format?
- Termination terms. What are the conditions for ending the agreement if the relationship is not working?
Buyers Agency Australia's Approach to Eastern Suburbs Property Buying
This section describes Buyers Agency Australia's own service and approach as presented on its current website. Service and licence details were checked against the Buyers Agency Australia website in August 2026. Confirm current scope, fees and availability directly before engaging.
Buyers Agency Australia approaches Eastern Suburbs property buying through a three-stage framework: strategy and brief development, property sourcing and assessment, and negotiation through to settlement.
A Strategy-Led Approach for Homes and Investment Property
Dragan Dimovski, the Class 1 Licensee at Buyers Agency Australia with 20-plus years of property experience, leads the strategy-led process. The approach begins with a defined acquisition brief that distinguishes between owner-occupier priorities and residential investment priorities before any search commences.
For owner-occupiers, the brief captures lifestyle, space, location and long-term fit. For residential investment buyers, it captures intended use, holding assumptions, finance structure and portfolio context, with tax and financial advice referred to qualified professionals.
For buyers whose brief involves office, retail or industrial property rather than residential, Buyers Agency Australia provides a separate pathway through its commercial property buyers agent service. That service is distinct from the residential Eastern Suburbs process.
When This Approach May Not Be the Right Fit
Buyers Agency Australia may not be the right fit if:
- You are seeking a free or no-obligation property search with no fee structure
- You expect a guaranteed purchase outcome, guaranteed off-market access or guaranteed pricing discount
- You need tax advice, legal advice, finance advice, a property valuation or a building and pest inspection from your buyers agent directly (those services require separate qualified professionals)
- Your brief is entirely self-directed and you only need a conveyancer to handle exchange and settlement
- You are pursuing a commercial acquisition such as office, retail or industrial property as your primary brief (see the commercial property acquisition guidance for that pathway)
Frequently Asked Questions About Buyers Agents in Sydney's Eastern Suburbs
What Is a Buyers Agent in NSW?
A buyers agent in NSW is a licensed real estate professional who acts exclusively for the property buyer. Unlike the selling agent, who represents the vendor, a buyers agent sources, assesses, negotiates and coordinates the purchase on the buyer's behalf. NSW Government guidance confirms the permitted buyer-side role and the licensing obligations that apply.
How Much Does a Buyers Agent Cost in Sydney's Eastern Suburbs?
Fee structures vary by agency, scope and agreement. Fees may be structured as a flat engagement fee, a percentage of the purchase price, or a combination. No specific fee amounts for Buyers Agency Australia have been independently verified for this guide. Confirm the current fee basis, payment timing and what is included directly with the team before signing.
Can a Buyers Agent Bid at Auction for Me?
Yes, where the agent is appropriately licensed and a written bidding authority with a confirmed maximum price has been agreed in advance. All due diligence, contract review, inspections and finance approval must be completed before the auction, because there is no cooling-off period in NSW once the hammer falls.
Can a Buyers Agent Find Off-Market Property in Sydney?
A buyers agent may identify off-market or pre-market opportunities through selling-agent relationships and targeted outreach. Access depends on the seller's circumstances, the agent's network and timing. Off-market access is not guaranteed, and any property identified through private channels requires the same due diligence as a publicly listed property.
Is a Buyers Agent Worthwhile for an Eastern Suburbs Investment Property?
Value depends on the buyer's experience, time availability, brief complexity and risk tolerance. For investors who are unfamiliar with strata assessment, comparable-sales analysis, Eastern Suburbs property types or auction dynamics, structured buyer-side support can reduce the risk of committing before the evidence supports the decision. A buyers agent does not guarantee any return, yield or capital growth.
What Suburbs Does Buyers Agency Australia Cover?
Buyers Agency Australia's Eastern Suburbs service covers key locations including Bondi, Bondi Junction, Coogee, Randwick, Woollahra, Rose Bay, Vaucluse, Double Bay, Paddington and Darling Point, among others. Confirm current service coverage directly with the team, as service areas can change.
Do Buyers Agents Handle Due Diligence?
Buyers agents can coordinate and review due diligence information, including commissioning inspections, reviewing strata reports and liaising with the solicitor or conveyancer. However, qualified building inspectors, pest inspectors, licensed conveyancers, solicitors, valuers and financial advisers remain responsible for their specialist assessments. The buyers agent coordinates; the specialists advise.
What Is the Difference Between a Buyers Agent and a Selling Agent?
A selling agent is engaged by and legally represents the vendor. Their obligation is to the seller. A buyers agent is engaged by and legally represents the buyer. Their obligation is to the purchaser. In NSW, the same agency cannot act for both parties in the same transaction without explicit consent and conflict disclosure, as outlined in NSW Government property-buying guidance.
How Do I Start Buying Property in the Eastern Suburbs?
Start by clarifying your brief: what you are buying, your finance position, your timeframe and your non-negotiables. Confirm your borrowing capacity with a lender or mortgage broker before searching. Then arrange a strategy discussion to map the brief against available options. The process is more productive when finance is confirmed and priorities are clear.
Next Steps for Buying Property in Sydney's Eastern Suburbs
Before engaging any buyers agent or making any offer, work through three practical questions.
What am I buying? Home, residential investment or a separate commercial acquisition such as office, retail or industrial property. Each has a different brief, evidence trail and professional support team.
What evidence do I need before committing? Finance approval, comparable-sales review, building and pest inspection, strata report where applicable, contract review from a solicitor or conveyancer, and a realistic assessment of holding costs.
What support do I actually need? Strategy only, property search, negotiation, auction bidding or end-to-end support from brief through settlement. Match the scope to the brief.
If you are ready to map out your next property move, book a free strategy session to work through these questions with the team. You can also contact the Buyers Agency Australia team directly to discuss your brief and confirm current availability.
 General
Learn how a buyers agent in Sydney's Eastern Suburbs helps with suburb research, sourcing, due diligence, auction bidding,...