A buyers agent in Australia represents the property buyer rather than the seller. They can help define the brief, source suitable properties, assess value and risk, coordinate due diligence, negotiate, bid at auction, and support the transaction through settlement. Fees, licensing requirements, and service scope vary, so review the agency agreement carefully and confirm the agent's current credentials before engaging them.
If you are comparing investment properties across multiple cities while holding down a full-time job, or trying to buy interstate without flying in for every inspection, you already understand the coordination problem. The question most buyers ask too late is not where to buy, but who is actually working for them, how each decision gets tested, and what the engagement agreement really includes.
Professional buyer-side representation is not the right fit for every situation. For investors and strategic owner-occupiers who need research depth, negotiation discipline, and a structured process from strategy to settlement, it can materially change the quality of the decisions being made. Buyers Agency Australia provides national investment property buying support focused on strategy-led acquisition, suburb analysis, and end-to-end buyer-side guidance.
This guide explains what a buyers agent does, who benefits, what to look for, how fees work, and the key questions to ask before signing anything.
What is a buyers agent in Australia?
A buyers agent, sometimes called a buyers advocate, is a licensed property professional engaged by the purchaser to represent their interests throughout the buying process. The role is distinct from a selling agent, who is appointed by and works for the vendor.
Under NSW Government guidance on buying property, a buyers agent can search for properties, assess them, negotiate on price and terms, bid at auction, and help coordinate the steps leading to settlement. Licensing requirements and consumer protections vary by state and territory, so rules that apply in NSW do not automatically apply nationally.

The buyers agent may coordinate professional inspections, legal reviews, and due diligence reports, but does not replace the solicitor, conveyancer, building inspector, pest inspector, or finance professional. Those professionals remain essential, and the buyer remains responsible for their own decisions.

To understand more about what a buyers agent does in practice, the role is best understood through the sequence of tasks they perform on the buyer's behalf.
Buyer-side representation versus a selling agent
| Role |
Who they represent |
How they are paid |
Primary obligation |
| Buyers agent |
The purchaser |
Buyer-paid fee (fixed, percentage, or staged) |
Act in the buyer's interest |
| Selling agent |
The vendor |
Vendor-paid commission on sale |
Achieve the best result for the seller |
The selling agent's obligation is to the vendor. They are not working against the buyer, but their incentive structure is aligned with the sale. Before signing any agency agreement, confirm exactly who the agent represents, whether any referral or dual-agency arrangement exists, and what disclosure obligations apply in your state.
Are buyers agent and buyers advocate the same thing?
Yes, in Australian property, buyers advocate is widely used as a synonym for buyers agent. Both terms describe a licensed professional acting for the purchaser. The scope of what each engagement covers depends entirely on the written agreement, so the label matters less than the documented inclusions.
What does a buyers agent actually do in Australia?
The process runs in a logical sequence from defining the brief through to settlement support. Each stage builds on the previous one, and the scope included at each stage must be confirmed in writing before the engagement begins.

Strategy, budget and property brief
The engagement typically starts with a strategy conversation covering the buyer's goals, finance position, borrowing capacity, timeline, risk tolerance, preferred markets, and the role this property should play in their broader portfolio.
This initial brief controls everything that follows. A search begun without a clear asset-role framework tends to produce a long list of attractive but unsuitable properties. Defining what the property must do before the search starts is one of the most practical ways a buyers agent can reduce wasted time.
For investors, that framework usually includes cash-flow requirements, growth objectives, expected hold period, and how the new asset interacts with existing holdings. For owner-occupiers, it covers location, property type, timing, privacy requirements, and budget ceiling.
Property search and off-market sourcing
Once the brief is set, the agent searches across publicly listed properties, pre-market opportunities where they exist, and off-market situations where a vendor may consider a direct approach.
Off-market sourcing is a genuine part of the market in some circumstances, but it is worth being clear-eyed about it. Not every off-market property represents better value, and access to off-market stock depends on the agent's local relationships, track record, and the specific market at the time. The search process also needs to cover publicly listed properties thoroughly, because the majority of quality stock reaches the open market.
Market assessment and property due diligence
For each shortlisted property, a well-structured engagement includes comparable sales analysis, suburb fundamentals assessment, rental evidence where relevant, property condition review, strata or body corporate records where applicable, and planning and zoning checks.
The agent coordinates professional building and pest inspections, legal review, and any specialist reports required. They do not replace those professionals. The evidence gathered at this stage forms the basis for the negotiation limit and price strategy.
Negotiation, auction bidding and settlement coordination
Armed with the due diligence evidence, the buyers agent can negotiate on price and terms or represent the buyer at auction under a written authority and an agreed maximum price.
For a full understanding of buyers agent responsibilities across the negotiation and settlement stages, confirm what is included in writing. Some engagements include contract review coordination, finance timeline management, and settlement liaison; others stop at an agreed offer.
Settlement coordination typically involves liaising between the buyer's solicitor or conveyancer, the selling agent, and the lender to keep the transaction progressing. This part of the process is often underestimated when buyers compare service inclusions.
For a clear picture of how the buying process works from brief to settlement, review the full process before committing to an engagement.
Who can benefit from a buyers agent?
Buyer-side representation is not universally necessary. Whether it makes sense depends on the buyer's time, experience, location, portfolio objectives, and appetite for managing the process independently.
Property investors
For investors, the case for representation is usually about process discipline and decision quality rather than convenience alone. Suburb selection, property type, rental evidence, yield and growth trade-offs, due diligence depth, and negotiation strategy all carry real financial consequences.
Interstate acquisition is a common scenario where the value of representation increases. Buying in Brisbane or another market from a Sydney or Melbourne base means relying on inspections you cannot attend, market knowledge you have to build quickly, and a negotiation you are running remotely. Brisbane investment property support through a local buyer-side agent can reduce the coordination burden substantially.
Busy, interstate and remote buyers
Time-poor professionals who cannot attend open homes, arrange multiple inspections, follow up on off-market leads, or monitor auction clearance data across several suburbs are the clearest candidates for full-service representation. The opportunity cost of attending to all of this while managing a career is real, even for buyers who understand property well.
Remote buyers still need to set clear inspection reporting standards, establish written communication expectations, and confirm that the agent can physically attend inspections in the target market. Service coverage and local availability must be checked before engaging.
Strategic owner-occupiers
Some owner-occupiers have specific property requirements, privacy preferences, strong timing constraints, or are entering a highly competitive auction market for the first time. Buyer-side representation can help manage the search, assess value against comparable sales, and handle auction bidding under a clear authority and agreed limit. A confident local buyer who has time, recent relevant experience, and no specific complexity may find they can manage the process themselves.
How can a buyers agent help with an investment property?
The question is not whether a buyers agent can find properties; most active investors can find properties independently. The more useful question is whether a structured, evidence-led buying process produces better decisions than an unstructured one.

Moneysmart's guidance on buying an investment property notes that property investment carries concentration risk, ongoing costs, and variable income, and that expected returns are not guaranteed. A buyers agent does not change those fundamentals, but a disciplined process can reduce avoidable mistakes.
Matching the property to the investment strategy
The right investment property for one buyer may be the wrong one for another. The asset needs to fit the investor's cash-flow requirements, capital growth objectives, borrowing capacity, intended hold period, tax position, and existing portfolio exposure.
An investor who needs positive cash flow to support their next purchase has different requirements from one who can hold a neutral or negatively geared property while building equity. Without a clear asset-role filter applied before the search, the shortlist tends to fill with properties that look appealing but do not perform the right function in the portfolio.
The Australian Taxation Office guidance on rental properties outlines the income, deduction, and record-keeping requirements for investment property owners. Tax-specific advice should always come from a qualified accountant or tax adviser.
Reducing avoidable buying mistakes
Common gaps in unrepresented investment purchases include emotional bidding beyond a defensible price, weak comparable sales evidence, incomplete inspections, rental yield assumptions that do not account for vacancy periods or management costs, and overlooked ongoing ownership costs such as strata levies, rates, and insurance.
A structured due diligence process, tested against comparable evidence and reviewed by the relevant professionals, reduces exposure to these gaps. It does not eliminate investment risk, but it creates a more defensible basis for each decision.
What should you look for when choosing a buyers agent?
Choosing the right buyers agent requires more than checking reviews or comparing headlines. The evaluation should focus on independence, licensing, investment expertise, market coverage, process transparency, fees, and the written documentation you will be asked to sign.
Independence, conflicts and disclosure
Ask directly: does the agent receive any payment, referral fee, commission, or benefit from the vendor, developer, property manager, or any other party connected to the transaction? Consumer Protection Western Australia's guidance on using a buyers agent recommends confirming the agent's representation and whether any conflicts exist before signing anything.
A buyers agent who receives referral payments from property managers, developers, or other service providers has an interest that may not align completely with the buyer. Ask for written disclosure of every financial relationship.
A useful independence test: ask the agent what evidence would lead them to advise you not to proceed with a property. An agent genuinely working in your interest should be able to answer that question clearly and specifically.
Licensing and relevant experience
Licensing requirements for buyers agents vary by state and territory. In NSW, real estate agent licensing through NSW Fair Trading covers the activity of acting for prospective purchasers. Other states have their own licensing classes and registers.
Always check the agent's licence directly on the relevant state or territory register before engaging them. Do not accept a verbal or document-only claim of licensing without independent verification.
For investment-focused engagements, also ask how many investment property transactions the agent has completed in the target market, what their property assessment process involves, and how they distinguish between a property that fits the brief and one that simply fits the budget.
Scope, process and communication
Before signing, require a written explanation of every inclusion: property search, inspection attendance, due diligence coordination, comparable sales reports, negotiation authority, auction bidding, contract review coordination, settlement liaison, and communication frequency. Ask specifically what is not included and what costs extra.
How much does a buyers agent cost in Australia?
Fees vary depending on the service model, the market, the property value, and the scope of the engagement. No single national fee standard exists, and the written agency agreement controls the exact obligation.

Common fee structures
| Fee model |
How it works |
What to clarify |
| Fixed fee |
A set dollar amount agreed at engagement |
Is it all-inclusive or does auction, travel, or other services cost extra? |
| Percentage-based fee |
A percentage of the final purchase price |
Does a higher price mean a higher fee? What is the base rate? |
| Staged fee |
An engagement fee plus a success fee on purchase |
When does each component become payable? What triggers the success fee? |
| Search-only or negotiation-only |
A partial-service fee for a defined scope |
What is explicitly excluded? Is this sufficient for the buyer's situation? |
For a detailed breakdown of buyers agent fee structures by state and service type, review that resource before committing to a quote.
What is included and what costs extra?
Before accepting any quote, ask about GST, building and pest inspection costs, travel for inspections in outer suburbs or regional areas, auction attendance fees where separate, legal review coordination, property management referral fees, and what happens financially if no purchase proceeds.
The total cost of an engagement is always higher than the headline fee. A total-cost checklist should include the agent fee plus GST, professional inspection costs, legal and conveyancing fees, stamp duty, and any additional services listed as extras in the agreement.
What should a buyers agency agreement state?
The buyers agency agreement should clearly state the scope of services, the term of the engagement, termination rights and any associated costs, the exact event that triggers the fee, exclusivity or non-exclusivity terms, all conflict and referral disclosures, and the buyer's obligations during the search period.
Read the entire agreement before signing. If any term is unclear, seek independent legal advice before committing.
The Buyers Agency Australia approach
Buyers Agency Australia is a buyer-side property advisory service with a national service positioning, based in Sydney. The approach, as described in current brand material, is built around strategy-led acquisition rather than property searching as the starting point.
Service details, availability, fees, and scope described in this section are based on brand material reviewed in August 2026. Confirm current inclusions and availability directly with Buyers Agency Australia before engaging.
Starting with strategy before property search
The process at Buyers Agency Australia begins with a strategy conversation that clarifies the buyer's portfolio objectives, finance position, target markets, risk tolerance, and the role the next property needs to perform.
That strategy brief then controls the search. Rather than presenting a wide range of properties and letting the buyer filter, the goal is to narrow the search criteria before any properties are shortlisted. This reduces the time spent on properties that look attractive but do not serve the stated investment objective.
If you want to test whether your current property goals are clearly defined before committing to any agency agreement, book a free strategy session to map out the brief before the search begins.
Property selection, analysis and negotiation
Following the strategy brief, the service covers property sourcing across listed and, where applicable, pre-market and off-market channels, comparative market analysis, due diligence coordination, and negotiation or auction representation. Settlement support and documentation coordination are included in the full-service engagement, though the specific scope should be confirmed in writing at the time of engagement.
The focus on strategy-led property buying is intended to connect the initial investment brief to each stage of the process, rather than treating search, assessment, and negotiation as separate tasks.
The experience of Dragan Dimovski
Dragan Dimovski is the founder and senior buyers agent at Buyers Agency Australia, with 20+ years of experience in property investment across Australian and international markets. His background includes data-informed suburb analysis, investment strategy planning, and buyer-side negotiation. Brand material reviewed for this article supports those details; no additional credentials, awards, or outcomes have been added beyond what current official brand material confirms.
When Buyers Agency Australia may not be the right fit
Buyers who prefer to conduct the property search themselves, attend all inspections personally, manage due diligence coordination directly, and handle negotiation independently may not need full-service buyer-side representation. The service is designed for buyers who want structured support across the full acquisition process. If you are confident managing that process yourself, and have the time and local knowledge to do so, the full-service model may not suit your situation.
Questions to ask before engaging a buyers agent
Use these questions in any initial consultation before committing to a buyers agency agreement.
Independence and conflicts
- Do you receive any payment, referral fee, or benefit from vendors, developers, or property managers connected to properties you recommend?
- Are you exclusively acting for me, or do you have any dual-agency arrangement on any property I might purchase?
- What evidence would lead you to advise me not to proceed with a property?
Licensing and experience
- What is your current licence number and which state authority issued it?
- How many investment property acquisitions have you completed in my target market in the past 12 months?
- Can you show me examples of comparable sales analysis you have produced?
Process and scope
- What is included in the written scope of your service from search through to settlement?
- Will you attend every inspection personally, or will another team member attend?
- What is your process for setting a maximum price before a negotiation or auction?
Fees and agreement
- What exactly triggers the fee payment, and is GST included or additional?
- What costs are charged separately from the headline fee?
- What are my rights if I want to end the engagement before a purchase completes?
Support and communication
- How often will you report progress, and in what format?
- Who is my primary contact throughout the process?
- What happens if the search extends beyond the original estimated timeframe?
Is a buyers agent right for you?
The decision comes down to time, experience, location, complexity, and the cost of making avoidable mistakes versus the cost of professional representation.

Representation is likely to make sense if you:
- Are buying interstate or in a market you do not know well
- Cannot attend open homes or inspections regularly
- Are heading into an auction for the first time without a clear bidding strategy
- Are making an investment decision with significant portfolio consequences
- Have a complex brief that requires specialist suburb or property-type knowledge
- Want a second opinion on price and due diligence depth before committing
You may not need full-service representation if you:
- Have recent relevant experience in the target market
- Can attend inspections, manage due diligence, and negotiate confidently yourself
- Are buying in a market you know well and have strong comparable sales access
- Have time to manage the process across each stage without a significant opportunity cost
For buyers who are uncertain, a partial-service engagement covering only negotiation or auction bidding can be a lower-cost way to access professional support for the stages where the financial stakes are highest. Confirm whether partial-service options are available before assuming a full-service engagement is the only option.
For Sydney buyers agent support or for interstate investment searches, confirm local availability and service coverage before committing.
Frequently asked questions about buyers agents in Australia
What is the difference between a buyers agent and a real estate agent?
A buyers agent represents the purchaser and is paid by the buyer. A real estate agent in a selling role represents the vendor and is paid by the seller. Their obligations, fee structures, and loyalties differ fundamentally, which is why confirming representation before any negotiation is important.
Do I need a buyers agent to buy an investment property?
No. Using a buyers agent is optional. Whether it makes sense depends on your time, experience, location, portfolio complexity, and whether you can manage the search, due diligence, and negotiation process confidently yourself.
Can a buyers agent bid at auction for me?
Many buyers agents offer auction bidding as part of or in addition to their standard service. This is subject to the engagement agreement, a written bidding authority, state-specific rules, and an agreed maximum price. Confirm auction attendance and authority terms before the engagement is signed.
Can a buyers agent help an interstate property investor?
Yes, though local availability and service coverage in the target market must be confirmed. Remote buyer support works best when inspection reporting, communication expectations, and decision authority are clearly agreed in writing before the search begins.
How do buyers agent fees work in Australia?
Fees vary by service model. Common structures include fixed fees, percentage-based fees, staged fees combining an engagement and success component, and partial-service fees. The written agency agreement controls the exact payment trigger and total obligation. Review it carefully before signing.
Are buyers agent fees subject to GST?
Buyers agent service fees are generally subject to GST in Australia, but the treatment on your specific engagement should be confirmed on the written quote and agreement. For investment properties, the fee may be treated as a capital cost affecting your cost base for capital gains purposes. Seek advice from a qualified accountant or tax adviser rather than relying on general information.
How do I check a buyers agent licence?
Check the relevant state or territory licence register directly. In NSW, the register is maintained by NSW Fair Trading. Other states have their own regulators and registers. Do not rely solely on a verbal or document-only claim; check the register independently before engaging.
Can a buyers agent guarantee a good property investment?
No. No buyers agent can guarantee capital growth, rental income, a purchase at a specific price, or any investment outcome. Property investment carries genuine risk, as Moneysmart's investment property guidance outlines. A buyers agent can support the quality of the process, not the outcome.
What should I ask before hiring a buyers agent?
Ask about their licence, their conflict disclosure, exactly what is included in the fee, what triggers payment, what due diligence they conduct, whether they attend inspections personally, how they set a maximum price before negotiation or auction, and what happens if the engagement ends without a purchase.
Is a buyers agent worth the fee?
It depends on the buyer's situation. For a time-poor investor buying interstate, heading into a competitive auction, or managing a complex brief, the structured process and negotiation discipline may justify the cost. For a confident local buyer with time and relevant experience, the case is less clear. Evaluate the service scope against your specific needs before deciding.
Your next step before choosing a buyers agent
Before committing to a property search or agency agreement, work through this short checklist:
- Define what the property must do for your portfolio or lifestyle, specifically.
- Confirm your borrowing capacity and total purchase costs with a finance professional.
- Check the buyers agent's licence on the relevant state register.
- Read the complete buyers agency agreement, including fee triggers, termination rights, and exclusivity terms.
- Confirm exactly what due diligence, negotiation, auction, and settlement support is included.
- Decide honestly whether professional representation solves a genuine time, distance, expertise, or complexity problem for your situation.
If you want to work through your property strategy with a buyers agent before committing to a search, map out your next property move with Buyers Agency Australia through a no-obligation strategy session.
To speak with the team directly about your situation, contact the team and confirm current service scope, availability, and fees before engaging.
 General
Learn what a buyers agent in Australia does, common fee questions, buyer protections, and how to choose support...
An investment property in Australia is a residential property bought to earn rental income, seek long-term capital growth, or support a wider portfolio. The right purchase starts with an investment strategy and borrowing-capacity check, then moves through suburb research, property assessment, full cost modelling, and legal, building, pest, strata, and planning due diligence. Returns are not guaranteed, so finance, tax, and legal decisions should be checked with the relevant licensed professionals.
You have savings or usable equity, you are seeing conflicting suburb advice, and you do not want your first purchase to limit the next one. That is the position most first-time investors are in when they start searching.
Buying an investment property is not only a property search. It is a strategy decision, a finance decision, a location decision, an asset decision, and a risk decision. Getting the sequence wrong is one of the most common reasons investors overpay, buy in the wrong location, or find themselves stretched after settlement.
This guide follows the approach used by Buyers Agency Australia for strategy-led property buying support, and it includes an honest look at where buyer-side help adds value and where it does not. The article is general information only and does not constitute personal financial, legal, or tax advice.
What is an investment property in Australia?
An investment property is a residential dwelling purchased to generate returns rather than to serve as the buyer's primary residence. It is distinct from a principal place of residence in how it is financed, held, taxed, and assessed as part of a broader plan.
According to ASIC's Moneysmart guidance on buying an investment property, the potential benefits of property investment include rental income, long-term capital growth, and diversification, but costs, vacancy, and market conditions can affect returns significantly.
How an investment property fits a wider portfolio
A single property can serve several portfolio roles: generating rental income to offset holding costs, building equity over time, or acting as a stepping stone toward a larger portfolio. No single property satisfies every objective equally well, and the role the asset plays should be defined before you search.
Rental yield, capital growth, and cash flow are the three primary return drivers. Rental yield is the annual rent expressed as a percentage of purchase price. Capital growth is the increase in property value over a holding period. Cash flow is what remains after all income is received and all costs are paid.
What investment property returns can and cannot tell you
Gross rental yield tells you almost nothing about net return. Once vacancy, property management fees, insurance, council rates, maintenance, loan repayments, and holding costs are subtracted, the actual cash position can look very different from the headline figure.
Past performance and market forecasts do not guarantee future results. Any suburb that performed well over the last cycle may face different supply, employment, or demand conditions in the next one.
Why do Australians invest in property?
Property is one of the most accessible asset classes for Australian investors, partly because residential real estate can be purchased using borrowed funds at relatively accessible loan-to-value ratios compared to other asset classes. According to the Reserve Bank of Australia's May 2026 Bulletin on Australian housing investors, approximately 3.3 million Australians hold an investment property, representing around 10 per cent of the working-age population.

Rental income, capital growth and portfolio building
Rental income provides a regular cash flow that can partially or fully offset holding costs depending on the property, location, and loan structure. Capital growth, when it occurs, builds equity that can support future borrowing or portfolio expansion. Portfolio building involves using the equity and serviceability from the first purchase to position for a second, which is why the first acquisition decision carries disproportionate weight.
Not every property serves all three objectives. A high-yield regional property may generate strong income but limited resale depth. A capital-city property may offer stronger long-term demand but require greater cash reserves to hold through lower-yield years.
The risks property investors need to understand
Property investment carries real risks that every investor should model before committing. Vacancy periods directly reduce cash flow and can be extended in oversupplied markets. Interest-rate changes affect repayment levels and borrowing capacity. Maintenance costs on older properties can be significant and unpredictable.
Market declines, low liquidity, and concentration risk are also material considerations. Unlike shares, a property cannot be partially sold. And owning a single asset in one location means the portfolio is highly exposed to local employment, infrastructure, and planning changes. One investment property can also affect your ability to borrow for the next one, which is a factor many first-time buyers underestimate.
How do you choose an investment property strategy in Australia?
The right property investment strategy approach depends on the investor's objective, cash position, time horizon, and tolerance for holding costs. Strategy selection is the gating decision. A property should be rejected when it conflicts with the portfolio role, even if the suburb is widely discussed.

Growth-focused strategy
A growth-focused investor prioritises long-term capital appreciation over immediate income. The characteristics typically assessed include strong owner-occupier demand, limited land supply, proximity to employment and infrastructure, and a deep buyer pool at resale. Growth-focused properties often have lower yields and require the investor to carry a negative cash flow position for extended periods, so cash reserves and serviceability buffers matter considerably.
Cash-flow-focused strategy
A cash-flow investor prioritises net rental income after costs. The trade-off is that high-yield markets sometimes carry higher vacancy risk, lower capital growth prospects, or thinner resale markets. Assessing operating costs, typical vacancy rates, and tenant demand at the suburb and property level is essential before relying on headline yield figures.
Balanced strategy
A balanced approach seeks both sustainable holding costs and reasonable growth potential. It tends to require more precise suburb and property selection because fewer markets naturally offer both. The investor must be clear about which objective they are willing to compromise if the two come into tension.
Portfolio-building strategy
For investors planning more than one acquisition, the first property sets the borrowing capacity for the second. A purchase that stretches serviceability or ties up too much equity can delay or prevent the next acquisition. Structuring the first purchase with future borrowing capacity in mind is a discipline that separates portfolio-oriented investors from single-property buyers.
| Strategy |
Primary objective |
Trade-off to consider |
| Growth-focused |
Long-term capital appreciation |
Lower yield; may require cash reserves to hold |
| Cash-flow-focused |
Net rental income |
May limit growth prospects; higher vacancy risk in some markets |
| Balanced |
Income and growth combined |
Fewer markets naturally satisfy both |
| Portfolio-building |
First purchase positions the next |
Serviceability and equity must be modelled across acquisitions |
If you are still weighing which approach fits your situation, book a free strategy session before shortlisting any property or suburb.
How do you research locations and suburbs for an investment property?
Suburb selection is not about finding the hottest market. It is about triangulating demand, supply, and risk evidence to identify whether a location's fundamentals support the strategy you have already defined. When researching where to invest, use at least three independent data signals before approving a suburb shortlist.
Employment, population and household trends
Suburbs with diverse employment drivers, growing household formation, and stable population tend to support more consistent rental demand. The ABS Census area search tool provides QuickStats and Community Profile data covering income levels, household type, dwelling mix, and demographic composition at the suburb level. Use this data to understand the demand profile, not to predict capital growth.

For capital cities with Sydney investment property guidance or Brisbane property investment support, the underlying employment and infrastructure context varies considerably by corridor and precinct, which is why broad city-level analysis needs suburb-level refinement.
Rental demand, vacancy and tenant profile
Headline vacancy rates published at a city level can mask significant variation at the suburb and property-type level. A suburb with strong demand for three-bedroom houses may show different vacancy than the same suburb for one-bedroom units. Tenant demand must be assessed at the level of the specific property and street, not inferred from a city average.
Supply, infrastructure and planning changes
New dwelling supply, approved development applications, rezoning decisions, and planned transport or infrastructure projects all affect a suburb's future demand-supply balance. Check official state and local planning portals for development applications and zoning changes. A suburb shortlisted for its current tight vacancy may look different if a large apartment development is approved nearby.
Using Australian capital-city and suburb data responsibly
Medians, means, vacancy rates, and forecasts use different methodologies, reference periods, and property-type definitions across providers. Always note the source, reference period, geography, and property type when citing a statistic. The ABS December quarter 2025 dwelling data records the national mean dwelling price at $1,074,700 and the total value of residential dwellings at $12.3 trillion, with growth most evident in Queensland, Western Australia, and New South Wales for that period. These are national aggregates and do not represent individual suburb or investment-grade property performance.
What should you look for in an investment property?
Once a suburb passes the three-signal test, the property itself must be assessed against tenant appeal, condition, maintenance obligations, and exit liquidity. The question to ask before committing is: who is the next likely buyer of this property, and is the buyer pool deep enough to support a sale when needed?
Houses, units and townhouses
Each property type carries different risk and return characteristics. Houses typically offer land value and stronger owner-occupier demand at resale, but they carry higher maintenance responsibility. Units and apartments can offer more predictable ongoing costs through strata management, but strata fees, sinking funds, and body corporate obligations add a layer of financial exposure that must be reviewed carefully. Townhouses often sit between the two in terms of land, maintenance, and tenant appeal.
No single property type is universally superior. The right choice depends on the target tenant, the suburb's buyer profile, current supply levels, and the investor's capital position.
Tenant appeal and practical property features
Properties with practical layouts, secure parking, adequate storage, good access to public transport, and proximity to employment, schools, and local amenities tend to attract and retain tenants more reliably. These factors also support a broader resale pool.
A property that appeals only to a narrow tenant or buyer demographic carries a liquidity risk that is often not visible in short-term yield calculations.
Condition, maintenance and future resale
Age, construction method, defect history, and renovation requirements affect both the carrying cost and the resale story. An older property may require capital expenditure within a short holding period. A newer property with strata may carry embedded building defect risk, particularly in apartment complexes built during high-volume development cycles.
Get an independent building and pest inspection before committing. A conveyancer or solicitor should review the contract and title. Use recent comparable sales from credible property data sources, not vendor-supplied appraisals, to verify price alignment.
| Assessment area |
Key question |
Professional or source needed |
| Property type fit |
Does it match the target tenant and exit buyer? |
Independent market analysis |
| Condition and defects |
Are there material defects or capital works pending? |
Licensed building and pest inspector |
| Strata or body corporate |
What are the levies, sinking fund, and known liabilities? |
Strata report or solicitor review |
| Comparable sales |
Does the asking price reflect recent market evidence? |
Credible property data provider |
| Planning and zoning |
Are there rezoning or development risks nearby? |
Local council or state planning portal |
| Hazard risk |
Is the property subject to flood, bushfire, or other risk? |
Official state or council hazard portal |
What costs and finance requirements should you budget for?
Gross rent is not cash flow. A realistic investment property budget separates four cost categories: upfront buying costs, ongoing holding costs, financing costs, and eventual exit costs. The formula is: rent received, minus vacancy allowance and operating costs, minus finance costs. Model a vacancy scenario and an interest-rate increase scenario before relying on rent to service the loan.

Upfront buying costs
Upfront costs include the deposit, transfer duty (formerly called stamp duty in many states), conveyancing and legal fees, building and pest inspection, lender valuation, lender establishment fees, and any buyer-side professional fees. Transfer duty varies by state and territory and by whether the property is new or established. Check the relevant state revenue office for transfer duty rules in your location before budgeting. Do not assume a single national rate applies.
Ongoing holding costs
Ongoing costs include loan repayments, property management fees, landlord insurance, council rates, water rates, land tax (which varies by state and threshold), strata or body corporate levies where applicable, and routine maintenance. Budget for periods of vacancy as a normal part of ownership, not as an exceptional event.
Finance, serviceability and borrowing capacity
Lender serviceability assessments apply buffers above the actual interest rate to test repayment capacity. Deposit requirements vary by lender, loan structure, and borrower profile. Speak with a licensed mortgage broker or lender to confirm your actual borrowing capacity, cash reserves required, and the effect of this purchase on future borrowing.
Do not rely on an informal affordability estimate based on current rent. Get written confirmation from a lender before committing to any property.
Negative gearing and tax considerations
Negative gearing may allow eligible investors to claim certain rental losses against assessable income, subject to Australian tax rules and individual circumstances. Tax outcomes depend on income level, loan structure, property type, and current legislation. The ATO's rental property guidance sets out deductible expenses, depreciation rules, and capital gains tax treatment. Always confirm your position with a registered tax professional before structuring a purchase around a tax outcome.
What should be on an Australian investment property due diligence checklist?
Due diligence is not optional. Every item below should be completed or consciously waived before exchanging contracts. If a report identifies an unresolved defect, legal restriction, abnormal strata liability, or material hazard, pause and obtain specialist advice before proceeding.

Building, pest and property condition checks
An independent licensed inspector should assess the structure, roof, plumbing, electrical, and pest condition of the property. Building and pest reports describe visible and accessible conditions at the time of inspection; they do not guarantee that concealed defects, specialist systems, or future issues will be identified. If the report flags significant concerns, obtain a specialist report before exchange.
Contract, title and comparable-sales review
A conveyancer or solicitor must review the contract of sale, title, and any encumbrances before exchange. Legal review requirements and contract processes vary by state and territory. The NSW Government's guidance on buying property in NSW outlines the contract and strata search requirements for NSW purchases; equivalent guides are available from each state and territory government.
Use recent comparable sales from a credible property data source to verify that the contract price reflects current market evidence.
Strata, body corporate and sinking-fund checks
For units and townhouses, request a strata report or equivalent body corporate records. Review levies, the sinking fund balance, known defects, pending special levies, and any history of significant disputes. A depleted sinking fund can mean unexpected capital contributions after settlement.
Flood, bushfire, climate and planning risk
Check the property's actual location against official hazard portals for the relevant state and council. Do not infer flood or bushfire risk from suburb reputation or distance from a known hazard zone. Many councils provide online flood mapping tools. State emergency management portals and planning authorities hold official hazard data. Confirm the applicable planning zone, any overlays, and nearby development applications before committing.
What mistakes do first-time Australian property investors make?
| Mistake |
Why it happens |
Correction |
| Choosing the property before defining its portfolio role |
Excitement or urgency overrides strategy |
Define objective and finance limits before searching |
| Prioritising yield alone |
High yield looks attractive in isolation |
Model full holding costs and vacancy across a cycle |
| Buying emotionally |
The property feels right rather than stacks up |
Apply a written brief and objective assessment criteria |
| Overpaying |
Insufficient comparable-sales research |
Use recent data from a credible source and verify independently |
| Ignoring future borrowing capacity |
First purchase stretches serviceability |
Model how this purchase affects the ability to buy a second property |
| Underestimating holding costs |
Budget based on rent, not net cash flow |
Include vacancy, maintenance, management, and rate-change scenarios |
| Relying on unverified forecasts |
Suburb or market predictions published without methodology |
Use demand, supply, and risk evidence rather than growth predictions |
Moneysmart's guidance on investment property costs, vacancy, and risk reinforces that property investment involves real financial risk and requires careful goal setting before committing funds.
How can a buyers agent support an investment property purchase?
A buyers agent (also called a buyers advocate) is a licensed real estate professional who acts exclusively for the buyer, not the vendor. The selling agent's duty is to the vendor; a buyers agent's duty is to you.
This section describes Buyers Agency Australia's own buyer-side approach and is not an independent comparison of agencies.
Strategy, brief development and suburb selection
Buyers Agency Australia works with investors to define the portfolio objective, confirm finance position, and develop a property brief before beginning any search. This front-end discipline is what distinguishes a strategy-led process from an ad hoc search.
Dragan Dimovski brings 20+ years of personal property investment experience to the brief-setting process. The starting point is always the investor's goals, time horizon, and cash position, not a suburb shortlist.
Sourcing listed, pre-market and off-market opportunities
Buyers Agency Australia may help identify properties not broadly advertised where its current service and relationships support that. Pre-market and off-market opportunities exist when vendors prefer a quiet process, but the volume and quality of such opportunities varies by market, timing, and location. No guarantee of off-market access or specific pricing outcomes is made.
Property analysis, due diligence and negotiation
The buyer-side role covers property analysis, assessment against the brief, due diligence coordination, and negotiation through to settlement. Independent conveyancers, building and pest inspectors, mortgage brokers, and tax professionals remain necessary for their respective areas of expertise. A buyers agent does not replace these professionals; they coordinate alongside them.
For investors who want buyer-side support for investors across research, sourcing, and negotiation, a strategy session is the right first step. Before hiring any buyers agent, there are important questions for a buyers advocate to ask about scope, fees, conflicts, process, and what remains your responsibility.
When a buyers agent may not be the right fit
Investors who prefer to research, inspect, negotiate, and coordinate professionals themselves may not need or want full-service buyer-side support. A buyers agent adds the most value when the investor lacks time, local market knowledge, negotiation experience, or confidence in the due diligence process. It is not a requirement for every purchase.
Investment property Australia: what should you do next?
The decision sequence matters as much as the property itself. Follow these steps before committing to any purchase.
A six-step purchase framework
- Define the portfolio objective. Is the property for income, growth, or to position a future acquisition? Write it down before you search.
- Confirm finance and cash reserves. Get written confirmation of your borrowing capacity, deposit requirements, and buffer from a licensed broker or lender. Pause if this step is incomplete.
- Set the property brief. Define the target property type, price range, location criteria, minimum tenant appeal standards, and acceptable holding cost range.
- Research markets and suburbs. Apply the three-signal test: one demand signal, one supply signal, and one risk signal before approving a suburb shortlist.
- Complete property and legal due diligence. Building and pest inspection, contract review, strata check, comparable sales, hazard check, and rental assessment. Do not skip items because of time pressure.
- Decide whether to proceed independently or seek buyer-side support. If the brief is clear and the research is solid, you can proceed independently. If strategy, sourcing, or negotiation is where you need support, map out your next property move with a professional before committing.
Frequently asked questions about investment property in Australia
What is an investment property in Australia?
An investment property is a residential dwelling purchased to generate rental income, seek capital growth, or support a broader portfolio, rather than to serve as the owner's primary residence. It is assessed differently from a principal place of residence for tax, finance, and planning purposes.
How do you choose an investment property in Australia?
Start with strategy and finance, then select the market, suburb, and property in that order. Confirm borrowing capacity, define the portfolio role, research suburb fundamentals, assess the property against your brief, and complete full due diligence before exchanging contracts.
Is rental yield or capital growth more important?
It depends on the investor's goals, cash position, time horizon, and portfolio role. A cash-flow investor may prioritise yield; a growth-focused investor may accept a lower yield in exchange for stronger long-term demand drivers. Many investors need both to be sustainable across a full holding period.
How much deposit do you need for an investment property?
Deposit requirements vary by lender, borrower profile, loan structure, and purchase costs. There is no single universal figure. Speak with a licensed mortgage broker to confirm the deposit, costs, and buffer required for your specific situation before committing to a purchase.
What costs should you budget for when buying an investment property?
Budget for upfront costs including deposit, transfer duty, conveyancing, inspections, and lender fees. Ongoing costs include loan repayments, property management, insurance, council rates, land tax, maintenance, and vacancy allowances. Exit costs include capital gains tax and selling agent fees at disposal.
How do you research the best suburbs to invest in Australia?
Use evidence triangulation rather than static suburb rankings. Assess at least one demand signal (employment, population, rental demand), one supply signal (new development, planning changes), and one risk signal (flood, bushfire, vacancy, or concentration risk) before shortlisting a suburb. The ABS Census area search is a reliable starting point for suburb-level characteristics.
What due diligence should you do before buying an investment property?
Complete an independent building and pest inspection, contract and title review by a conveyancer or solicitor, strata or body corporate report for units and townhouses, rental assessment, comparable-sales review, hazard and planning check, and a serviceability review with your broker.
Is negative gearing suitable for every investor?
No. Negative gearing may allow eligible investors to claim rental losses against assessable income, but whether it is appropriate depends on personal income, loan structure, tax position, and current ATO rules. Confirm your position with a registered tax professional before structuring a purchase around a negative gearing outcome.
When does a buyers agent make sense for an investment purchase?
A buyers agent may suit investors who need help with strategy, suburb research, sourcing, analysis, negotiation, or settlement coordination. It is not essential for every buyer. Self-directed investors with time, market knowledge, and process confidence can proceed independently.
What should you ask a buyers agent before hiring them?
Ask about service scope, fees, how conflicts of interest are managed, which locations they cover, what evidence they use for suburb selection, how due diligence is coordinated, and what responsibilities remain yours. A credible buyers agent should answer all of these directly.
Make the next investment property decision with a clear brief
The most useful investment property decision is not finding a popular suburb. It is sequencing the decision correctly: define the property's role in the portfolio, confirm the finance and holding-cost limits, and then select the market, suburb, and property that fit those constraints.
This article is general information only and does not constitute personal financial, legal, or tax advice. Finance, tax, legal, insurance, and inspection decisions should be verified with the relevant licensed professional for your individual circumstances.
If you are ready to move from research to a clear strategy, map out your next property move with Buyers Agency Australia investment guidance before you start searching. To speak directly with the team, contact the team and outline your goals.
 General
Learn how to buy an investment property in Australia, from strategy and suburb research to finance, due diligence,...
A Sydney buyers agent represents the purchaser through property search, assessment, negotiation, auction bidding and settlement coordination. In New South Wales, a buyers agent must hold a real estate agent licence or work under a licensed real estate agent. Buyers Agency Australia applies this buyer-side process to strategy-led investment purchases, with Dragan Dimovski and the team supporting Sydney and national buying decisions. Every purchase is treated as one step in a broader portfolio plan, not simply an access event.
Buying property in Sydney is rarely a single decision. You may be comparing suburbs after work, preparing for an auction you have never bid at before, trying to buy from interstate without taking a week off, or working out how one purchase connects to the next one in your portfolio.
Choosing buyer-side representation is not only about finding listings. It is about deciding whether a service adds value at the strategy, assessment, negotiation, and execution stages of a major financial transaction. That distinction matters before you sign any agreement.
The Sydney property market is one of Australia's most active, with Greater Sydney recording population growth of 75,200 people in the year to June 2025, according to the Australian Bureau of Statistics. That sustained demand shapes competition at every price point and across every transaction type.
This guide explains what a buyers agent does, who benefits from the service, how fees work, what the process looks like, and how to evaluate buyer-side expertise before committing. For investors and buyers seeking strategic property investment support, the sections below provide a clear decision framework.
Service and regulatory references checked August 2026.
What is a buyers agent in Sydney?
A buyers agent, also called a buyers advocate, is a licensed property professional who acts exclusively for the purchaser during a property transaction. According to NSW Government guidance on using an agent to buy property, a buyers agent can search, assess, inspect, negotiate and coordinate a purchase through to settlement on behalf of the buyer.
The role is distinct from a selling agent, who is engaged by and legally obligated to the vendor. A buyers advocate in New South Wales works solely in the purchaser's interest, from the initial brief through to final settlement.
Representation has value before the search begins. The buyer brief and acquisition strategy determine which properties should be shortlisted, which should be rejected, and which markets align with the buyer's goals.
How buyer-side representation differs from a selling agent's role
| |
Buyers Agent |
Selling Agent |
| Who they represent |
The purchaser |
The vendor |
| Primary obligation |
Buyer's interests and objectives |
Achieving the best outcome for the seller |
| Advice provided |
Search, assessment, negotiation, settlement support |
Marketing, price negotiation, vendor guidance |
| Fee paid by |
Buyer (fixed fee or percentage) |
Vendor (commission on sale) |
| Conflict of interest |
Minimal when buyer-only practice |
May conflict with buyer's price objective |

What licensing means for a Sydney buyers agent
In NSW, operating as a buyers agent requires holding a real estate agent licence or working under a licensed real estate agent. NSW Fair Trading sets out the licence classes and requirements applicable to property professionals, including those who act for purchasers.
Readers can verify that an agent or agency holds a current, valid licence through NSW Fair Trading or Service NSW before engaging their services. Buyers Agency Australia displays its corporation licence number on its homepage, with Dragan Dimovski identified as Class 1 Licensee. Confirm that those details remain current before proceeding.
What does a Sydney buyers agent actually do?
The service scope can vary by engagement type, but the NSW Government's guidance on buyer-side representation outlines a consistent set of tasks a buyers agent can perform on behalf of a purchaser.
| Task |
What the buyers agent does |
| Buyer strategy |
Translates goals, budget and timeline into a clear acquisition brief |
| Property search |
Identifies on-market, pre-market and off-market opportunities matching the brief |
| Inspections |
Attends and assesses properties on the buyer's behalf |
| Market analysis |
Reviews comparable sales and assesses fair market value |
| Due diligence coordination |
Facilitates building, pest, strata and contract checks with the relevant specialists |
| Negotiation |
Manages price and contract negotiations with the selling agent or vendor |
| Auction bidding |
Registers and bids at auction under authority from the buyer |
| Settlement support |
Coordinates with the buyer's solicitor or conveyancer through to settlement |
For investment property guidance the scope also typically includes portfolio context, suburb selection logic, and asset-fit assessment.
Important boundaries apply. A buyers agent does not replace a solicitor or conveyancer, who manages legal contract review and the formal conveyancing process. Mortgage broking, building inspection, pest inspection, accounting, financial planning, and tax advice each remain with the qualified specialist holding the relevant authority.
Strategy, search and property assessment
The buyer brief defines what success looks like before a single property is inspected. It captures the buyer's budget, finance position, location preferences, property type, capital growth objective, cash-flow tolerance, and time horizon.
Search activity is shaped entirely by that brief. Properties that do not fit the strategy, borrowing capacity, or next acquisition plan are rejected, not presented. This is where buyer-side representation adds structure that a self-directed search rarely replicates consistently.
Valuation assessment uses comparable sales, condition analysis, and local market context to help the buyer form an independent view of fair value, separate from the vendor's asking price.
Negotiation, auction bidding and settlement support
In private treaty transactions, NSW Government guidance on making an offer describes the standard offer and cooling-off process. A private treaty purchase in NSW typically carries a five-business-day cooling-off period, but exceptions apply. Confirm your specific contract terms with a solicitor or conveyancer.
At auction, the rules differ significantly. NSW Government auction guidance states that buyers who sign the contract at auction pay the deposit on the spot and have no cooling-off period. Contract review before bidding is strongly recommended.

A buyers agent can register and bid at auction under authority from the buyer. Settlement coordination involves liaising with the buyer's appointed legal professional, broker, and other parties, but does not constitute legal representation.
Who should use a buyers agent in Sydney?
The service is not a universal fit. Its value depends on the buyer's time, experience, location, and the complexity of the transaction.
| Buyer type |
Likely problem |
Possible value |
Honest limitation |
| Property investors |
Aligning asset choice with portfolio strategy |
Brief-to-settlement support, suburb selection, asset assessment |
Does not guarantee growth, yield, or outperformance |
| Interstate buyers |
No local access for inspections or auctions |
Remote representation and on-the-ground assessment |
Service area coverage must be confirmed before engaging |
| Time-poor professionals |
Cannot inspect or bid consistently |
Handles search, inspections, and auction representation |
Requires clear communication of brief and priorities |
| First-time investors |
Uncertainty about market, process, and negotiation |
Process guidance, comparable sales review, due diligence coordination |
Legal, tax, and finance advice must come from qualified specialists |
| Strategic owner-occupiers |
Complex requirements, competitive market |
Negotiation, auction support, assessment depth |
Best suited where the buyer has a clear brief rather than a vague wish list |
| Confident local buyers |
Already experienced, locally connected, time-flexible |
May not need full representation |
Self-directed purchase may be more cost-effective for experienced buyers |
If you are weighing up whether buyer-side support suits your situation, book a free strategy session with Buyers Agency Australia to talk through your goals before committing to any engagement.
How a buyers agent helps Sydney property investors choose an asset
The most useful Sydney acquisition is not simply the one that becomes available first or carries an off-market label. It is the property that fits the investor's portfolio strategy, borrowing position, cash-flow tolerance, and next purchase plan.
A well-structured buyer-side process for investors moves through four stages.
Stage 1: Portfolio objective. Before selecting a market, the question is what role this property plays in the investor's broader plan. Is it a cash-flow asset, a capital growth position, or a bridging step toward the next purchase? That objective shapes everything else.
Stage 2: Market selection. Suburb selection should precede property enthusiasm, not follow it. The right suburb for one investor's brief may be wrong for another's, even at the same price point. A credible property investment strategy process uses supply, demand, infrastructure context, and rental fundamentals to narrow the field, rather than defaulting to popular opinion.
Stage 3: Asset assessment. Once a suburb shortlist is confirmed, individual properties are assessed against comparable sales, condition, layout, land component, and fit with the investor's cash-flow and depreciation position. Data-led market selection helps investors avoid buying the wrong asset in the right area.
Stage 4: Risk review. Before an offer is made, the borrowing impact of this purchase on the next acquisition, the cash-flow position under current lending conditions, and any planning or title risks need to be confirmed. The RBA cash rate target currently sits at 4.35% (effective 17 June 2026, source: RBA), which directly affects serviceability calculations and the cost of holding an investment property.
How suburb and property selection should connect to portfolio strategy
A property that suits a buyer's emotional preference but strains their borrowing capacity for the next two years is a portfolio risk, not just a personal decision. The asset should fit the investor's current finance position, serviceability buffer, cash-flow tolerance, and time horizon.
Sequencing matters too. Buying the wrong asset now can delay or block the next acquisition. A buyers agent working within a portfolio-planning lens should advise on the downstream effects of this purchase, not only its standalone characteristics.
What due diligence should cover before an offer
Properly conducted investment property due diligence covers several distinct areas before any offer is made or contract is exchanged.
- Comparable sales within a tightly defined comparable set, not broad suburb averages
- Building and pest inspection by a qualified inspector
- Strata or title review where applicable, including levy arrears and special levies
- Contract review by a solicitor or conveyancer before exchange
- Flood, bushfire, or planning overlay checks relevant to the specific property
- Independent financial and tax advice on the suitability of the asset for the investor's structure
Coordinating these checks is part of a full-service engagement. But the buyer remains responsible for instructing and paying each specialist.
How do off-market and pre-market properties in Sydney work?
Off-market and pre-market property refers to property that has not been listed publicly through a portal or campaign. Access generally comes through one of three pathways: direct relationships between buyers agents and selling agents, conversations with owners who are considering selling, or buyer networks where upcoming listings are shared early.
Access through these channels is real, but it is not automatic, unlimited, or guaranteed. The availability, quality, and price of off-market opportunities vary considerably.
What off-market does not mean:
| Common assumption |
Reality |
| Off-market means cheaper |
Price is set by the vendor, not the channel. Off-market does not imply a discount. |
| Off-market means less competition |
Other buyers agents may be presenting the same property to multiple clients. |
| Off-market means better quality |
Quality depends on the asset and the brief, not the listing status. |
| Off-market guarantees a good outcome |
Due diligence, assessment, and negotiation are still required regardless of how a property surfaces. |
A buyers agent cannot guarantee access to off-market property in Sydney, and any claim otherwise should be treated with caution. What access can provide is an earlier conversation with the vendor, which may create a negotiating context before the property reaches the open market.
Before any off-market offer is made, investment property due diligence should be conducted with the same rigour applied to a publicly listed property.
How much does a buyers agent cost in Sydney?
Buyers agent fees in Sydney are structured in two broad ways: fixed fees and percentage-based fees. Fixed fees are set at the start of the engagement and remain the same regardless of the purchase price. Percentage-based fees are calculated as a proportion of the final purchase price and therefore scale with the transaction value.
Some agents offer an auction-only or negotiation-only service at a reduced scope and fee. Others include the full engagement from brief through to settlement.
Buyers Agency Australia's current homepage describes tailored fixed-fee pricing, with fees confirmed after an initial discovery call based on the client's goals and transaction complexity. No universal dollar amount is published publicly, and no third-party range is used here as a substitute for the actual quoted fee.
What should be included in a buyers agent fee proposal?
When reviewing any fee proposal, confirm each of the following in writing before signing:
| Item |
What to check |
| Strategy and brief development |
Is initial strategy included or charged separately? |
| Property search |
Is ongoing active search included for the full engagement period? |
| Inspections and reports |
Are property inspection visits and written reports included? |
| Negotiation |
Is private treaty negotiation part of the core fee? |
| Auction bidding |
Is auction representation included, or is it an additional charge? |
| Due diligence coordination |
Does the agent coordinate specialist checks, or is that out of scope? |
| Settlement support |
Is post-exchange liaison with solicitors and conveyancers included? |
| GST treatment |
Is GST included in the quoted fee or added on top? |
| Retainer terms |
Is an upfront retainer required, and is it refundable if no property is secured? |
| Out-of-pocket expenses |
Are travel, reports, or third-party costs charged separately? |
| Cancellation terms |
What are the conditions if the buyer withdraws from the engagement? |

Compare the scope, not only the headline fee. A lower fee that excludes auction representation, due diligence coordination, or settlement support may cost more in total once those services are added separately.
Is a Sydney buyers agent worth the fee for an investor?
The honest answer is: it depends on your time, experience, location, and transaction complexity.
More likely to help when:
- You are buying interstate and cannot attend inspections or auctions reliably
- You are unfamiliar with NSW auction rules, contract terms, or Sydney suburb dynamics
- You are buying for investment and want portfolio-strategy alignment, not just property access
- Your time is constrained and inspection and research opportunities are genuinely limited
- The transaction involves complexity such as a competitive auction, strata due diligence, or off-market negotiation
Less likely to provide additional value when:
- You have strong local knowledge, time to search and inspect, and access to trusted advisers
- You are a confident negotiator with comparable-sales experience in the target suburb
- Your purchase is straightforward and your professional network covers legal, finance, and building checks
A buyers agent does not guarantee that the fee will be recovered in purchase savings, and any claim to the contrary should be viewed critically. The value is in expertise, process, and representation, not a guaranteed price reduction. For investors who want investment property guidance on whether buyer-side representation fits their situation, an initial strategy conversation is a practical first step.
The Sydney buyers agent process from brief to settlement
The investment property buying process follows a structured sequence from initial discovery through to post-settlement. Here is how a full-service engagement typically unfolds.

- Discovery call. Buyer and agent discuss goals, budget, timeline, finance position, and investment objectives. The buyer decides whether the service and scope are the right fit.
- Buyer brief. A formal brief captures the property type, location parameters, price range, must-haves, and deal-breakers. This brief drives every subsequent decision.
- Strategy development. The agent develops an acquisition strategy covering target suburbs, asset class, and portfolio sequencing. This stage may also involve confirming finance pre-approval with the buyer's broker.
- Active search. The agent searches on-market listings, contacts selling agents for pre-market and off-market opportunities, and applies the brief as a filter to reject unsuitable properties before presenting a shortlist.
- Assessment and decision gate. Each shortlisted property is inspected, assessed against comparables, and reviewed against the brief. The buyer then decides to proceed to an offer, renegotiate the terms of engagement, or walk away from that property. Not every shortlisted property should result in an offer.
- Negotiation or auction. For private treaty sales, the agent negotiates with the selling agent. For auctions, the agent registers and bids under authority. NSW auction rules require the contract to be signed and the deposit paid on the day, with no cooling-off period.
- Contract, due diligence and settlement. After exchange, the buyer's solicitor or conveyancer manages the formal legal process. The buyers agent coordinates building, pest, and strata checks where applicable and liaises with the relevant parties through to settlement.
For Sydney buyers agent support covering the full engagement from strategy to settlement, Buyers Agency Australia services buyers across Greater Sydney and nationally.
How do you choose a buyers agent in Sydney?
Not every person operating as a buyers agent in Sydney has the same scope, independence, or experience. Use the following questions before signing any agreement.
| Question |
Why it matters |
| Do you hold a current NSW real estate agent licence? |
Verify through NSW Fair Trading before proceeding. |
| Do you act exclusively for buyers, or do you also list properties for sale? |
Dual-role agents carry a higher risk of conflict of interest. |
| Who performs the actual search, inspections, and negotiation? |
Confirm whether the person you meet is the person doing the work. |
| Do you receive referral fees, commissions, or benefits from selling agents or developers? |
Any financial relationship with the selling side is a conflict that should be disclosed. |
| What is your fee structure, and what does it include? |
Confirm inclusions, GST, retainer terms, cancellation policy, and out-of-pocket costs in writing. |
| Can you show evidence of recent comparable purchases in my target area? |
Experience in the target suburb type matters more than general market experience. |
| How do you assess fair market value? |
Ask for the methodology, not just a general answer. |
| What professional referrals can you make for legal, finance, and building advice? |
A good buyers agent works within a professional network, not as a one-person operation. |
| What will you advise me NOT to buy, and why? |
This question tests genuine independence better than asking only about access or network size. |
| What are the service boundaries, and when does my responsibility begin? |
Understand exactly where the buyers agent's role ends and your solicitor's role begins. |
Why choose Buyers Agency Australia for Sydney property buying?
This section explains the approach of Buyers Agency Australia, the business offering the buyer-side service described in this guide.
Buyers Agency Australia takes a strategy-to-settlement approach to buyer representation, with a focus on investment property acquisition and portfolio planning rather than simply accessing listings. The service is built around a defined acquisition process: understanding the investor's objectives, selecting the right market, assessing individual assets against portfolio criteria, and executing the purchase with due diligence and negotiation discipline.
Dragan Dimovski, founder and senior buyers agent, brings more than 20 years of property investment experience to each engagement. The team operates across Greater Sydney and nationally, with a research capability that extends across major Australian markets.
The current homepage describes tailored fixed-fee pricing, data-informed suburb selection, off-market and pre-market access through established agent relationships, and end-to-end support from initial brief through to settlement. Fee details are confirmed after an initial discovery conversation based on the client's goals and complexity, not published as a universal rate.
Buyers Agency Australia positions buyer representation as a portfolio-planning service. That means the acquisition brief captures not only what to buy now, but how this purchase positions the investor for the next one.
When Buyers Agency Australia may not be the right fit
Buyer-side representation is not the right choice for every transaction. Consider a self-directed approach if:
- You have strong local Sydney knowledge, a reliable professional network, time to search and inspect, and experience negotiating property purchases.
- You prefer to manage the entire transaction yourself, from search through to settlement.
- Your requirements are straightforward and your legal, finance, and building advisers are already in place.
Regardless of how a property is purchased, legal advice comes from a solicitor or conveyancer, financial and tax advice from a qualified accountant or financial adviser, and building condition assessment from a licensed building inspector. A buyers agent does not replace any of those roles.
Sydney buyers agent FAQs
What is a buyers agent in Sydney?
A buyers agent is a licensed property professional who represents the purchaser through search, assessment, negotiation, auction bidding, and settlement coordination. In NSW, they must hold a real estate agent licence or work under a licensed real estate agent.
What does a Sydney buyers agent do?
A Sydney buyers agent searches for properties, inspects them, assesses market value, coordinates due diligence, negotiates with the selling agent, bids at auction, and supports the buyer through to settlement. The exact scope depends on the engagement agreed in the service agreement.
Is a buyers agent worth it in Sydney?
It depends on your time, experience, location, and transaction complexity. Interstate buyers, time-poor investors, and buyers unfamiliar with NSW auction rules often find the most value. Confident local buyers with strong networks may not need full representation.
How much does a buyers agent cost in Sydney?
Fees vary by scope and engagement type. Common models include fixed fees and percentage-based fees. Buyers Agency Australia's current public information describes tailored fixed-fee pricing confirmed after an initial discovery call, with no universal dollar amount published.
Can a buyers agent bid at auction in NSW?
Yes, where the service and licence arrangements permit. Under NSW auction rules, the successful bidder signs the contract and pays the deposit on the day with no cooling-off period. Always review the contract with a solicitor before authorising a bid.
Can a buyers agent find off-market property in Sydney?
A buyers agent may access off-market or pre-market opportunities through agent relationships and buyer networks, but access and outcomes are not guaranteed. Off-market does not automatically mean cheaper, less competitive, or better suited to the buyer's strategy.
Can an interstate buyer use a Sydney buyers agent?
Yes, if the service covers the relevant area and the buyer brief can be managed remotely. Interstate buyers are among those who often benefit most from on-the-ground representation during inspections, negotiations, and auctions.
Does a buyers agent provide legal or tax advice?
No. A buyers agent does not provide legal, tax, financial planning, or mortgage advice unless they separately hold the relevant professional authority. Use a solicitor or conveyancer for legal matters, an accountant for tax, and a licensed mortgage broker for finance.
What should I ask before hiring a Sydney buyers agent?
Ask about their NSW licence and verify it through NSW Fair Trading, confirm they act exclusively for buyers, clarify fee structure and inclusions, ask how they handle conflicts, request examples of recent comparable purchases, and confirm which professional tasks fall outside their scope.
Next steps for choosing buyer-side support in Sydney
Before engaging any buyers agent in Sydney, work through this checklist.
- Confirm your finance pre-approval is in place or close to being confirmed
- Define your acquisition brief: property type, location, budget, hold period, and portfolio objective
- Verify the agent's NSW licence through NSW Fair Trading or Service NSW
- Confirm the agent acts exclusively for buyers and discloses any referral relationships
- Review the fee proposal in full, including GST, retainer, cancellation, and inclusions
- Ask what properties they would advise against and why
- Confirm which tasks sit with your solicitor, conveyancer, broker, and building inspector
- Understand transfer duty obligations for your specific transaction type through Revenue NSW

If you are ready to talk through your Sydney property goals, Contact us for a free strategy session with Buyers Agency Australia. For direct enquiries, contact the team to discuss your brief and next steps.
This guide explains the approach of Buyers Agency Australia, the business offering the buyer-side service. It is general information only and does not constitute legal, financial, tax, or investment advice. Consult qualified Australian professionals for advice specific to your circumstances.
 General
Learn what a Sydney buyers agent does, how the process works, what fees cover, and how to choose...
No. Buy-and-hold property investing is not automatically dead in Australia. It becomes risky when investors treat time as a substitute for asset selection, cash-flow modelling, debt management, and due diligence. The strategy can still suit investors with a long-term horizon who buy a property with durable demand and can hold through changing market conditions.
Open any property forum right now and you will find investors questioning whether long-term ownership still makes sense. Higher borrowing costs, tighter lending conditions, and rising ownership expenses have made the numbers harder to stack. Some investors have concluded the strategy is finished.
The more useful question is not whether buy-and-hold has died, but whether the property, the debt structure, and the holding plan fit the investor's actual circumstances. A poor asset does not improve with age, and a sound strategy applied to the wrong property will still produce a poor result.
This guide separates strategy risk from asset risk and offers a practical framework for Australian investors weighing up long-term acquisition decisions. Any rate, lending, tax, or market claims in this article are tied to the specific sources and reference periods noted throughout. This guide is general information only and is not personal financial, tax, legal, lending, or investment advice.
Is buy-and-hold property investing really dead?
No. The strategy has not become obsolete, but it has become less forgiving of passive buying.
Buy-and-hold investing works on the premise that a well-selected property, held through different market conditions, can deliver rental income, potential capital growth, and progressive debt reduction over time. ASIC Moneysmart notes that property investment carries risks including vacancy, interest rate changes, leverage, and concentration risk and that investors need to consider their goals and risk tolerance before acting.
What has changed is the margin for error. When borrowing costs were lower and rental yields were thin, a mediocre asset in a reasonable location could still produce a serviceable outcome. That buffer has narrowed. Investors who buy without evidence-based asset selection, without realistic cash-flow assumptions, and without a debt structure they can sustain are now exposed more quickly to the consequences of those decisions.
The strategy is conditional, not automatic. Buyers Agency Australia exists precisely for the investor who wants to approach that condition with discipline rather than hope.
What buy-and-hold property investing actually involves
Buy-and-hold is an acquisition strategy where an investor purchases a residential property, holds it through property market cycles, collects rental income, and relies on long-term asset appreciation to build equity.
In practice, it involves selecting a location and property type, arranging suitable finance, settling the purchase, securing a tenant, managing the property over time, and periodically reviewing the asset against the investor's broader portfolio goals. The active work happens at the front end. The discipline required after purchase is ongoing.
The three return drivers investors need to understand
A long-term investment property can generate value through three mechanisms, though none of them are guaranteed.

| Return driver |
What it means |
What affects it |
| Rental income |
Regular income from tenants |
Vacancy, market rents, property type, location |
| Capital growth |
Increase in property value over time |
Location quality, demand, supply, market cycles |
| Debt reduction |
Loan principal decreases as repayments are made |
Loan structure, repayment type, interest rate |
Rental income supports cash flow and helps service the loan. Capital growth builds equity over time. Debt reduction improves the net position as the loan balance falls. Tax outcomes, including treatment of deductions and capital gains, are personal and depend on the investor's circumstances and current law. Consult the ATO's rental property guidance and seek qualified tax advice for your situation.
Why buy-and-hold is not the same as buy-and-forget
The term long-term holding can create a false impression that the strategy is low-maintenance. It is not.
A buy-and-hold property still requires periodic cash-flow reviews, maintenance planning, insurance checks, finance reviews as rates or loan terms change, tenant management, and portfolio reassessment as the investor's goals or borrowing capacity shifts. Properties in poorly maintained condition or with deteriorating fundamentals do not recover by themselves. The holding period is a feature of the strategy, not a repair mechanism.
Why some investors believe buy-and-hold no longer works
The concern is understandable. A combination of higher financing costs, tighter lending conditions, and stretched cash flows has made the strategy feel broken for many investors. The real issue is that conditions have removed the buffer that once masked poor decisions.
How interest rates and borrowing capacity change the equation
The RBA cash rate target was set at 4.35% effective 17 June 2026, following three increases in 2026, as recorded on the RBA cash-rate target page. Higher rates increase repayment obligations on variable loans and reduce the borrowing capacity that determines how much an investor can finance.
APRA introduced a debt-to-income lending limit effective from 1 February 2026, as confirmed by APRA's announcement. Under this measure, lenders can extend no more than 20% of new residential mortgage lending to borrowers with a debt-to-income ratio of six times or more. This applies separately to investor and owner-occupier portfolios. The measure does not ban high-DTI loans but limits their frequency, which can affect portfolio investors seeking to add further properties.

Personal borrowing capacity still depends on individual income, expenses, existing debts, lender assessment, and loan structure. Seeking guidance on property strategy during rate changes from an experienced adviser is worthwhile before making any acquisition decision.
Why cash flow pressure makes a good strategy feel broken
Holding costs extend well beyond mortgage repayments. They include council rates, water rates, landlord insurance, property management fees, routine maintenance, periodic repairs, and body corporate fees for strata properties. Add vacancy periods, where the mortgage runs without rental income, and the cash-flow position can tighten significantly.
Borrowing to invest increases both potential returns and potential losses, and interest and repayments remain payable regardless of whether the property generates rental income during a given period. An investor who has not stress-tested their cash-flow position against a realistic vacancy allowance and a rate movement scenario is exposed to exactly that risk.
The issue is rarely the buy-and-hold strategy itself. It is usually an asset that was purchased without a clear understanding of what it would cost to hold.
How tax and policy headlines can distort investment decisions
Negative gearing, capital gains tax concessions, and possible policy changes attract significant media attention. They can push investors toward decisions driven by tax considerations rather than asset quality.
Tax is one input into the overall investment picture, not the investment thesis. An asset that performs poorly as a property does not become a sound long-term hold because of its tax treatment. The ATO provides clear guidance on rental income and eligible deductions, and investors should obtain personal tax advice from a qualified accountant before factoring tax outcomes into an acquisition decision.
What actually makes a buy-and-hold property fail?
This is the question that gets less attention than it deserves. Strategy failure and asset failure are not the same thing, and the difference matters enormously over a long hold.

A sound strategy applied to the wrong property will underperform. A poor strategy applied to a strong property may still produce a reasonable outcome by accident. The more useful question is not whether buy-and-hold works, but whether the specific asset supports a long holding period.
| Failure cause |
Why it matters |
What to check |
| Weak local demand |
Low tenant interest and slow resale depth |
Employment base, population trend, liveability |
| Oversupply |
Vacancy and rent pressure from competing stock |
Building approvals, new development pipeline |
| Poor property quality |
Higher maintenance cost, low owner-occupier appeal |
Building and pest inspection, construction type |
| Overpayment at entry |
Compressed equity and reduced sale options |
Comparable sales, independent valuation |
| Single-industry exposure |
Rent and value vulnerability if one employer exits |
Diversity of local employers and economic activity |
| Forced selling |
Exit at the wrong point in the cycle |
Cash-flow buffer, liquidity outside the property |
Location and supply risk
Location affects long-term performance through employment access, population growth, transport infrastructure, amenities, and planning controls. A location with a single dominant employer, limited population growth, or unconstrained competing supply carries structural risk that a long holding period cannot resolve.
ABS national and state population data provides context on population trends, but population growth alone does not determine property performance. It is the interaction between demand and supply that creates or erodes value over time.
ABS Building Approvals data can indicate future housing supply trends, but approvals are not completions. A suburb with strong approvals figures may face more rental competition in two to three years if a significant portion of those dwellings are completed and occupied. Distinguishing approved, under construction, completed, and available stock matters when assessing supply risk.
Property selection and owner-occupier appeal
A high rental yield and a durable long-term asset are not the same thing. Properties with strong owner-occupier appeal tend to hold resale depth across different market conditions because the buyer pool is wider. Properties targeting a narrow tenant segment may generate acceptable income when occupied but struggle to attract buyers at resale or tenants in softer markets.
Broad appeal, practical layouts, maintainable construction, and scarcity characteristics relative to the local market all contribute to resilience over a holding period that may extend beyond a decade.
The cost of paying too much at the beginning
Purchase price sets the starting equity position, the loan-to-value ratio, and the holding cost base for the entire period. Comparable sales analysis, an independent valuation, and disciplined negotiation are not optional extras in a long-term hold strategy. They are the most direct way to reduce avoidable entry-point risk.
Overpayment at the start can take years to recover through capital growth, during which the investor carries a higher debt-to-equity position with less flexibility to sell if circumstances change. Understanding strategy before suburb selection is one of the reasons disciplined investors do their planning work before committing to a market.
When can buy-and-hold still make strategic sense?
Buy-and-hold is not a suitable strategy for every investor or every property. But for the investor, asset, and market conditions described below, it can still represent a sound long-term approach.
Investor conditions that support a long holding period
The investor's personal position matters as much as the property itself. Conditions that tend to support a long hold include:
- Stable and sufficient income to service the loan alongside existing commitments
- Realistic borrowing capacity assessed against current serviceability standards
- Emergency liquidity outside the property, such that a job change or unexpected cost does not force an early sale
- Tolerance for periods of negative cash flow without financial distress
- A genuine long-term goal that the property is intended to support
- Willingness to review the asset and the portfolio at regular intervals
Property conditions that support long-term ownership
The asset itself needs to meet a threshold for long-term resilience. Conditions that can support continued ownership include credible and durable tenant demand, a constrained or manageable supply pipeline, established employment drivers, practical liveability for a broad tenant pool, quality construction with manageable ongoing maintenance, and a purchase price supported by comparable sales evidence.
Portfolio conditions that support another purchase
For investors considering a second or subsequent property, the existing portfolio structure matters. One investment property can affect future borrowing capacity. Concentration in a single asset type or location increases risk if that market softens. Debt structure, including interest-only versus principal and interest terms, affects both cash flow and equity build. Accessing property investment strategy guidance before adding another property can prevent sequencing decisions that limit future options.
If you are at the point of assessing whether the timing and asset are right for your situation, book a free strategy session to work through the specifics before committing.
Is buy-and-hold better than short-term property strategies?
Short-term strategies such as flipping, renovation, and property development can produce strong results in the right conditions. They are not universally superior or inferior to buy-and-hold. The appropriate choice depends on the investor's capital, expertise, time availability, risk tolerance, and financial goals.
| Strategy |
Time horizon |
Complexity |
Capital required |
Primary risk |
| Buy-and-hold |
Long-term (years to decades) |
Moderate at acquisition, lower ongoing |
Purchase price and holding costs |
Asset quality, cash flow, leverage |
| Flipping |
Short-term (weeks to months) |
High |
Purchase, renovation, transaction costs |
Market timing, renovation overruns, tax |
| Renovation and hold |
Medium to long-term |
High at execution stage |
Purchase plus renovation budget |
Cost overruns, disruption, limited upside |
| Development |
Medium-term (site to completion) |
Very high |
Land, construction, finance, approvals |
Planning risk, build cost, absorption risk |
| Market timing |
Variable |
High (information intensive) |
Variable |
Missing the entry point in either direction |
Buy-and-hold versus flipping
Flipping requires buying, improving, and selling a property within a short window, usually before a market shift or renovation cost overrun erodes the margin. Stamp duty, agent fees, holding costs, and capital gains tax treatment all reduce the realised gain. The strategy depends heavily on market conditions at the time of sale, which cannot be reliably predicted. For investors without deep renovation and project management experience, execution risk is high.
Buy-and-hold versus development or renovation
Development and renovation can create genuine value by transforming an asset. They require planning approvals, construction finance, contractor management, cost control, and a disciplined exit or hold plan. The returns when executed well can be material, but the failure modes, including cost overruns, approval delays, and adverse market moves during the construction period, are also significant. These strategies suit investors with relevant skills, professional networks, and capital reserves for contingencies.
Why market timing is not a complete strategy
Waiting for the optimal entry point is rational in theory and difficult in practice. Property markets move across different cycles in different cities and suburbs. Investors who delay indefinitely waiting for conditions to improve often miss periods of growth. Investors who buy without financial capacity or asset evidence take on a different set of risks. The practical alternative is to assess financial readiness, asset quality, and portfolio fit, and to act when all three criteria are met rather than when the headline environment feels comfortable.
How do I know if buy-and-hold suits my financial situation?
The answer depends on your goals, income, borrowing capacity, cash-flow tolerance, liquidity, existing portfolio, and time horizon. No single threshold applies to every investor.
Questions to answer before choosing the strategy
Work through these before committing to an acquisition intended for long-term ownership:
- What is this investment meant to achieve, and over what period?
- How much monthly shortfall can I sustain if the property runs at a loss for a period?
- What happens to my financial position if the property is vacant for 60 to 90 days?
- Do I have liquidity outside the property to cover unexpected costs?
- Is my borrowing capacity sufficient for this purchase without impairing future options?
- What would cause me to sell, and can I avoid that trigger for the intended holding period?
- Have I obtained independent advice on the tax, legal, and lending structure?
These questions do not require a qualified financial adviser to ask, but they do require honest answers. If the answers suggest thin margins, it is worth pausing before proceeding. Reviewing resources on how to build long-term property wealth can help frame the planning decision before the financial modelling begins.
How to stress-test the holding costs
A simple holding cost review should include the estimated mortgage repayment at the current applicable rate, a vacancy allowance reflecting local market conditions, property management fees, council and water rates, landlord insurance, maintenance and repair reserves, and body corporate fees where applicable. Tax outcomes should be modelled with a qualified accountant using the investor's personal income position, not a generic negative gearing assumption. The purpose is to understand the realistic annual shortfall or surplus, and whether it is sustainable.
What should you check before buying a long-term investment property?
A thorough pre-purchase process moves from suburb to property to finance and legal review. Every check has a purpose: either to confirm the case for proceeding, or to identify a condition that requires further review or a decision to pause.
Suburb and market checks
- Population and employment trend in the area (use ABS data as a starting point)
- Rental demand and current vacancy rate from a recognised property data provider
- Building approvals and development pipeline as an indicator of future supply
- Proximity to employment nodes, public transport, schools, and services
- Comparable rental evidence to test yield assumptions
- Planning controls and zoning to understand future land use around the property
Note that building approvals indicate future intent, not confirmed supply. ABS Building Approvals data should be read alongside completion and occupancy trends, not treated as a direct measure of competitive rental stock.
Property-level checks
Every long-term acquisition warrants a building and pest inspection, a contract and title review by a solicitor or conveyancer, and verification of any easements, encumbrances, or covenant conditions affecting the land. For strata properties, review the body corporate records, including meeting minutes, the maintenance fund balance, and any special levies. Confirm the rental evidence is comparable and current, not a best-case estimate. Check any applicable flood, bushfire, or coastal hazard mapping from the relevant state or local authority.
A comprehensive property investment due diligence checklist is a useful reference before engaging solicitors and inspectors.
Finance, tax, and ownership checks
The loan structure, ownership entity, and tax treatment should be reviewed by a qualified mortgage broker, accountant, and solicitor or conveyancer before settlement. Decisions about interest-only versus principal and interest loans, individual versus trust or company ownership, and negative gearing treatment each carry consequences that extend across the entire holding period. The ATO rental property guidance covers the general rules for declaring rental income and claiming eligible expenses, but personal outcomes depend on your individual tax position and must be confirmed by a registered tax adviser.
The role of professional property selection and due diligence
Buyer-side property advisory support is most valuable before the purchase is made. The decisions taken at acquisition, including asset selection, purchase price, due diligence, and ownership structure, affect the outcome for the entire holding period. Changing those decisions after settlement is expensive or impossible.
For investors who have the time, research capability, established professional advisers, and a clearly defined market, managing the acquisition process independently is a legitimate approach. Professional support is not mandatory, and no advisory relationship guarantees an outcome.
Where Dragan Dimovski and Buyers Agency Australia may add value
Dragan Dimovski brings more than 20 years of property experience to buyer-side advisory work. The approach at buyer-side property guidance centres on investment strategy, data-led suburb selection, independent property assessment, negotiation support, off-market property communication, and end-to-end support from planning through settlement.
For investors who are unsure whether a specific market or asset meets the selection criteria for a long-term hold, that research and assessment process can reduce the risk of an avoidable acquisition decision. For investors building a portfolio across multiple properties, the sequencing and debt structure decisions that come with each subsequent purchase are where strategic support can be most relevant.
Buyers Agency Australia provides buyer-side property advisory services. This article is general information and is not personal financial, tax, legal, lending, or investment advice.
When professional support may not be the right fit
Investors who have already identified their target market, have strong research skills and established professional relationships, and are comfortable conducting their own due diligence may prefer to manage the process themselves. Professional support adds most value when the investor is entering an unfamiliar market, is acquiring at a price point where negotiation and independent assessment carry material weight, or is building a portfolio where sequencing decisions affect future borrowing capacity.
Map out your next property move before deciding whether independent or professional-supported acquisition is the right approach for your next purchase.
A practical buy-and-hold checklist for Australian investors
Use this checklist before committing to any long-term acquisition. Each item has a purpose: confirm the evidence, or identify a reason to pause.

| Check |
What you are verifying |
Pause signal |
| Investment purpose and time horizon |
Why you are buying and how long you can genuinely hold |
Short time frame or uncertain goals |
| Borrowing capacity and serviceability |
Whether the loan is sustainable at current and stressed rates |
Capacity only works at the lowest possible rate |
| Cash-flow stress test |
Whether you can cover holding costs including vacancy |
Thin buffer with no liquidity outside the property |
| Suburb demand evidence |
Rental demand, vacancy, population, employment |
Single-employer dependence or falling population |
| Supply pipeline |
Building approvals and planned development in the area |
Significant competing supply within the holding period |
| Property condition |
Building and pest, strata records, maintenance obligations |
Major defects or deferred capital works |
| Title, planning, and legal review |
Contract, title, easements, zoning, hazards |
Unresolved encumbrances or hazard exposure |
| Rental evidence |
Comparable achieved rents, not asking rents |
Evidence is dated or based on new-build premiums |
| Comparable sales |
Purchase price relative to recent like-for-like sales |
Limited comparable sales or significant price premium |
| Tax and ownership structure |
Advice from accountant on entity, deductions, CGT |
No professional tax advice obtained before signing |
| Insurance |
Landlord insurance cover confirmed before settlement |
Property uninsurable or specialist cover required |
| Portfolio fit |
How this purchase affects future borrowing capacity |
Purchase removes capacity needed for existing commitments |
Frequently asked questions about buy-and-hold property investing
Is buy-and-hold property investing dead in Australia?
No, but it is not automatic or suitable for every investor. The strategy can still work when the asset is selected with evidence, the debt is serviceable, and the investor can hold through changing conditions.
How long should you hold an investment property?
There is no universal minimum. ASIC Moneysmart frames property as a long-term investment, and the appropriate period depends on personal goals, holding costs, finance structure, and market conditions. Align the holding period with your documented investment objectives.
Does buy-and-hold work when interest rates are high?
It can, provided the investor can sustain the holding costs and the asset has genuine long-term demand. The RBA cash-rate target stood at 4.35% from 17 June 2026, which affects repayments and serviceability assessments. Stress-testing at higher rates before purchasing is essential.
What makes a buy-and-hold property fail?
Weak local demand, oversupply, poor construction quality, overpayment at entry, unsuitable debt structure, or a forced sale at the wrong point in the cycle can each undermine the result. Strategy and asset risk are not the same problem.
Should I prioritise rental yield or capital growth?
The right balance depends on your cash-flow position, goals, borrowing capacity, and portfolio stage. A high-yield asset that lacks resale depth or demand durability is not automatically stronger than a moderate-yield property in a high-demand location. Neither is universally preferable.
Is negative gearing necessary for buy-and-hold investing?
No. Tax treatment is separate from the underlying asset decision. The ATO outlines the general rules for rental income and deductions, but tax outcomes depend on the investor's circumstances and must be assessed by a qualified tax adviser. Buying a property primarily for tax reasons without a sound underlying asset case carries its own risk.
Should I buy property now or wait?
The right timing depends on financial readiness and asset quality, not a prediction about market direction. Waiting indefinitely can mean missing periods of growth. Buying without the financial capacity to hold carries a different risk. The practical test is whether the investor, asset, and finance conditions are all met simultaneously.
What due diligence should I complete before buying?
Verify the suburb demand, supply pipeline, property condition, title, planning, rental evidence, comparable sales, finance structure, insurance, and tax position. Engage a solicitor or conveyancer, qualified building and pest inspector, mortgage broker, and accountant before settlement.
Do I need a buyer's agent for buy-and-hold investing?
No, it is not mandatory. Investors with strong research capability, established professional advisers, and a clearly defined target market can manage the process themselves. Professional support may reduce research burden and improve process discipline, particularly for unfamiliar markets or complex negotiations.
When is buy-and-hold not the right fit?
It may not suit investors with a short required time frame, fragile cash-flow position, insufficient liquidity outside the property, a need for near-term capital access, or an asset that lacks durable demand characteristics.
Final verdict: buy-and-hold is not dead, but passive investing is risky
The evidence across rate cycles, lending conditions, and property market data consistently shows that the strategy's outcome depends on what was bought, at what price, with what debt structure, and whether the investor could hold through difficulty. Time alone does not repair a poor asset selection or an unsustainable financial position.
Three decision positions apply to most investors considering a long-term acquisition:
Proceed when you have a long-term objective supported by evidence, realistic borrowing capacity at current rates, liquidity outside the property, manageable holding costs confirmed by stress-testing, and an asset selected through rigorous due diligence.
Pause when you are relying on optimistic rent assumptions, have a thin cash-flow buffer, have not completed independent due diligence, or are responding to fear of missing out rather than a documented investment plan.
Seek tailored advice when the decision involves significant personal finance complexity, cross-state considerations, portfolio restructuring, tax or legal uncertainties, or a price point where independent assessment materially affects the risk profile.
Buy-and-hold is not dead. Passive buying without evidence, strategy, or financial discipline is where the real risk lies. If you are ready to assess whether a long-term acquisition fits your goals and financial position, map out your next property move with a structured strategy conversation first.
For investors ready to take the next step, contact the team at Buyers Agency Australia to discuss how buyer-side property advisory support fits your acquisition goals.
 General
Is buy-and-hold property investing dead in Australia? Learn what still works, what fails, and how to assess the...
Yes, Brisbane can still suit a long-term property investment strategy in 2026, but it is not a blanket buy. ABS data confirms Brisbane added 58,200 people in 2024-25, while Cotality recorded annual dwelling-value growth of 17.4% to June 2026, with the median dwelling value reaching $1,118,306. Those demand signals sit alongside a cash rate of 4.35% (effective 17 June 2026), rising affordability pressure, flood exposure, and uneven supply across property types. Whether Brisbane fits your portfolio depends on finance readiness, suburb evidence, property quality, risk tolerance, and your ability to hold under realistic cost assumptions.
Brisbane still appears on most investors' shortlists, and the data gives reasonable grounds for that interest. But the entry price, loan assessment, and property-specific selection now carry more weight than broad market headlines alone.
The more useful question is not simply whether Brisbane is growing. It is whether a specific Brisbane property fits your budget, cash-flow tolerance, holding period, and next-purchase plan. Strategy-led property investing demands that level of precision before any purchase decision.
This guide works through the demand drivers, the real risks, a repeatable suburb framework, property-type considerations, due diligence essentials, and when buyer-side support may be worth exploring.
Brisbane property investment in 2026: the short answer
Is Brisbane still a good place to invest in property in 2026?
Brisbane remains one of Australia's more active property markets heading into the second half of 2026. Cotality's June 2026 data shows Brisbane dwelling values up 17.4% annually and 1.3% over the quarter, while the Brisbane LGA added more residents than any other local government area in the country in 2024-25, according to the ABS regional population release.
That combination of population growth and sustained value movement reflects real underlying demand. But it does not make every suburb, property type, or price point a sound investment. Median values above $1.1 million mean the margin for error on property selection, financing, and holding-cost assumptions is smaller than it was three years ago.
For long-term investors with finance in order and a clear portfolio role for the asset, Brisbane can still be worth serious consideration. For investors relying on optimistic rent, vacancy, or growth assumptions to make the numbers work, the risk profile has shifted materially.
What the current data can and cannot tell you
Citywide data is a starting point, not a purchase decision. Cotality's June 2026 figures cover Greater Brisbane as a geography, and the annual growth rate of 17.4% is a blended dwelling figure across houses and units in very different suburbs, price bands, and supply conditions.
Brisbane house values grew 16.8% annually to June 2026, reaching a median of $1,225,350. Unit values grew faster at 20.3% annually, reaching a median of $885,132. Both figures are useful as market context, not as suburb-level or property-level benchmarks.
The more important question is whether the suburb you are assessing has durable demand, manageable supply, and a specific property whose rent, comparable sales, flood status, and total costs make the purchase viable under conservative assumptions.
| Data point |
Source |
What it tells you |
What it does not tell you |
| Annual dwelling value growth 17.4% |
Cotality, June 2026 |
Market-wide value trend |
Suburb, property type, or specific asset performance |
| Brisbane LGA added 58,200 residents |
ABS, 2024-25 |
Population demand signal |
Whether that demand is near your target property |
| Cash rate 4.35% (effective 17 June 2026) |
RBA |
Current cost of debt |
Your personal borrowing capacity or holding cost |
| Median dwelling value $1,118,306 |
Cotality, June 2026 |
Market-level price context |
Fair value for any individual property |

What makes Brisbane attractive to property investors?
Population growth and housing demand
Greater Brisbane grew at 2.1% in 2024-25, the second-highest growth rate among Australian capital cities, according to ABS capital city population data. The Brisbane LGA alone added 21,464 residents in that period, the largest numerical addition of any local government area in Australia.
Net overseas migration remained the largest driver of that growth, accounting for 44,300 of Greater Brisbane's increase in 2023-24, with net internal migration contributing a further 15,600. This mix of overseas and interstate arrivals sustains rental demand across a broad range of dwelling types and locations.
Population growth does create housing need. But population growth alone does not determine whether a particular property is fairly priced or whether its rental income will cover your holding costs.
Employment, infrastructure, lifestyle and supply
Brisbane's employment base spans healthcare, construction, education, tourism, and professional services, with ongoing infrastructure investment across Cross River Rail (under construction) and Brisbane Metro adding to public transport access in key corridors. These projects may influence access, amenity, and employment proximity for properties near the affected corridors. They do not guarantee growth for any individual asset.
Queensland's relatively lower entry costs compared to Sydney and Melbourne continue to attract interstate buyers and investors, though Brisbane's median dwelling value has now crossed $1.1 million, which changes that affordability comparison materially.
New dwelling supply has not kept pace with population growth across established, well-located areas, which supports rental demand in those locations. In higher-density precincts, however, new apartment supply adds a different set of risks discussed below.
What tight rental conditions mean for investors
Rental demand across Greater Brisbane has remained firm, with vacancy conditions reported as tight in most independent rental datasets over recent quarters. Tight vacancy supports asking rents, which in turn affects gross rental yield calculations.
Gross rental yield is a useful comparison metric, but it is not cash flow. To understand what a property will actually cost you to hold each year, you need to subtract property management fees, council rates, water, insurance, body corporate levies where applicable, maintenance allowances, and a realistic vacancy buffer from gross rent. That net figure is the number that matters for serviceability, tax planning, and portfolio sequencing.
Brisbane rental yields vary significantly by suburb, property type, land size, condition, and price point. A credible yield estimate requires current, independent rental evidence for comparable properties in the same suburb, not a citywide average.
| Demand driver |
Observable evidence |
Investor implication |
| Population growth |
ABS: Brisbane LGA added 21,464 in 2024-25 |
Sustained housing need, not guaranteed capital growth |
| Rental vacancy |
Tight conditions across most established areas |
Supports asking rents; verify at suburb and property level |
| Infrastructure |
Cross River Rail under construction; Brisbane Metro active |
May improve access and amenity in specific corridors |
| New supply |
Strong pipeline in high-density precincts |
Greater risk for new apartments in those areas |
What are the biggest risks of investing in Brisbane property?
Affordability, interest rates and serviceability
The RBA cash rate sat at 4.35% as of 17 June 2026, following three consecutive increases in 2026. The next RBA decision is scheduled for 11 August 2026. Investor borrowing capacity has reduced materially from 2021 and 2022 levels, and APRA's serviceability settings require lenders to assess borrowers at a rate at least 3 percentage points above the loan rate, which restricts total borrowing capacity across many investor portfolios.
For existing property holders, higher debt costs have increased holding expenses even where rents have risen. Any acquisition modelled at current rent levels needs to be stress-tested at higher vacancy and higher maintenance cost assumptions before commitment.
Affordability is now a genuine constraint in Brisbane. An investment that only works under the most optimistic rent, rate, and vacancy scenario is carrying risk that the market conditions of 2023 may have obscured.
Flood, insurance, climate and planning exposure
Flood risk is one of the most underweighted variables in Brisbane investment decisions. Parts of Greater Brisbane have experienced repeated inundation events, and flood exposure affects not only the physical asset but also insurance availability, insurance premiums, development potential, future buyer appetite, and lender willingness to finance at standard terms.
The Brisbane City Council FloodWise Property Report provides address-level flood risk information including historical flooding, planning overlays, and flood planning levels. This check must be completed for every property under consideration, not estimated from suburb reputation or a general impression of the area.

Insurance premiums in flood-affected areas of Queensland have risen sharply in recent years. Obtain written insurer feedback on premium estimates and exclusions for any shortlisted property before signing a contract.
Supply, vacancy and market-cycle risk
Not all Brisbane property types face the same supply conditions. Established houses in well-located suburbs with limited development opportunities carry different supply dynamics from new apartments in high-density precincts, where settlement risk, oversupply, and valuation shortfalls at completion add layers of risk.
Market cycles also matter. Brisbane dwelling values decelerated in monthly terms through the second quarter of 2026, with monthly growth of 0.3% in June compared to 1.8% in March, per Cotality data. That moderation does not signal a downturn, but it does indicate the rate of price growth is slowing. Investors who purchased expecting recent monthly growth rates to continue indefinitely are carrying timing risk.
| Risk |
What to check |
Why it matters |
When to pause |
| Interest rates and serviceability |
RBA cash rate; APRA settings; lender assessment rate |
Higher rates reduce borrowing capacity and increase holding costs |
Numbers only work under optimistic rate assumptions |
| Flood and insurance |
BCC FloodWise Report; written insurer quote |
Affects premiums, development potential, and resale pool |
Uninsurable at standard premium, or flood overlay affects usage |
| New apartment supply |
Development pipeline for the suburb and precinct |
Can suppress rents and resale values for similar stock |
High concentration of competing new supply under construction |
| Market-cycle timing |
Dated comparable sales trend over 6 to 12 months |
Monthly growth deceleration changes short-term holding assumptions |
Only viable under peak-rate-of-growth assumptions |
How do you assess Brisbane suburbs for an investment property?
Start with strategy, budget and portfolio role
Before looking at any suburb, define what role this property is meant to play in your portfolio. Is it a cash-flow asset, a long-term capital-growth hold, or a stepping stone to a larger portfolio? Your answer changes which suburbs are even worth assessing.
Also establish your realistic holding period and your serviceability buffer after this purchase. The question to ask is whether the property still allows you to buy your next asset within your intended timeframe, after modelling realistic debt, rent, vacancy, and ownership costs. If buying in Brisbane now would block your next purchase for a decade, that is a material portfolio constraint regardless of the suburb's quality. For help building a tailored property investment strategy, it pays to work through these numbers before suburb selection begins.
Test demand, supply and access
- Population and employment: Is there a diversified employment base within reasonable commuting distance? Suburbs dependent on a single employer or single industry carry concentration risk.
- Transport and amenity: Confirm proximity to public transport, schools, retail, and healthcare using official maps, not marketing descriptions. Cross River Rail station locations are confirmed; check the official project pages for current delivery status.
- Development pipeline: Search the Brisbane City Council development applications portal for approved or pending medium and high-density approvals in the target suburb. High approval rates signal future supply competition for similar stock.
- Resale depth: Review how many comparable properties have sold in the suburb over the past 12 months. Low volume means less price discovery and potentially lower liquidity if you need to exit.
- Two-layer test: First assess whether the suburb has durable demand from owner-occupiers and tenants. Then assess whether your specific property type has demonstrable demand and resale appeal within that suburb.
For a detailed look at Brisbane suburbs for investment that pairs this kind of framework with current, dated evidence, treat any such list as a starting point for your own due diligence rather than a permanent ranking.
Validate rent, yield and comparable sales
Advertised rent is not achieved rent. Achieved rent reflects actual lease terms, any incentives offered, and current market depth. Request evidence of recent comparable leases, not asking prices on listing portals.
Calculate gross yield as annual achieved rent divided by purchase price. Then subtract all holding costs to arrive at net cash flow. That figure, modelled at a conservative vacancy rate of at least four to six weeks per year, is what you use to assess serviceability and portfolio impact.
Comparable sales must be current, comparable by property type, condition, land size, and location, and sourced from a dated dataset such as Cotality or PropTrack rather than from a selling agent's verbal estimate.
Check planning, flood and property-specific evidence
Every shortlisted property requires a zoning and overlay check against the Brisbane City Plan 2014, a FloodWise Property Report from Brisbane City Council, building and pest inspection reports from qualified professionals, and a conveyancer or solicitor review of the contract and title.
Do not proceed unconditionally until every material item has been resolved. Missing evidence on flood, planning overlays, building defects, or body corporate finances is a pause condition, not a minor detail.
Do Brisbane houses, units or townhouses suit different strategies?

Houses: land, tenant demand and capital requirements
Brisbane houses carry land content, which is the primary component of long-term value in most established locations. Owner-occupier demand in well-located suburbs provides a broader resale pool and tends to support price stability in downturns more than investment-heavy precincts.
The entry cost is higher: the Cotality June 2026 median Brisbane house value is $1,225,350. Holding costs are also higher in absolute terms, including council rates, insurance on a standalone dwelling, and maintenance on land and structure. The trade-off is less exposure to body corporate risk and new supply from apartment development.
Units: entry price, body corporate and supply risk
The critical distinction for Brisbane units is between established, well-located stock and new apartments in high-density precincts. These are not the same investment.
Established units with proven tenant demand, reasonable body corporate levies, and a healthy capital works fund can offer lower entry cost and competitive rental yields relative to purchase price. New apartments in precincts with a heavy development pipeline carry settlement risk, potential valuation shortfalls, and rental competition from similar new stock.
For any unit purchase, obtain at least two years of body corporate meeting minutes and the current capital works fund balance before signing. A low body corporate levy on a building with a depleted capital works fund signals a future special levy rather than a cost saving.
Townhouses: a middle ground, not an automatic compromise
Townhouses offer partial land content, typically under a strata or community title, with lower entry cost than houses in the same suburb. Tenant appeal is generally strong for families and professionals who want outdoor space without full house maintenance.
Assess the strata or community title costs, including levies, upcoming capital works, and any sinking fund shortfall, alongside the local resale buyer pool. In some Brisbane suburbs, townhouses compete with a large number of similar new townhouse completions, which can moderate achieved rents and resale values.
Questions to ask about any property type
- Who is the primary tenant for this property in this suburb, and what does independent rental evidence show for comparable stock?
- What does the development pipeline look like for similar property types within a two-kilometre radius?
- What are the full holding costs, including body corporate, insurance at an accurate premium, rates, maintenance allowance, and a vacancy buffer?
- Does the property carry any flood overlay, and have you obtained written insurer feedback?
- Does the resale buyer pool include owner-occupiers as well as investors?
- Does this purchase support or restrict your next portfolio decision?
| Property type |
Potential fit |
Main risk |
Required checks |
| House |
Long-term hold, owner-occupier-grade suburbs, land-content strategy |
Higher entry cost, holding costs, maintenance exposure |
Building and pest, flood, comparable sales, planning overlays |
| Established unit |
Cash-flow focus, lower entry, proven tenant demand |
Body corporate quality, capital works shortfall, supply in precinct |
Body corporate records, capital works fund, comparable rents and sales |
| New apartment |
Income from day one in some cases |
Settlement risk, valuation shortfall, supply competition |
Developer financials, comparable rental evidence, development pipeline |
| Townhouse |
Balance of yield and land content |
Strata costs, new townhouse competition, narrower resale pool |
Strata records, sinking fund, comparable sales, local supply pipeline |
What should investors check before buying in Brisbane?
Finance and total acquisition costs
The purchase price is one line in the budget. The full acquisition cost includes a deposit (typically 20% for an investment property to avoid lenders mortgage insurance, though this depends on lender policy and loan structure), Queensland transfer duty on the purchase price, legal and conveyancing costs, building and pest inspection fees, loan establishment costs, initial insurance premium, and a cash reserve for vacancy and early maintenance.
For detailed guidance on deposit and purchase cost planning, including how lenders assess investor borrowing capacity, work through the full cost schedule with a qualified mortgage broker before committing to a purchase price range.

Queensland transfer duty rates for investment properties differ from owner-occupier rates. There is no first home buyer concession available on investment properties. Confirm the applicable rate for your buyer status and purchase price using the Queensland Revenue Office's published duty calculator.
Building, pest, title, contract and body corporate
Building and pest inspections must be conducted by qualified, independent professionals with professional indemnity insurance. Do not rely on a vendor's inspection report. Request access before making an unconditional offer, or include a building and pest condition in the contract.
Your conveyancer or solicitor must review the title, any easements or encumbrances, the contract of sale, and for units and townhouses, body corporate records including meeting minutes, levies, insurance, and capital works fund position. These checks are not optional and are not tasks a buyers agent replaces.
Refer to our property due diligence checklist for a fuller treatment of the steps involved, alongside the Brisbane-specific checks below.
Rental, insurance, flood and planning checks
| Check |
Source |
Responsible professional |
Decision consequence if missing |
| Flood risk |
BCC FloodWise Property Report and Flood Awareness Map |
Buyer, with legal and insurer follow-up |
Cannot assess insurance cost, development potential, or resale pool |
| Insurance premium |
Written quote from insurer for that property |
Buyer and licensed insurer |
Cannot accurately model holding costs or net cash flow |
| Zoning and overlays |
Brisbane City Plan 2014 via Council's development portal |
Conveyancer or solicitor |
May not understand permitted uses, development restrictions, or change-of-use risk |
| Comparable rents |
Independent leasing agent evidence or dated rental dataset |
Buyer or buyers agent coordinator |
Yield calculation is based on an assumption, not evidence |
| Rental income and deduction rules |
ATO guidance |
Qualified accountant or tax adviser |
Tax treatment is misunderstood, affecting net return calculation |
When should you consider a Brisbane buyers agent?
A buyers agent operates exclusively on behalf of the buyer, not the vendor. That distinction matters most when the property you want to buy is being sold by an agent whose fee depends on achieving the highest price for their client, not yours.
What Buyers Agency Australia can help with
Buyers Agency Australia provides buyer-side property advisory services for Australian investors, with a national service footprint and specific support for Brisbane acquisitions. The team's approach is built around strategy alignment before suburb selection, data-led suburb research, property sourcing including selected off-market opportunities (off-market access is a sourcing channel, not evidence that a property is cheaper or safer), due diligence coordination, negotiation, and settlement support.
Dragan Dimovski, a property expert with 20+ years of experience, leads the advisory approach at Buyers Agency Australia. The firm's process is designed to reduce the search and negotiation burden for investors who want structured, evidence-based buyer-side representation rather than navigating the market independently.
For Brisbane buyers agent support that covers the full buying process from strategy through to settlement, the team can be engaged at different stages depending on how far along your planning is.
If you are still working out whether Brisbane suits your next investment, book a free strategy session to map out the decision before committing to a market or property type.
Buyers Agency Australia is the publisher and service provider discussed in this section. This article explains process fit, not guaranteed investment performance.
What a buyers agent cannot replace
A buyers agent does not replace a licensed mortgage broker (borrowing capacity and loan structure), a qualified accountant or tax adviser (tax treatment, depreciation, negative gearing, land tax), a solicitor or conveyancer (contract review, title, legal matters), a building and pest inspector (physical property condition), a licensed insurer (flood and property insurance), or a planning authority (zoning, overlays, development approvals).
Each of those professionals must be engaged separately, and their advice must inform your purchase decision independently.
When this approach is not the right fit
Buyers Agency Australia's buyer-side service is not the right fit for every investor. Investors without finance pre-approval or a clear deposit position are not yet at the property selection stage. Investors who need guaranteed returns or guaranteed growth will not find that here, because no credible advisory service can make that promise. Investors who prefer to manage the full research, negotiation, and settlement process independently may find the structure unnecessary for their approach.
Thinking through whether to buy in 2026 or hold off is a legitimate prior question, and it deserves an honest answer before engaging any service.
Frequently asked questions about Brisbane property investment in 2026
Is Brisbane still a good place to invest in property in 2026?
It can suit some long-term investors, but suitability depends on finance readiness, suburb evidence, property quality, and portfolio fit. No market condition removes the need for property-specific due diligence.
Is Brisbane property overpriced in 2026?
Affordability must be assessed against your income, debt cost, comparable rents, and holding period. The Cotality June 2026 median dwelling value of $1,118,306 is a market reference, not a fair-value judgement for any individual property.
What are the biggest risks of investing in Brisbane property?
The primary risks are higher borrowing costs and serviceability constraints, flood and insurance exposure, new apartment supply in high-density precincts, vacancy changes, and geographic concentration in a single market.
What rental yield can I expect from a Brisbane investment property?
Yield varies by suburb, property type, price, and current rent evidence. Gross yield is not cash flow. Calculate net yield after all holding costs and a realistic vacancy allowance before drawing conclusions.
What are the best Brisbane suburbs for investment?
There is no permanent best suburb. Suburbs that may suit a stated strategy require current evidence on demand, supply, flood status, comparable rents, and comparable sales. Use the framework in this guide and check the Brisbane suburbs for investment article for dated supporting research.
Should I buy a house, unit or townhouse in Brisbane?
The choice depends on your strategy, budget, land-content priority, body corporate tolerance, local supply conditions, and the resale buyer pool in the target suburb. There is no universal winner.
How much deposit do I need for a Brisbane investment property?
The amount depends on your lender's policy, loan structure, purchase price, and total acquisition costs including Queensland transfer duty. Most lenders require 20% to avoid lenders mortgage insurance on investment loans, but confirm your position with a qualified mortgage broker.
Should I buy Brisbane property now or wait?
Timing decisions should not rest on market forecasts alone. Test your finance, the quality of the property you can access, your risk tolerance, and your capacity to hold under conservative assumptions. Our guide on whether to buy in 2026 works through that decision in more detail.
How do I check flood risk before buying in Brisbane?
Use the Brisbane City Council Flood Awareness Map and request a FloodWise Property Report for the specific address. Then obtain written insurance feedback and legal advice on any planning overlays before proceeding.
Do I need a buyers agent to invest in Brisbane?
No. A buyers agent is not mandatory. It may be useful for investors who want structured, buyer-side research, sourcing, and negotiation support. It does not replace a mortgage broker, accountant, solicitor, building inspector, insurer, or planning authority.
This article provides general educational information about Brisbane property investment. It is not personal financial, tax, legal, lending, insurance, or planning advice. Consult qualified professionals for advice specific to your circumstances.
A practical Brisbane property investment decision checklist
A positive market trend does not make every Brisbane property a sound investment. Use this checklist to determine whether you are ready to proceed, need to pause, or should walk away from a specific purchase decision.

Go: all of the following apply
- Finance is pre-approved and serviceability confirmed at a stress-tested rate
- The suburb has verified, durable demand from both tenants and owner-occupiers
- The property has no material flood, planning, building, pest, or body corporate issue outstanding
- Comparable sales support the purchase price
- Independent rental evidence supports the yield calculation at a conservative vacancy rate
- The purchase supports, rather than restricts, your next portfolio decision
- Total acquisition costs including Queensland transfer duty and holding costs are modelled and affordable
Pause: one or more of the following apply
- Insurance, flood, body corporate, comparable sales, or serviceability has not been fully resolved
- The yield only works at asking rent with zero vacancy
- The development pipeline for comparable stock in the suburb is unclear
Walk away: any of the following apply
- The property only stacks up under optimistic rent, vacancy, rate, or growth assumptions
- The purchase compromises your ability to hold the asset or buy the next one
- Material due diligence items remain unresolved at exchange
If you want help working through this checklist against a real property or suburb, map out your next property move with the Buyers Agency Australia team before committing. For direct enquiries, contact the team to discuss your investment goals and timeline.
 General
Is Brisbane still a good place to invest in property in 2026? Review growth drivers, rental demand, risks,...
A 20% deposit is the common benchmark for an Australian investment property because it produces an 80% loan-to-value ratio (LVR) and often avoids lenders mortgage insurance (LMI). Some lenders may consider a lower deposit, but the investor may face LMI, a tighter serviceability assessment, and higher total borrowing costs. The real target is the deposit plus transfer duty, conveyancing, inspections, lender costs, and a cash buffer. Your income, existing debts, expenses, property valuation, and loan structure all matter as much as the deposit itself.
You have saved a deposit or built equity in an existing property. The question keeping you up at night is whether that amount is actually enough to get through settlement and come out the other side in a sound financial position.
The word “deposit” adds to the confusion because it means different things at different stages of a purchase. It can refer to the amount you hand over with an offer, the equity contribution a lender requires, or the full cash position needed to complete the transaction. Blurring those three meanings together is one of the most common deposit-planning mistakes investors make.
This guide separates each of those concepts, explains the key lending rules that shape your practical target, and shows what the real cash requirement looks like through three illustrative scenarios. For investors connecting these numbers to a broader plan, Buyers Agency Australia investment guidance provides strategy-led support from suburb selection through to settlement.
General information only. This guide does not account for your personal financial, tax, or legal circumstances. Consult a licensed mortgage broker, registered tax adviser, solicitor, or conveyancer before making any property or finance decisions.
How much deposit do you need for an investment property in Australia?
For most investment property loans in Australia, a 20% deposit is the most widely used benchmark because it targets an 80% LVR. At 80% LVR, many lenders do not require lenders mortgage insurance, and the borrowing assessment tends to be more straightforward. ASIC’s MoneySmart guidance identifies a 20% deposit as a common savings goal for property buyers.
That 20% figure is a benchmark, not a universal legal requirement. Some lenders may consider a lower deposit for investment loans, but the trade-offs include LMI, stricter serviceability tests, and potentially higher interest rates. Others may require more than 20% depending on the borrower’s profile, property type, and loan structure.
The most important distinction to grasp early is this: the deposit percentage your lender requires and the total cash you need at settlement are two very different numbers. A 20% deposit on a $700,000 property is $140,000. Add transfer duty, conveyancing, inspections, lender fees, and a cash buffer, and the actual cash requirement can be materially higher.
Why there is no single minimum deposit for every investor
The phrase “minimum deposit” sounds like a fixed rule. In practice, it is shaped by at least five different variables: lender policy, the borrower’s financial profile, the property type, the loan structure, and the relevant state or territory’s transaction costs.

Three concepts are frequently confused under the single word “deposit”:
| Term |
What it means |
Why it matters |
| Contract deposit |
The amount paid with an offer or at auction, usually 5% to 10% of the purchase price |
Does not represent the lender’s full equity requirement |
| Lender equity contribution |
The full equity position the lender expects, typically measured by LVR |
Determines whether LMI applies |
| Total settlement cash |
Deposit plus transfer duty, conveyancing, inspections, lender costs, and buffer |
The actual figure you need in your account |
A property valuation below the purchase price adds a further complication. If a lender values the property at less than what you agreed to pay, the LVR calculation uses the lower figure, which means you may need to contribute more cash to maintain the same LVR. A qualified mortgage broker can help you model these scenarios before you commit to a purchase.
The common deposit benchmarks for investment property loans
The table below sets out the four most commonly discussed deposit positions for investment property and the key trade-offs attached to each. All figures are illustrative and lender-specific. Verify any scenario with a current mortgage broker before relying on it.
| Deposit |
Indicative LVR |
Likely trade-off |
What to verify |
| 5% |
95% |
Not a standard investor pathway. The Australian Government 5% Deposit Scheme applies to eligible owner-occupiers only, not investment properties. Some specialist lenders may consider 95% LVR investor loans but at materially higher rates. |
Confirm availability and pricing with a lender or broker. |
| 10% |
90% |
May be considered by some lenders with LMI and stronger serviceability. Higher LMI cost. Stricter assessment is common. |
Confirm lender policy and LMI cost before proceeding. |
| 20% |
80% |
Common benchmark. Often avoids LMI. More lenders participate. |
Verify that transaction costs and a cash buffer are funded separately. |
| More than 20% |
Below 80% |
Lower debt, lower repayments, stronger cash-flow resilience. Capital used for the deposit is unavailable for other investments or emergencies. |
Assess opportunity cost against portfolio strategy. |
Can I buy an investment property with a 5% deposit?
In most practical scenarios, no. The Australian Government’s 5% Deposit Scheme is available to eligible owner-occupiers, not investors purchasing a rental property. While a small number of specialist lenders offer 95% LVR investment loans, these typically come with higher interest rates and strict eligibility criteria. This is not a pathway most investors should plan around without detailed advice from a current mortgage broker.

Can I buy an investment property with a 10% deposit?
Some lenders may consider a 10% deposit for an investment loan, but it generally involves LMI, tighter serviceability scrutiny, and potentially a higher interest rate. Availability is lender-specific, and the LMI cost at a 90% LVR is considerably higher than at an 85% LVR. If a 10% deposit is all that is available, speak with a broker about whether the total acquisition cost still makes financial sense.
Why 20% is often used as the practical benchmark
A 20% deposit produces an 80% LVR, which is where many mainstream lenders draw the line for requiring LMI. Below 80% LVR, the lending assessment is typically smoother, and more lenders participate competitively. It is worth noting that 20% covers only the lender’s equity requirement. Transfer duty, conveyancing, inspections, and other costs must be funded in addition to the deposit.
When a deposit larger than 20% may make sense
A larger deposit reduces borrowing, lowers monthly repayments, and can improve cash-flow resilience, which matters when vacancy periods or rate changes arise. The trade-off is opportunity cost: capital tied up in a single property is unavailable for other investments or as an emergency reserve. The right balance depends on your overall property investment strategy process and portfolio sequencing, not just the entry price.
What is the real cash amount needed at settlement?
This is where many first-time investors underestimate their cash requirement. The formula is straightforward:
Total cash target = Deposit + Transfer duty + Conveyancing + Inspections + Lender costs + Valuation fee + Insurance + Adjustments + Buyer-side fees + Emergency buffer
Which upfront costs should investors budget for?
Beyond the deposit, investors should budget for the following:
- Transfer duty (stamp duty): The most significant variable. Rates differ by state or territory, property value, property use, and buyer circumstances. In NSW, transfer duty is calculated on a sliding scale by Revenue NSW. In Victoria, the State Revenue Office Victoria publishes general rates that apply to investment purchases. Never apply one state’s rate to another state.
- Conveyancing or solicitor fees: Usually $1,500 to $3,000, depending on complexity and location.
- Building and pest inspection: Typically $400 to $800.
- Lender application and valuation fees: Vary by lender and loan product.
- Landlord insurance: Often required before or at settlement.
- Adjustments at settlement: Council rates, water rates, and body corporate fees may be apportioned.
- Emergency buffer: A reserve to cover unexpected repairs, vacancy periods, or changes in repayment obligations.

For a property in NSW, transfer duty alone can add tens of thousands of dollars to the cash requirement. Check the Revenue NSW transfer duty calculator and the relevant revenue office in your target state before finalising a budget.
Why the contract deposit is not the same as the full lender deposit
When you sign a contract or win at auction, you typically pay a contract deposit of 5% to 10% of the purchase price. That amount is not the same as the equity the lender requires. The lender will assess the full LVR based on the accepted property valuation and the total loan amount. You need the remaining equity and all purchase costs funded by settlement day, not just the contract deposit.
How lenders assess your deposit and borrowing capacity
A large deposit does not guarantee loan approval. Lenders assess your entire financial position, and the borrowing capacity for investment property depends on several interconnected factors.
What does borrowing capacity have to do with your deposit?
Serviceability is the lender’s test of whether you can afford the repayments. Under APRA’s residential mortgage lending standards, authorised deposit-taking institutions (ADIs) must assess a borrower’s ability to repay at the loan rate plus a buffer of at least 3 percentage points. As confirmed in APRA’s May 2026 macroprudential update, that buffer remains at 3 percentage points. If your income and existing commitments do not support the repayments at the assessed rate, no deposit size will change that outcome.

It is also worth noting that APRA introduced debt-to-income (DTI) limits from February 2026, requiring ADIs to limit new mortgage lending with a DTI ratio of six or more to 20% of all new lending. This affects investors with significant existing debt and can reduce available borrowing even when a deposit is ready.
How rental income and existing debt affect the assessment
Lenders may include a portion of the expected rental income in the serviceability calculation, but they typically apply their own assessment assumptions rather than the full market rent figure. Existing debts, credit card limits (even unused ones), and living-expense estimates all reduce the amount a lender will approve. A mortgage broker can run a current serviceability calculation across multiple lenders before you begin searching for a property. This is a useful step toward understanding how to invest in property in Australia with a realistic finance foundation.
Can I use equity instead of cash for the deposit?
Yes, usable equity in an existing property can contribute to an investment purchase. But equity is a secured borrowing mechanism, not free money. The lender assesses how much of your existing property value can be borrowed against, subject to valuation and serviceability.
A simple usable equity formula
The following is an illustrative estimate, not a lending approval:
Indicative usable equity = (Accepted property value x lender’s LVR limit) – Existing loan balance
Example (illustrative only, not a lender approval):
- Accepted property value: $900,000
- Lender’s LVR limit: 80%
- Maximum borrowable: $720,000
- Existing loan balance: $500,000
- Indicative usable equity: $220,000
That $220,000 could be accessed through a loan top-up or a separate equity loan, subject to valuation and full serviceability assessment. As Westpac’s investment property deposit guidance notes, a lender typically calculates usable equity based on borrowing against up to 80% of a property’s value, minus the existing loan balance.
What can go wrong when equity funds the deposit?
Several risks deserve attention before accessing equity:
- Valuation shortfall: The lender’s accepted value may be lower than your estimate, reducing available equity.
- Higher total debt: You now carry two loan facilities. Repayment pressure increases on both properties.
- Cross-collateralisation: Some lenders link both properties as security. This limits your flexibility to sell, refinance, or restructure later.
- Interest-rate risk: Rising rates affect both loans simultaneously.
- No cash buffer: Using every dollar of equity for the deposit leaves nothing for vacancy, repairs, or emergencies.
Discussing loan structure with a mortgage broker before accessing equity protects both your existing property and the new investment. Reviewing property investment fundamentals before committing to equity access helps frame the decision within a broader portfolio context.
What is lenders mortgage insurance and when might it apply?
Lenders mortgage insurance (LMI) is an insurance premium paid by the borrower to protect the lender if the borrower defaults and the property sale does not cover the outstanding loan. LMI does not protect the borrower.
LMI generally applies when a borrower’s LVR exceeds the lender’s preferred threshold, most commonly above 80%. The premium depends on the lender, the LVR, the loan amount, and the borrower’s profile. Investment property LMI premiums are typically higher than owner-occupier equivalents.
Do not plan around a specific LMI dollar amount without running a current calculation through a lender or insurer, as premiums vary significantly between lenders and LVR bands. The key strategic question is whether paying LMI to enter the market earlier makes sense compared to waiting to accumulate a larger deposit. That decision depends on your cash-flow position, market timing assessment, and portfolio plan, not a universal rule. Avoiding LMI is not always the correct call if waiting materially delays a sound investment or depletes your emergency reserve.
Worked deposit examples for different Australian investor scenarios
All figures below are illustrative only. They are not lender approvals, quotations, or recommendations. Transaction costs vary by state, territory, lender, and individual circumstances.

Scenario 1: First-time investor using cash savings
| Item |
Illustrative figure |
| Target purchase price |
$650,000 |
| Deposit (20%) |
$130,000 |
| Loan amount (80% LVR) |
$520,000 |
| Transfer duty (state-dependent, estimate only) |
Check relevant state revenue office |
| Conveyancing and inspections |
Approximately $2,500 to $4,000 |
| Lender fees and valuation |
Approximately $500 to $1,500 |
| Emergency buffer (recommended) |
$15,000 to $20,000 |
| Indicative total cash target |
$150,000 to $160,000+ |
Assumption: The investor holds the deposit in cash savings, the lender values the property at the purchase price, and no LMI applies. Transfer duty must be calculated using the relevant state or territory revenue office for the target purchase location.
Scenario 2: Existing owner using usable equity
| Item |
Illustrative figure |
| Existing property accepted value |
$850,000 |
| Existing loan balance |
$450,000 |
| Maximum borrowable at 80% LVR |
$680,000 |
| Indicative usable equity |
$230,000 |
| Target investment property price |
$700,000 |
| Deposit funded from equity |
$140,000 (20%) |
| Remaining equity after deposit |
$90,000 (available for costs and buffer) |
Assumption: The lender’s accepted valuation matches the estimate, serviceability is confirmed for both facilities, and no cross-collateralisation is used. All figures are indicative. A mortgage broker must verify the actual accessible equity and loan structure.
Scenario 3: Growth-stage investor protecting future borrowing capacity
An investor already holding one or two properties may technically have enough equity or cash for a third purchase. The decision is rarely that straightforward. Using every available dollar of deposit leaves no room for vacancy periods, maintenance costs, or a rate increase across the portfolio.
A 25% deposit instead of 20% means a lower loan balance, smaller repayments, and a stronger position for the next acquisition. The investor who enters a third purchase over-leveraged can find that serviceability limits on a future purchase arrive sooner than expected. This connects directly to property investment mistakes to avoid: focusing only on the entry price rather than the cumulative repayment burden across the portfolio.
How to set a realistic deposit target before you buy
A useful deposit target answers three questions: how much will the lender accept, what does it cost to get through settlement, and what is left over to hold the property safely? Work through these seven steps before signing anything:

- Confirm borrowing capacity first. Speak with a current mortgage broker and obtain a conditional pre-approval so you know the lender’s position before you commit to a price range.
- Set a realistic property price range. Do not assume the largest loan you could theoretically obtain is the right starting point.
- Calculate transfer duty for your target state or territory. Use the official state or territory revenue office calculator, not an estimate from a property listing.
- Add all purchase costs. Include conveyancing, inspections, lender fees, valuation, landlord insurance, and any body corporate adjustments.
- Model repayments conservatively. Because APRA requires ADIs to assess repayments at the loan rate plus a 3-percentage-point buffer, model your cash flow at a higher-than-current rate to check whether the investment is still viable.
- Reserve an emergency and vacancy buffer. Most experienced investors hold a buffer covering at least three to six months of loan repayments and anticipated maintenance costs.
- Confirm alignment with your investment strategy. The deposit target should reflect the property type, location, and hold period that fits the wider portfolio plan, not just the maximum affordable price.
If you want to connect your current deposit position to a concrete property plan, book a free strategy session with the Buyers Agency Australia team before committing to a price range or loan application.
How Buyers Agency Australia can fit into deposit planning
Australia-wide buyer-side support from Buyers Agency Australia centres on connecting an investor’s available capital to the right market, property type, and acquisition strategy. Once the finance framework is established with a mortgage broker, the buyers agent role shifts to identifying suitable assets, assessing risk, negotiating terms, and supporting the buyer through due diligence and settlement.
Dragan Dimovski, a property expert with more than 20 years of experience, understands that a deposit figure alone does not make a property purchase sound. The selection of the asset, the structure of the acquisition, and the fit with the investor’s portfolio sequencing determine whether the deposit is deployed well.
Buyers Agency Australia’s service details were checked in August 2026. The service covers strategy, data-led suburb selection, property assessment, negotiation, and support from planning through to settlement.
When this is not the right fit
A buyers agent is not a replacement for a mortgage broker, accountant, tax adviser, solicitor, or conveyancer. Readers who do not yet have a confirmed finance position, or who need guidance on negative gearing, ownership structure, SMSF investment, CGT, or contract terms, should resolve those questions with the relevant licensed or registered professional first. A buyers agent adds the most value when the finance framework is established and the focus moves to identifying and securing the right property.
Disclosure: Buyers Agency Australia is the publisher’s own service. This section describes the service in good faith using current official brand context checked in August 2026.
Frequently asked questions about investment property deposits
How much deposit do I need for an investment property in Australia?
A 20% deposit is the most commonly used benchmark, producing an 80% LVR and often avoiding LMI. The practical cash target is higher once transfer duty, conveyancing, inspections, and a buffer are included.
Can I buy an investment property with a 10% deposit?
Some lenders may consider a 10% deposit for an investment loan, typically with LMI and a stricter serviceability assessment. Availability and LMI cost are lender-specific. Confirm the full acquisition cost with a mortgage broker.
Can I buy an investment property with a 5% deposit?
The Australian Government’s 5% Deposit Scheme is for eligible owner-occupiers and does not apply to investment properties. A 5% deposit is not a standard investor pathway with mainstream lenders.
Is 20% enough once stamp duty and buying costs are included?
No, not on its own. A 20% deposit covers only the lender’s equity requirement. Transfer duty, conveyancing, inspections, lender fees, and a buffer add to the cash requirement and must be funded separately.
Can I use equity instead of cash for the deposit?
Yes, subject to lender valuation and full serviceability assessment for both properties. Usable equity is calculated as a proportion of your existing property value minus the outstanding loan balance. It is not free money and carries valuation, repayment, and cross-collateralisation risks.
Does LMI apply to investment property loans?
LMI may apply when an investment loan’s LVR exceeds the lender’s preferred threshold, typically above 80%. LMI protects the lender, not the borrower, and the premium for investment loans differs from owner-occupier equivalents. Confirm the cost with a current lender or insurer calculation.
Can gifted money be used as an investment property deposit?
Some lenders may accept gifted funds as part of a deposit, but conditions apply and lender policies differ. You should disclose the source of funds to your lender and confirm policy with a current mortgage broker before relying on gifted money as your deposit.
Can I use superannuation to buy an investment property?
Generally, superannuation cannot be accessed directly for an investment property deposit outside of a self-managed super fund (SMSF). SMSF property investment is subject to strict restrictions under current ATO guidance on SMSF investing. Specialist SMSF advice from a registered adviser is required before proceeding.
Does negative gearing help me fund the deposit?
No. Negative gearing explained for investors refers to a tax treatment applied to rental losses, not an upfront cash source. It may reduce your tax liability over time but does not create deposit cash. Consult a registered tax adviser for advice specific to your circumstances.
Does buying interstate change how much deposit I need?
The deposit policy is set by the lender and is not state-specific. However, transfer duty, transaction costs, and any state-based taxes or concessions vary significantly by state or territory and materially affect total cash required at settlement. Check the revenue office for your target state before finalising a budget.
Your next-step deposit plan
Three questions clarify where you stand before you proceed:
- How much cash or usable equity do you have confirmed? Not estimated, but verified with a lender or broker against a current valuation.
- What will the lender support? Serviceability, DTI ratios, and lender-specific investment policies all shape the approved loan amount independently of your deposit size.
- What acquisition strategy protects the portfolio? The deposit target should reflect the property type, hold strategy, and total cost of ownership, not just the purchase price.
If the answer to any of those questions is unclear, that is the right place to start. A clear finance picture before property selection prevents the common mistake of choosing an asset simply because it sits within a raw price ceiling.
To map out your next property move with a strategy that connects your deposit position to a sound acquisition plan, reach out to the Buyers Agency Australia team. To speak directly, contact the team and we can work through the next steps with you.
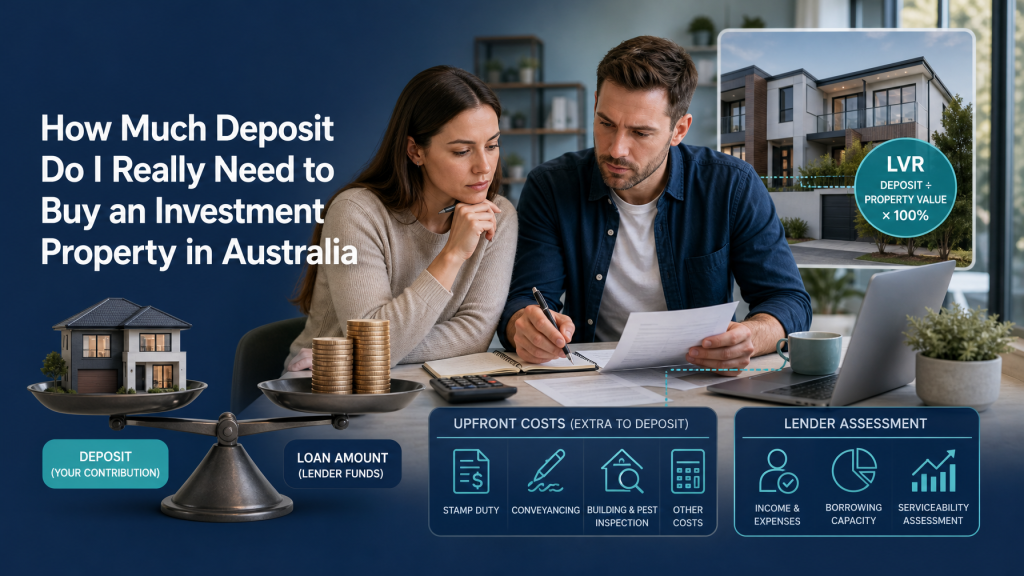 General
Learn how much deposit you need for an Australian investment property, including LVR, LMI, buying costs, equity, and...
You may be ready to buy an investment property in 2026 if your borrowing capacity, cash buffer and strategy remain sound under conservative assumptions. Waiting may be wiser if the purchase only works after a forecast rate cut, expected capital growth or optimistic rent. As at 17 June 2026, the RBA cash rate target sits at 4.35%, with the next scheduled decision on 11 August 2026. APRA-regulated banks apply a minimum 3 percentage-point serviceability buffer when assessing new borrowers. Recheck both figures before committing to a purchase.
You have a deposit ready. You have been watching the market for months, perhaps longer. And yet the question keeps returning: is this the right moment, or is waiting the smarter call?
That tension is completely understandable. The decision to buy investment property is not simply a bet on where prices go next. It is a test of whether your finances, your chosen asset, and your investment plan can hold up if conditions shift in any direction.
This guide works through both sides of that decision using current market data, finance fundamentals, cash flow analysis and a practical readiness framework. Buyers Agency Australia approaches every purchase through a strategy-led lens, and the same logic applies here: the right time to buy is when the property and the plan stack up, not when a headline says so.
This article provides general property investment information and is not personal financial, tax or legal advice.
Should You Buy an Investment Property in 2026 or Wait?
The clearest decision rule is this: buying makes sense when you can support the property under conservative assumptions, not just under ideal ones.
A rising or falling national market does not determine whether your specific purchase is sound. Two investors who buy in the same month in the same city can have very different risk profiles depending on their loan structure, cash buffer, property selection and holding period. The Australian property market is not one thing. It is a collection of submarkets, price points and property types, each responding differently to rate movements, supply conditions and local demand.
Market timing and purchase timing are different decisions. Market timing asks when the overall market is cheap. Purchase timing asks whether this investor, with this finance and this property, can hold comfortably through uncertainty. The second question is the one worth answering.
What Does the 2026 Australian Property Market Data Actually Show?
The data paints a mixed picture, and that is precisely the point.
The RBA held the cash rate at 4.35% effective 17 June 2026, following three consecutive increases earlier in the year. The Board noted that inflation remains above target and that financial conditions have tightened. The next scheduled decision is 11 August 2026.
The PropTrack Home Price Index for June 2026 recorded a national price fall of 0.3% for the month, while prices remained 5.8% higher year-on-year. According to ABS Lending Indicators for the March quarter 2026, new investor loan commitments fell 5.3% in the quarter, though they remained 18.8% above the same period a year earlier. The June quarter release is scheduled for 14 August 2026.

| Signal |
What it tells you |
What it does not tell you |
| Cash rate at 4.35% |
Borrowing is more expensive than 2023 lows |
What the next RBA decision will be |
| National prices down 0.3% in June |
Short-term softening across most capitals |
Whether your target suburb or property type has softened |
| Investor loans down 5.3% in Q1 2026 |
Some investors are pulling back |
Whether the right property in the right market is still viable |
| Prices still 5.8% above year-ago |
Broad market remains above recent lows |
Whether entry at today's price offers long-term value |

The national figures are a starting point, not a decision. Two properties bought in the same month can carry very different risk profiles based on suburb, property type, rental demand and purchase price.
What Would Make Buying an Investment Property in 2026 Sensible?
Buying in 2026 may make sense when the investor can support the property without relying on a future rate cut or forecast capital growth. The conditions that justify proceeding are specific and testable.
ASIC MoneySmart's investment property guidance identifies financial readiness, risk tolerance and genuine understanding of ownership costs as prerequisites before any purchase. The four conditions worth testing are below.
You Can Fund the Deposit, Purchase Costs and Cash Buffer
The upfront requirement is not simply the deposit. Transfer duty (often called stamp duty) varies by state, property value and investor status. Conveyancing, building and pest inspections, and lender fees all add to the initial outlay. Requirements vary by lender, state and personal circumstances, so the right starting point is a confirmed pre-approval and a full cost schedule from your conveyancer before signing.
Retaining a cash buffer after settlement matters just as much. An investor who depletes all available funds at purchase is exposed to vacancy, unexpected repairs or a change in income before the property stabilises.
The Loan Works Under Conservative Assumptions
Approval is not the same as viability. A lender may approve a loan that only remains manageable if rent is paid on time, vacancy is minimal and rates do not rise. The Australian Prudential Regulation Authority (APRA) confirmed in May 2026 that the minimum 3 percentage-point mortgage serviceability buffer applied by APRA-regulated banks when assessing new borrowers remains in place. That buffer is a lending assessment rule, not a personal guarantee of affordability. The property should be stress-tested against higher interest rates and lower rent before any purchase decision is finalised.
For further detail on navigating a higher-rate environment, see Buyers Agency Australia's guide to property strategy in a rising-rate market.
The Property Matches a Written Investment Strategy
A purchase without a written strategy is a guess. Before committing, the investor should be able to describe the target capital growth profile, acceptable rental yield range, preferred property type, holding period, and how the acquisition fits into any broader portfolio plan. If those answers do not exist in writing, that alone is a reason to pause.
When Is Waiting the More Sensible Choice?
Waiting is not automatically cautious if the delay is based only on headlines and has no defined decision rule. But waiting is clearly the right call under several circumstances.
Your Borrowing Position Is Unclear or Too Tight
If a formal pre-approval is not in place, income is variable, existing debt is unresolved or the loan only passes the serviceability test with optimistic assumptions, the purchase should not proceed. A qualified mortgage broker and financial adviser are the appropriate professionals to consult on personal borrowing capacity. Proceed only when the numbers are confirmed, not estimated.
Be aware that common property investment mistakes in 2026 often stem from acting on an informal lending estimate rather than a verified pre-approval.
The Cash Buffer Would Be Depleted
Using all available cash to settle leaves no margin for the real costs of ownership. Vacancy periods, urgent repairs, rising insurance premiums, council rates, water charges, land tax and unexpected finance costs can all appear in the first twelve months. A responsible holding plan includes a named reserve, not a vague intention to save after purchase.
You Are Waiting for a Perfect Market Signal
A purposeful delay is different from indefinite waiting. If the investor is waiting for a rate cut, a price correction or a more confident headline, the question to ask is: what specific condition would need to be true before proceeding, and how would that condition actually improve the numbers?
Waiting for an event that cannot be dated or defined is not a strategy. If the plan is to buy when rates fall, model the property at the current rate first. If it does not work today, confirm whether a rate reduction would actually change the decision, or whether other factors such as the deposit, property quality or strategy clarity need to be resolved first.
How Do Interest Rates and Borrowing Capacity Affect the Decision?
Many investors conflate the RBA cash rate with the rate they actually pay. They are different inputs.

Cash Rate, Loan Rate and Repayment Cost Are Different Inputs
The RBA cash rate (4.35% effective 17 June 2026, recheck at the RBA's monetary policy decisions page before publication) influences but does not directly set the rate a lender charges on an investor loan. The actual investor loan rate depends on lender pricing, the loan-to-value ratio, loan structure (principal and interest versus interest-only), and individual credit assessment. The gap between the cash rate and the rate actually offered on investor mortgages has varied across the cycle.
The APRA Serviceability Buffer Matters Before You Buy
APRA requires APRA-regulated banks to assess a new borrower's ability to repay at their actual loan rate plus a minimum 3 percentage-point buffer. As confirmed in the APRA System Risk Outlook May 2026, this buffer remains in place. If an investor is offered a loan at 6.5%, the lender assesses repayment capacity at around 9.5%. This is an assessment rule applied at origination, not a statement about affordability at that rate.
Stress-Test Three Holding Scenarios
The table below uses illustrative figures only. Investors should build their own model using actual loan offers, confirmed rental appraisals and state-specific cost estimates.
| Assumption |
Base case (illustrative) |
Cautious case (illustrative) |
Adverse case (illustrative) |
| Weekly gross rent |
$550 |
$500 |
$450 |
| Vacancy allowance |
2 weeks per year |
4 weeks per year |
8 weeks per year |
| Investor loan rate |
6.5% |
7.0% |
7.5% |
| Annual maintenance |
$2,000 |
$3,500 |
$5,000 |
| Net cash position |
Model your actual numbers |
Model your actual numbers |
Model your actual numbers |
The purpose of the table is to show that the loan and property should remain manageable under the cautious and adverse columns, not just the base case. If the numbers only work under base assumptions, the purchase carries more risk than it may appear.
What Property Fundamentals Matter More Than Market Timing?
Once finance is confirmed, the quality of the specific property becomes the primary risk variable.
Rental Demand, Vacancy and Tenant Depth
A low vacancy rate at the time of purchase is useful but insufficient. What matters is the direction of vacancy, the tenant demographic, the volume of comparable rentals entering the market, and whether the property would lease quickly at a realistic rent. A rental appraisal from an independent property manager, not the selling agent, is the appropriate evidence base.
Employment, Population and Infrastructure Need Local Evidence
Suburb-level demand is driven by employment access, population growth and physical infrastructure. These factors require local evidence from government, council and planning authority sources. An infrastructure announcement does not guarantee capital growth; the relevant questions are funding confirmation, project timing, delivery risk and how the change affects the specific suburb.
Supply Risk Can Matter More Than a Headline Growth Rate
A suburb with strong rental demand today can be oversupplied within two years if development approvals, zoning changes or apartment completions are adding significant stock. Check development applications and planned completions in the relevant council and state planning portal. Oversupply risk is property-type and location specific.
Property Quality and Resale Appeal Protect the Exit
The exit test is worth applying at purchase: if this investor needed to sell or refinance under less favourable conditions, would the property appeal to a broad buyer pool? Layout, land component, construction quality, strata risks, absence of material defects, and genuine owner-occupier appeal all affect the future buyer pool. A property that only appeals to other investors carries a narrower exit and higher risk at any stage of the cycle.
What Should Your Investment Property Cash Flow Model Include?
Gross yield and net cash flow are not the same figure, and treating them as equivalent is one of the most common modelling errors in property investment.
Separate Gross Rental Yield from Net Cash Flow
Gross rental yield is annual rent divided by purchase price, expressed as a percentage. It excludes every ownership cost. Net cash flow is what remains after all income has been received and all expenses have been paid. The gap between the two is usually substantial. For more context on building a positive position, see Buyers Agency Australia's overview of positive cash flow property investing.
Include Every Purchase and Holding Cost
A complete model includes at minimum:
- Loan interest (and principal repayments where applicable)
- Vacancy allowance (weeks per year at the actual rent)
- Property management fees
- Building and landlord insurance
- Council and water rates
- Repairs and routine maintenance
- Capital expenditure reserve (roof, hot water, appliances)
- Strata levies and special levies where applicable
- Land tax (varies by state, ownership structure and total portfolio value)
- Accounting and tax return preparation
- Transfer duty and conveyancing at acquisition
The Australian Taxation Office rental properties guidance and ASIC MoneySmart's investment property page both identify costs that are regularly overlooked by first-time investors.
Treat Tax Benefits as a Secondary Input
Tax deductions on investment property interest and eligible expenses may reduce taxable income, but they do not remove the cash outflow. The Australian Taxation Office is the correct source for rental expense rules; a registered tax adviser is the appropriate professional for personal tax planning. Tax treatment should not be the primary justification for a purchase that does not otherwise stack up.
A 2026 Investment Property Readiness Checklist
This checklist divides readiness into three areas. A stop condition in any area is a reason to pause, regardless of how strong the other categories look.

Financial Readiness
- Formal pre-approval confirmed with a qualified mortgage broker
- Full upfront cost schedule prepared (transfer duty, conveyancing, inspections, lender fees)
- Post-settlement cash buffer retained (separate from the deposit)
- Loan stress-tested at the cautious and adverse rate scenarios above
- Ability to fund a vacancy period of at least four to eight weeks without financial strain
- Future borrowing capacity considered: does this purchase affect the next acquisition?
Strategic Readiness
- Written investment strategy exists with a defined target outcome and holding period
- Property type, location criteria and acceptable yield range are documented
- Risk tolerance is understood relative to the debt level and income stability
- Portfolio sequencing plan is in place (how does this purchase affect the next one?)
- Professional team engaged: mortgage broker, accountant, solicitor or conveyancer
Property Readiness
- Independent rental appraisal obtained
- Comparable sales analysis completed for purchase price validation
- Building and pest inspection by a licensed inspector
- Title or strata records reviewed by a solicitor or conveyancer
- Development pipeline and supply risk assessed for the suburb
- Planning, zoning and any encumbrances checked
For a broader foundation, see how to invest in property in Australia as a starting reference before working through the checklist above.
If all three readiness categories pass, the next step is applying a structured decision framework. If any stop condition is present, the appropriate action is to resolve it before proceeding, not to proceed and hope for the best. To work through your specific position with an experienced team, book a free strategy session with Buyers Agency Australia.
When Can a Strategy-Led Buyers Agent Help You Decide?
A buyers agent operates on the investor's side of the transaction. That distinction matters because the selling agent's obligation is to the vendor, not to the buyer.
Where Buyers Agency Australia Fits
Buyers Agency Australia is a buyer-side property advisory service with a national footprint, offering data-led suburb selection, access to off-market and pre-market opportunities, and end-to-end support from strategy development through to settlement. Dragan Dimovski, who brings more than 20 years of property experience to the role, leads an approach that centres on investment property strategy, portfolio planning and objective market research.
The service is most useful when the investor needs a repeatable acquisition process, not simply more listings. That includes defining the brief, researching markets, identifying suitable opportunities, coordinating due diligence, negotiating on behalf of the buyer, and managing the path to settlement.
Buyers Agency Australia provides buyer-side property advisory support. This article is general information and is not personal financial, tax or legal advice.
When This Is Not the Right Fit
A buyers agent cannot replace a mortgage broker, accountant, tax adviser, solicitor, building inspector or personal financial adviser. Each of those professionals provides advice or services that a buyers agent is neither qualified nor licensed to replicate.
A reader who has not confirmed borrowing capacity, does not retain adequate cash reserves or has not defined a clear investment strategy may benefit more from professional financial and legal preparation than from engaging a buyer-side service at this stage. Resolving those foundations first makes every subsequent step, including property search and acquisition, more effective.
How Do I Decide Whether to Buy Now or Wait?
The framework below is an editorial decision aid, not financial advice. Use it alongside professional guidance from a mortgage broker, accountant and legal adviser.

Use a Five-Part Buy-or-Wait Scorecard
| Category |
Score 0: Unsupported |
Score 1: Partly supported |
Score 2: Evidence-backed |
| Financial readiness |
No pre-approval, deposit or buffer confirmed |
Pre-approval in progress, costs estimated |
Full pre-approval, costs confirmed, buffer retained |
| Property quality |
No due diligence completed |
Some checks done, gaps remain |
Independent valuation, inspections and comparables complete |
| Market evidence |
No local research, relying on national averages |
Suburb data reviewed but dated or incomplete |
Current vacancy, rental evidence and supply data confirmed |
| Strategic fit |
No written strategy or portfolio plan |
Strategy outlined but not stress-tested |
Written plan, holding period defined, portfolio impact modelled |
| Downside resilience |
Purchase only works under optimistic assumptions |
Manageable under base case, tight under cautious |
Serviceable under cautious case, survivable under adverse case |
A total score of 8 to 10 supports proceeding. A score of 5 to 7 suggests specific gaps to resolve before committing. A score below 5 is a clear signal to delay.
Use Stop Conditions, Not Just a Total Score
A high total score cannot override a critical failure. Do not proceed if any of the following apply:
- Finance is unconfirmed or only works under optimistic income assumptions
- The cash buffer would be depleted at or shortly after settlement
- Due diligence is incomplete or relies on the selling agent's information
- The investment thesis depends on a forecast rate cut, expected capital growth or above-market rent
To map out your next property move with a clear plan in place, a free strategy session is available through Buyers Agency Australia's investment property approach.
Frequently Asked Questions About Buying an Investment Property in 2026
Is 2026 a good time to buy an investment property in Australia?
It can be, but there is no single national answer. Readiness and property evidence matter more than a market headline. Current data shows national softening, but submarkets vary significantly.
Should I wait for interest rates to fall before buying?
Do not make a purchase depend on a forecast rate cut. Test the property at a conservative current-rate assumption and the cautious scenario above. The RBA cash rate was 4.35% as at 17 June 2026; the next decision is 11 August 2026.
How do I know if I am financially ready to buy?
You are financially ready only when finance, purchase costs and reserves are all understood and confirmed. A mortgage broker and financial adviser are the appropriate professionals for personal assessment.
What interest rate should I use when modelling an investment property?
Use the actual loan offer or a conservative lender-based assumption, then stress-test a higher rate as shown in the scenarios above. Do not use the RBA cash rate as a proxy for your investor loan rate.
What costs should I include in an investment property cash flow model?
Include rent, vacancy, interest, principal, management, insurance, rates, repairs, maintenance, strata, land tax and acquisition costs. The ASIC MoneySmart guide and the ATO rental properties guidance both provide relevant cost categories.
Does rental yield matter more than capital growth?
Neither metric should be used alone. Rental yield measures income relative to purchase price, while capital growth measures asset appreciation. Both need to be assessed against holding costs, risk and portfolio fit.
How can I tell if a property fits my portfolio strategy?
A property fits when it advances a defined portfolio goal without creating unacceptable debt or concentration risk. If no written strategy exists, the first step is to create one.
When is waiting safer than buying?
Waiting is safer when the numbers are unconfirmed or the downside cannot be funded. Stop conditions include unconfirmed finance, an insufficient cash buffer, incomplete due diligence, or a thesis that depends on forecast growth or rate cuts.
What due diligence should I complete before buying?
Complete independent checks on value, condition, title or strata, rental evidence, planning and contract terms. A licensed building inspector handles the physical assessment, a solicitor or conveyancer handles the legal review, and an independent property manager provides the rental appraisal.
Can a buyers agent help me decide whether to buy now or wait?
A buyers agent can help assess strategy, markets and properties, but cannot make personal financial decisions for you. Buyers Agency Australia provides buyer-side strategy, market research and acquisition support as part of a broader professional team that should also include a mortgage broker, accountant and solicitor.
Final Decision: Buy When the Strategy and Property Stack Up
The answer to whether you should buy an investment property in 2026 is not a calendar prediction. It is a readiness test.
Buying makes sense when the loan is confirmed and stress-tested, the cash buffer is retained, the property passes an independent due diligence process, and the investment thesis does not depend on events that cannot be controlled or dated.
Waiting makes sense when any of those conditions are absent, or when the purchase only works under optimistic assumptions that the investor cannot verify today.
The next steps are practical: confirm borrowing capacity with a qualified mortgage broker, build the full cash flow model including every holding cost, write down the property criteria, engage a solicitor or conveyancer early, and apply the stop conditions before any offer is made.
For investors who want a structured process from suburb research through to settlement, map out your next property move with a free strategy session. To speak directly with the team, contact the team at Buyers Agency Australia.
 General
Use this Australia-focused framework to test finance, cash flow, property quality and risk before deciding to buy investment...
The most expensive property investment mistakes in Australia are almost always process errors: buying without a strategy, chasing headlines, judging one metric in isolation, skipping due diligence, underestimating holding costs, rushing under pressure, and ignoring the wider portfolio. Start with your goals and borrowing constraints, stress-test the suburb and property evidence, and only proceed when the purchase still works under conservative assumptions. APRA-regulated lenders apply a minimum 3 percentage point mortgage serviceability buffer when assessing new borrowers, so any plan must work beyond today's repayment setting.
You have finance approval, a shortlist of suburbs, and pressure to act. What you may not have written down is what this property must actually do for your portfolio.
That gap between urgency and strategy is where most acquisition errors begin. The real question is rarely "where should I buy?" It is whether this specific property fits your goals, borrowing capacity, cash flow requirements, and future purchases.
This is where strategy-led property investing makes the difference. The seven mistakes below were chosen for their likely financial consequence, frequency in the Australian decision process, actionability, and the strength of available evidence. They appear in dependency order, not as a ranked claim that one is universally more costly than another.
Why these property investment mistakes matter more in 2026
Australia's residential dwelling stock reached $12.8 trillion in value during the March quarter 2026, according to the Australian Bureau of Statistics, yet that national figure masks sharp state-level divergence. Western Australia and Queensland recorded strong quarterly gains, while Victoria saw a small decline. National averages tell investors very little about whether a specific suburb or property type will serve their plan.

At the same time, the RBA held its cash rate target at 4.35 per cent effective 17 June 2026, following three consecutive increases earlier in the year. APRA maintained its 3 percentage point mortgage serviceability buffer as of June 2026, meaning lenders assess new borrowers at their actual rate plus 3 points. The cost of process failure in this environment is not just a bad purchase. It is a purchase that compromises every decision that follows.
How these seven mistakes were selected
These mistakes were identified using five editorial criteria:
- Likely financial consequence for Australian investors
- Frequency in the acquisition decision process
- Relevance to the 2026 Australian market and regulatory context
- Actionability for investors who identify the issue
- Quality and availability of supporting official evidence
This is an editorial methodology, not a statistically representative survey. These are not claimed to be the only costly mistakes, and no universal dollar loss is attributed to any single error without a clearly labelled assumption.
Mistake 1: Buying an investment property without a clear strategy
Most investors begin searching for a property before they have defined what that property must do. Without a written strategy, the selection process defaults to price, proximity, or what looks good on inspection day. These are not reliable proxies for investment fit.
A complete property investment strategy should cover the portfolio role of the purchase (growth, cash flow, or both), the intended hold period, the cash flow floor the investor can carry, the ownership structure, and the next-purchase constraint. Why property investment strategy matters more than suburb selection is a point many first-time investors discover only after they have already committed to a purchase that limits their next move.
As Moneysmart notes, investors should consider their goals, timeline, and risk tolerance before acquiring an investment property.
What should an Australian property investment strategy include?
| Element |
What to define before searching |
| Portfolio goal |
Growth, cash flow, or hybrid; which comes first and why |
| Investment timeline |
Intended hold period and any exit or sale trigger |
| Cash flow floor |
Minimum net position you can carry, including vacancy periods |
| Borrowing capacity |
Current confirmed limit, not an optimistic estimate |
| Risk tolerance |
Acceptable vacancy rate, repair exposure, and market volatility |
| Ownership structure |
Individual, joint, trust, or company; tax advice required |
| Next-purchase test |
What must this property make easier or harder within 3 to 5 years |
Mistake 2: Choosing a suburb from headlines or past growth alone
Recent capital growth in a suburb is descriptive. It tells you what happened. It does not tell you whether the conditions that drove that growth remain in place or whether any remaining upside is already priced in.

Media rankings, suburb "hotlists", and familiar postcode bias are common selection shortcuts. None of them replace a structured assessment of demand drivers, supply pipeline, employment base, infrastructure spending, vacancy rates, owner-occupier appeal, and resale liquidity for the specific property type you are buying. For additional context on property investment hotspots and strategies in 2026, including which markets are showing structural demand signals, the brand's research covers current suburb-level evidence rather than headline rankings alone.
How do you know whether a suburb fits your investment strategy?
Use a two-layer location test. First, assess the market:
- Demand signals: population growth, employment diversity, net migration, and infrastructure pipeline
- Supply signals: approved development applications, new dwelling completions, and stock on market
- Price and rent trend: use dated suburb-level data, not national averages
- Vacancy rate: compare with the local historical range, not a single point in time
Second, assess whether the specific property type has demand and resale appeal. A suburb with strong house demand does not automatically support unit demand, and vice versa. The property must fit both the market and your investor profile. For 2026 Australian property market context, market-level evidence should be cross-checked against current suburb-level data before any acquisition decision is made.
Mistake 3: Looking at price, yield or cash flow in isolation
An attractive entry price or a high gross rental yield can be a genuinely useful signal. It can also hide weaker demand, oversupply, thin land content, high holding costs, or low resale liquidity. The risk is that investors treat one number as sufficient evidence for a purchase.
Gross yield is calculated before vacancy, property management fees, insurance, rates, repairs, body corporate fees, land tax, and interest. The gap between gross and net can be substantial. Moneysmart confirms that investors still carry all ownership costs during vacancy periods, which directly compresses the net return picture.

Can a high rental yield still be a bad investment?
Yes. Gross yield does not account for the quality or durability of the tenant demand behind it. A high yield may reflect a location where vacancy is structural, where resale demand is thin, where the property type has poor land content, or where operating costs are above average. The ATO treats rental property income and associated deductions differently depending on ownership structure and property type. Investors should obtain current ATO guidance on property tax treatment and work through the net position with their accountant before relying on a gross yield figure.
| Metric |
What it shows |
What it hides |
| Gross rental yield |
Rent as a percentage of purchase price |
Vacancy, management fees, repairs, insurance, land tax, body corporate |
| Net cash flow |
Actual cash surplus or shortfall |
Capital growth assumptions, resale liquidity, asset quality |
| Purchase price |
Entry cost |
Comparable sales context, land content, depreciation |
| Capital growth assumption |
Potential upside |
Evidence basis, hold period required, compounding holding costs |
Before proceeding, ask what remains after vacancy, management, insurance, council rates, repairs, body corporate fees, land tax, loan interest, and tax effects. If the net position only works under optimistic assumptions, treat that as a pause signal.
Mistake 4: Skipping property, building and legal due diligence
Due diligence is not a tick-box exercise. It is the process that tests whether the property, contract, location, and price are consistent with what you believe you are buying. Skipping any part of it means making a decision with incomplete information, often under time pressure.
State-specific requirements for building inspections, strata records, contract reviews, and title searches vary. Always engage qualified professionals rather than relying on selling-agent representations.
Which due diligence checks should happen before an investor makes an offer?
| Check |
Purpose |
Who verifies it |
Decision consequence |
| Comparable sales |
Confirm price is in line with recent market evidence |
Investor, buyers agent, or valuer |
Overpaying risk if skipped |
| Building and pest report |
Identify structural defects, timber pests, moisture |
Licensed building inspector |
Unexpected repair costs if missed |
| Strata or owners corporation records |
Assess levies, disputes, capital works, and financial health |
Solicitor or strata inspector |
Hidden future costs or disputes |
| Title search and encumbrances |
Confirm ownership, easements, caveats, covenants |
Conveyancer or solicitor |
Legal complications at settlement |
| Zoning and planning overlays |
Check permitted uses, development constraints |
State planning authority or council |
Future value or use limitations |
| Flood and climate risk |
Assess insurance exposure and land risk |
State flood authority, council, official flood maps |
Insurance cost or uninsurability |
| Tenancy details |
Confirm lease terms, rent, and condition provisions |
Solicitor reviewing lease documents |
Income or legal obligations missed |
| Capital works and future costs |
Estimate upcoming levies or maintenance requirements |
Strata manager, building report |
Cash flow impact post-purchase |
For investment property buyer support that covers due diligence coordination across these areas, Buyers Agency Australia works with investors to map required checks before an offer is made.
Mistake 5: Underestimating finance, holding costs and serviceability
Lender approval confirms that you qualify for a loan at current rates. It does not mean the purchase is comfortable across a range of real-world scenarios: a vacancy period, a rate increase, a significant repair, or a period of reduced income.
APRA-regulated lenders assess serviceability at the borrower's actual rate plus 3 percentage points. At a cash rate of 4.35 per cent effective 17 June 2026, as recorded by the Reserve Bank of Australia, this buffer adds meaningful pressure to borrowing capacity. Moneysmart's guidance on borrowing to invest confirms that investors carry interest and ownership costs even when rental income is lower or absent.
Two illustrative scenarios (labelled as assumptions, not forecasts):
- Six months of vacancy on an assumed $700 per week rent equals approximately $18,200 in forgone income before other costs are included.
- A 1 percentage point increase on an assumed $600,000 loan balance equals approximately $6,000 per year in additional interest before repayment structure is factored in.
These figures illustrate the cash flow sensitivity of a leveraged investment. They are not typical investor outcomes.
How can one purchase affect your ability to buy the next property?
Every investment property you hold reduces your assessed borrowing capacity for the next purchase. Lenders count the full loan commitment against your serviceability, regardless of what rental income offsets it. Loan structure matters too: an interest-only period can preserve cash flow in the short term but does not reduce assessed debt, and a principal-and-interest structure affects monthly cash position differently.
The practical consequence is that a property which is affordable in isolation may close off the next purchase entirely. For investors thinking in sequences rather than single transactions, the structure of each loan and the cash flow position of each asset need to be modelled before committing. Consult a licensed mortgage broker for personalised lending advice.
For context on how negative gearing changes in Australia may affect future tax outcomes for investors, current ATO guidance and professional advice from a qualified accountant remain the appropriate sources. The ATO's current position on property and land taxation should be checked before any tax-led investment decision is made.
Mistake 6: Becoming emotionally attached or rushing to secure a deal
Property acquisition carries real emotional pressure. Open homes, competitive auctions, vendor urgency, and fear of missing out can all narrow the decision window faster than the evidence base justifies.
Common warning signs that emotion is driving the decision:
- You are considering bidding beyond your pre-set maximum because you "really want this one"
- You are rationalising a weaker property because of sunk inspection costs
- You are accepting verbal rental estimates from the selling agent without independent evidence
- You are anchoring on the asking price rather than comparable sales
- You are shortening the due diligence period to avoid losing the deal
The stop-work rule: if a new piece of evidence changes how you score the property (building report, comparable sale, tenancy review, or finance update), pause rather than rationalise the purchase. A rushed decision made under auction pressure is one of the most common ways investors end up with a property that looked acceptable on the day but does not hold up to a colder review.
Set your maximum price before inspection day and treat it as a firm limit, not a starting point for negotiation under pressure.
Mistake 7: Treating an investment property as a standalone purchase
A property that works well in isolation can still be the wrong purchase if it weakens the broader portfolio. Investors who think in single transactions often find that the first or second purchase creates constraints they did not anticipate: reduced borrowing capacity, concentrated exposure to one market or property type, a cash flow position that cannot carry the next acquisition, or an exit structure that has not been thought through.

The next-purchase test is a useful discipline: before committing to any property, ask what this purchase makes easier or harder over the next three to five years. Relevant questions include:
- Does this purchase leave enough borrowing capacity for the next acquisition?
- Does the asset type and location diversify or concentrate portfolio risk?
- Is equity growth from this asset likely to fund the next deposit within the intended timeline?
- What is the exit plan, and does the asset type have sufficient resale demand to support it?
As Moneysmart's investment property guidance notes, diversification and planning considerations apply to property portfolios just as they do to other asset classes. A portfolio-sequencing mindset treats every purchase as a decision that affects all future decisions, not as a standalone transaction.
What should Australian investors check before buying an investment property?
The following framework applies in order. A missing high-risk item should move the decision from "go" to "pause" until it is resolved.

| Step |
Decision criterion |
Required source or document |
Outcome |
| 1. Written strategy |
Is the purchase role defined? |
Investor's written brief |
Go / Pause |
| 2. Finance confirmation |
Is borrowing capacity confirmed by a broker? |
Lender pre-approval or broker assessment |
Go / Pause |
| 3. Suburb evidence |
Has demand, supply, and vacancy been assessed? |
ABS, PropTrack, council, or planning authority data |
Go / Pause |
| 4. Property fit |
Does the property type match the strategy and suburb? |
Comparable sales, rental evidence |
Go / Pause |
| 5. Total cost model |
Has net return been modelled including all holding costs? |
Investor model with stated assumptions |
Go / Pause |
| 6. Due diligence |
Are building, legal, planning, and flood checks complete? |
Inspector, conveyancer, solicitor, official maps |
Go / Pause / Walk away |
| 7. Maximum price |
Is a firm price limit set before negotiation or auction? |
Written investor brief |
Go / Pause |
| 8. Independent advice |
Have tax, finance, and legal questions been referred? |
Accountant, broker, solicitor |
Go / Pause |
| 9. Portfolio test |
Does this purchase support the next acquisition? |
Investor's portfolio model |
Go / Pause / Walk away |
If you are unsure how to complete this framework for your situation, book a free strategy session with the Buyers Agency Australia team before committing to a search.
When can Buyers Agency Australia help reduce investment risk?
Buyers Agency Australia is the publisher of this article and the service provider described in this section. The following explains process fit, not guaranteed investment performance.
Dragan Dimovski, founder of Buyers Agency Australia, brings 20+ years of personal property investing experience to the advisory process. The brand's data-led property buying approach is structured around five stages that directly address the seven mistakes above:
- Strategy alignment: Clarifying the portfolio goal, borrowing position, cash flow requirement, and next-purchase constraint before the search begins.
- National research: Assessing suburb-level demand, supply, vacancy, and property type evidence using current data rather than headline rankings.
- Property sourcing: Accessing both listed and off-market properties as an expanded sourcing channel. Off-market access is a sourcing tool, not proof that any individual property offers superior value or condition. Independent evidence is still required for every asset.
- Assessment and due diligence coordination: Coordinating building, pest, strata, title, and legal checks with qualified professionals before an offer is made.
- Negotiation and settlement support: Applying evidence-based comparable sales analysis and pre-set price discipline through negotiation and to settlement.
A buyers agent does not replace a mortgage broker, accountant, financial adviser, solicitor, conveyancer, building inspector, or planning authority. Each professional has a distinct and non-substitutable role in a sound acquisition process.
Website service details were checked in July 2026. Confirm current service scope and availability before publication.
When this approach is not the right fit
Buyer-side advisory support may not suit every investor:
- Investors who are not yet financially ready to purchase (finance not confirmed, deposit not in place)
- Investors seeking guaranteed returns or a promise of specific capital growth outcomes, which no buyers agent can ethically provide
- Investors who have a clear strategy and prefer to manage every step of the research, negotiation, and due diligence process independently
If any of the above applies, the most useful next step is to resolve those preconditions first before engaging any advisory service.
Frequently asked questions about property investment mistakes in Australia
What is the biggest property investment mistake Australian investors make?
Buying without a clear strategy is often the most consequential process error because it flows into every subsequent decision: asset selection, finance structure, and portfolio sequencing.
Can a high rental yield still be a bad investment?
Yes. Gross yield can hide vacancy, high maintenance, body corporate fees, land tax, weak resale demand, or structural oversupply. Net cash flow and asset quality both matter.
How do I know if a suburb fits my investment strategy?
Compare the suburb's demand drivers, supply pipeline, vacancy rate, employment base, and property-type evidence against your goals, cash flow tolerance, and risk profile.
What costs should I include before buying an investment property?
Include stamp duty, loan costs, interest, vacancy allowance, council rates, insurance, repairs, property management, body corporate, land tax, and eventual sale costs. Use state-specific revenue office sources for duties and taxes.
How does borrowing capacity affect the next property?
Each purchase reduces future assessed capacity through additional debt, loan commitments, and cash flow obligations, even when rental income partially offsets the cost. Loan structure affects the impact.
What due diligence should I complete before making an offer?
Check comparable sales, building and pest condition, strata or owners corporation records, title, zoning, flood and planning risk, tenancy details, insurance exposure, and likely future capital works.
Is negative gearing a reason to buy an investment property?
No. Negative gearing is a tax outcome, not an investment thesis. It should be assessed with current ATO guidance and advice from a qualified accountant rather than used as the primary reason to buy.
Can a buyers agent guarantee property growth?
No. A buyers agent can support strategy, research, sourcing, assessment, and negotiation. Future property performance depends on many factors outside any advisory firm's control.
Does off-market property mean better value?
No. Off-market describes a sourcing channel, not the quality, condition, or price of the asset. Independent evidence and due diligence remain essential for every off-market property.
Final checklist for Australian property investors in 2026
Before committing to your next acquisition, work through each of the following:
- Is the purchase linked to a written strategy with a defined portfolio role?
- Does the property work after realistic costs, vacancy allowance, and a rate stress test?
- Has finance been confirmed by a broker and tested beyond today's repayment setting?
- Has the suburb been assessed using current, suburb-level evidence rather than media rankings?
- Have building, legal, planning, environmental, and strata checks been completed by qualified professionals?
- Is a firm maximum price set and documented before negotiation or auction?
- Does the purchase support, rather than compromise, the next portfolio decision?
If you can answer yes to all seven, you are working from process rather than pressure.
If any item is unresolved, map out your next property move with a free strategy session before you proceed. When you are ready to discuss buyer-side support, contact the team at Buyers Agency Australia.
This article is general educational information only and does not constitute personal financial, tax, or legal advice. Property investment involves risk and outcomes vary depending on individual circumstances. Speak with a licensed financial adviser, mortgage broker, accountant, solicitor, and qualified property inspector before making any investment decision. Buyers Agency Australia is the publisher and service provider discussed in this article.
 General
Avoid the 7 most costly property investment mistakes Australian investors make in 2026, from poor strategy and suburb...
No single sell date begins on 1 July 2027. An Australian investment property may no longer be worth holding when its forward net cash flow, asset fundamentals, risk profile and portfolio role no longer justify the capital tied up in it.
The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 changes how some established-property losses and post-1 July 2027 capital gains are treated, but those changes do not make every property a sell. Model the asset and your portfolio before acting, and obtain personal tax advice where needed.
Imagine opening your rent statement, scanning your loan balance, reviewing your insurance renewal, and then reading about 2027 tax changes. The question forming in your head is not really about the market. It is about this property, this debt, and whether holding on still makes sense.
That is the right question. The real test is not whether the Australian property market will be strong or weak, but whether this specific property still earns its place in your portfolio. That distinction matters, because a market-level headline cannot tell you what your particular asset costs to hold, who wants to rent it, or whether the capital it ties up could do more work elsewhere.
The review framework here covers four tests: cash flow, asset quality, risk, and portfolio fit. A sound Australian property investment strategy applies all four, not just the one that confirms an existing view.
Why 2027 Should Be a Review Point, Not a Sell Deadline
The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received Royal Assent on 26 June 2026 and applies the relevant residential property rules from the 2027-28 income year. It is a legal and planning reference point. It is not a universal market turning point, and it does not tell you whether your specific property is worth keeping.

What Changes From 1 July 2027?
The enacted legislation makes three material changes for property investors. First, the 50% capital gains tax (CGT) discount for individuals, trusts and partnerships is replaced by cost base indexation, with a 30% minimum tax applying to capital gains accruing from 1 July 2027. Second, negative gearing deductions for losses on residential dwellings acquired after 7:30 pm AEST on 12 May 2026 are quarantined from the 2027-28 income year and can only offset income from other residential properties. Third, eligible new residential dwellings retain the 50% CGT discount as an option and continue to qualify for negative gearing. The 2027 tax changes for investors are now law; the question is how they interact with each investor's actual circumstances.
| Asset category |
Negative gearing from 2027-28 |
CGT treatment from 1 July 2027 |
| Held at 7:30 pm AEST 12 May 2026 |
Full deductibility preserved |
50% discount applies to pre-1 July 2027 accrued gains; indexation applies thereafter |
| Established property acquired after that time |
Losses quarantined to residential property income only |
Cost base indexation; 30% minimum tax on gains |
| Eligible new residential dwellings |
Full negative gearing retained |
Choice of 50% discount or indexation method |
Source: Treasury Laws Amendment (Tax Reform No. 1) Act 2026, enacted 26 June 2026. Recheck with a registered tax adviser before acting.
Why a Tax Change Does Not Automatically Make an Asset a Sell
A tax rule changes the after-tax return on a property. It does not change the property's rental demand, land value, construction quality, or the depth of the market where it sits. An established investment property that was already generating strong net rental income, held in a well-located suburb with genuine tenant competition, does not become a poor asset because a tax concession narrows. Conversely, a property with persistent cash flow problems and structural weakness does not become viable simply because the tax position has not yet changed. Treat the 2027 reforms as one input, not the whole decision.
What Makes an Investment Property Worth Holding?
The hold decision is a forward-looking test, not a reward for past performance. For a property investment Australia guide approach, four attributes determine whether an asset earns its place in a portfolio.

Asset Quality and Location Fundamentals
Land value is the primary store of long-term appreciation for most residential properties. Assess the land-to-asset ratio, the supply of comparable stock, local employment diversity, population trends from ABS regional population data, transport access, and amenity. None of these factors guarantees a specific outcome, but each one influences the depth and consistency of demand over time.
Cash-Flow Resilience and Rental Demand
Gross yield is a starting point, not a verdict. A property showing a 5% gross yield on purchase price may produce a negative net cash position once vacancy, interest, property management, maintenance, insurance, council rates, land tax, and strata charges are deducted. The national vacancy rate sat at 1.2% as of May 2026 according to Mozo data referencing Cotality, but that national figure can mask suburbs where a specific property type faces meaningful competition. Obtain a current rental appraisal and compare it with the actual rent ledger over the past 12 months before drawing a conclusion.
Portfolio Fit and Future Use of Capital
A property can perform adequately in isolation and still be the wrong asset for a particular investor. Serviceability constraints, concentration in one market, debt structure, retirement timing, and the opportunity to fund a stronger acquisition can each change the hold calculus. The test is simple: if you did not own this asset today, would you buy it again at its current value and current holding cost? If the honest answer is no, that is worth examining.
How Do I Know If My Investment Property Is Still Working?
This diagnostic table separates signals that warrant a deeper review from those that suggest a property may need a more fundamental reassessment.
| Signal |
Likely meaning |
Evidence to collect |
Possible action |
| Persistent negative cash flow after all costs |
Holding cost exceeds rental income at realistic assumptions |
Rent ledger, loan statement, all expense records |
Review, refinance or exit analysis |
| Rising vacancy or long leasing periods |
Weak tenant demand or uncompetitive property condition |
Days on market data, vacancy history, comparable listings |
Improve property, review rent, or reassess location |
| Multiple special strata levies or capital works notices |
Structural or building liability emerging |
Strata minutes, sinking fund statement, building reports |
Quantify total exposure before deciding |
| Insurance premium spikes or coverage refusals |
Elevated flood, bushfire or building risk |
Insurer correspondence, state planning maps, council overlays |
Obtain address-specific specialist advice |
| Comparable sales weakening without a market-wide cause |
Possible structural demand weakness in the specific location |
Comparable sales data, days on market, listing volumes |
Investigate supply, employment and demographic trends |
| Portfolio concentration in one market or one asset type |
Single-point risk to serviceability or cash flow |
Full portfolio schedule, borrowing capacity assessment |
Diversification or sequencing review |
| Tax position materially affected by 2027 reforms |
Purchase date or property type places asset under new rules |
Tax advice specific to ownership structure and dates |
Obtain registered tax adviser input |
Persistent Negative Cash Flow
A deliberate short-term cash flow position where a well-located asset is building equity and the investor can comfortably absorb the shortfall is different from a property that remains deeply loss-making under realistic rent, vacancy, interest, maintenance, and insurance assumptions. The distinction matters more after 2027, when some established properties acquired after 12 May 2026 can no longer offset those losses against other income.
The Australian Taxation Office rental properties guidance covers deductible expenses and depreciation concepts. It does not tell you whether your cash position is sustainable. That requires your actual numbers.
Weak Rental Demand or Poor Tenant Appeal
One slow leasing period in a tight labour market or during a seasonal trough is not the same as structural weakness. A pattern of long vacancy periods, below-market rent to retain a tenant, or repeated refusals from prospective tenants is more significant. Use verified rental appraisals, days-on-market data across multiple comparable properties, and the property's own leasing history over three to five years before concluding that demand is soft.
Rising Maintenance, Insurance, Strata or Compliance Exposure
Building age, construction quality, and common-area condition can convert a nominally positive cash flow property into a loss-making one when capital works, special levies, or insurance costs arrive. Review strata meeting minutes, the sinking fund balance, any defect notices, and the insurer's most recent renewal terms. For properties in flood-affected or bushfire-prone areas, check state and council planning maps for updated hazard overlays.
How Should Investors Stress-Test Investment Property Cash Flow Before 2027?
Gross yield is not the same as net return. A common error is to divide annual rent by purchase price, compare it against a benchmark, and stop there. The number that matters is the after-expense, pre-tax cash position, modelled at realistic rather than optimistic assumptions. Run a positive cash flow analysis before deciding whether to hold.

Gross Yield Is Not the Same as Net Return
The standard formula: Net operating income = Annual rent x (1 – vacancy rate) – (interest + property management + insurance + council rates + land tax + strata + repairs and maintenance + water charges)
Depreciation is a non-cash deduction that reduces taxable income but does not reduce the actual cash leaving your account. Presenting a tax benefit as an economic return overstates the investment's real performance. The ATO rental properties guidance covers deductible expense categories. Individual tax outcomes depend on ownership structure and marginal rate; confirm with a registered tax adviser.
Use Actual Loan and Property Costs
Illustrative stress-test model (label all inputs as your actual figures; this is an example structure, not a forecast):
| Cost line |
Base case |
Stress: interest +1% |
Stress: vacancy 8 weeks |
Stress: major repair |
| Annual gross rent |
Your rent |
Same |
Reduced by vacancy |
Same |
| Vacancy allowance |
2-3 weeks |
2-3 weeks |
8 weeks |
2-3 weeks |
| Interest (current loan) |
RBA lender-rate range |
Add 1% to rate |
Same |
Same |
| Property management |
Actual % |
Same |
Same |
Same |
| Insurance |
Renewal figure |
Same |
Same |
Same |
| Council rates |
Current notice |
Same |
Same |
Same |
| Land tax (state-specific) |
Current assessment |
Same |
Same |
Same |
| Strata (if applicable) |
Annual levy + works |
Same |
Same |
Same |
| Repairs and maintenance |
5-year average |
Same |
Same |
Add large repair |
| Net cash position |
Sum |
Sum |
Sum |
Sum |
NSW land tax thresholds and rates differ from other states. Revenue NSW publishes current NSW land tax guidance for NSW properties. Check the relevant state revenue office for properties held in Victoria, Queensland, South Australia, Western Australia, or other jurisdictions.
After completing the table, book a free strategy session to assess the numbers in the context of your full portfolio rather than a single property in isolation.
When Does Capital Growth No Longer Justify the Holding Costs?
Capital growth is a hypothesis supported by fundamentals, not a guarantee. The PropTrack Home Price Index for June 2026 shows national prices remained 5.8% higher than a year earlier despite three consecutive monthly falls, with the Cotality Home Value Index recording a national decline of 0.4% in June 2026, its sharpest monthly fall since December 2022. These national figures mask significant divergence: some markets were still recording annual gains while others were retreating from prior peaks. A market-level statistic cannot substitute for a property-specific assessment.

Separate a Temporary Slowdown From a Structural Weakness
| Temporary signal |
Structural signal |
| One weak leasing period in a tightening labour market |
Persistent vacancy in a location with falling employment |
| A cyclical price pause after a strong run |
Several years of flat or negative growth with no infrastructure catalyst |
| Higher holding cost from a rate rise that is cycling through |
Oversupply of comparable stock with no demand catalyst |
| Short-term insurance premium increase |
Uninsurability due to flood, bushfire or building defect |
| One-off maintenance bill |
Recurrent structural repairs or capital works with no end date |
Do Not Use Forecasts as Guarantees
Every market forecast carries uncertainty, and historical performance does not guarantee future results. When citing a market statistic, record the index name, the geography it covers, the reference month and year, and the methodology. PropTrack and Cotality data are useful for directional context but should not be used as a property-specific forecast for a single address. Population and migration data from the ABS regional population statistics can support demand analysis, but population growth does not translate automatically into rent or price outcomes for a specific property.
What Property-Specific Risks Should You Reassess Before 2027?
Risk is not an abstract concept in a property portfolio. Each risk category below has a direct link to future holding costs, insurance terms, or resale liquidity.
Building Defects, Strata Liabilities and Upcoming Capital Works
For strata properties, review the owners corporation meeting minutes from the past two years, the current sinking fund balance relative to the 10-year plan, any outstanding defect notices, and any special levy resolutions. A sinking fund that is materially underfunded against known capital works is a future cash flow liability, not a theoretical risk. Obtain a building and pest inspection report for freestanding properties and, where defects are suspected, engage a specialist building consultant.
Flood, Bushfire, Insurance and Planning Exposure
Insurance availability and premiums for properties in high-hazard zones have tightened in parts of Queensland, New South Wales and Victoria. Check the relevant state planning portal and council mapping for flood and bushfire overlays. Do not rely on the listing description or the previous owner's disclosure alone. An insurer's willingness to provide cover at a reasonable premium is itself a signal about the property's risk profile. Do not describe any property as safe, insurable, or low-risk without address-specific, current professional evidence.
Is Negative Gearing Enough Reason to Keep a Property?
No, negative gearing alone is not enough reason to keep a weak investment property.
A tax deduction reduces taxable income. It does not create economic profit, improve the asset's physical condition, increase tenant demand, or build equity faster than the property's market is moving. Four definitions help separate the concepts:

- Tax benefit: the reduction in income tax payable from a deductible rental loss. This is real but depends on the investor's marginal rate and, from 2027-28, on whether the property is subject to the quarantining rules.
- Cash benefit: the actual reduction in out-of-pocket holding cost after the tax saving. This is less than the tax benefit and does not offset the full cash loss.
- Economic return: the net gain from rent, tax effect, and capital appreciation after all costs. This is the only complete measure.
- Portfolio value: the contribution this asset makes to the investor's borrowing capacity, equity, diversification, and long-term plan.
The 2027 reforms, confirmed under the enacted Treasury legislation, change the tax benefit calculation for properties purchased after 12 May 2026 from the 2027-28 income year. For properties held before that date, the negative gearing treatment is preserved. Individual outcomes depend on purchase date, ownership structure, and taxpayer circumstances. Obtain advice from a registered tax adviser before treating any general statement as applicable to your situation.
Can a Property Be Acceptable but Still Wrong for Your Portfolio?
Yes. A property that meets a reasonable set of individual performance tests can still reduce the strength of a portfolio as a whole.
Concentration risk is one dimension. An investor with three properties in the same suburb, the same property type, and similar tenancy profiles has amplified exposure to one local market. A single employment shock, planning change, or insurance event can affect all three assets simultaneously.
Debt structure is another. Properties with interest-only debt approaching a principal-and-interest conversion, a high loan-to-value ratio without near-term equity release, or a combined borrowing exposure that limits serviceability for the next acquisition may be constraining the portfolio's growth even if each individual asset is performing acceptably.
The opportunity cost question is the sharpest test: could the equity in this property, redeployed through a sale or refinance, fund an acquisition with better forward return, lower risk, and stronger portfolio fit? If the answer is probably yes, that is not a reason to sell immediately. It is a reason to model the comparison carefully before the next review date. For a property investment strategy service review that incorporates portfolio sequencing, that modelling should precede any exit decision.
A Practical Hold, Review or Exit Framework
This is a decision process, not a recommendation. Use it to organise evidence before obtaining tax, finance, legal, and property advice.

Step 1: Record the Current Position
Gather the current rent and any rent review date, the loan balance, interest rate and expiry of any fixed term, the annual expense schedule (insurance, rates, land tax, strata, management, maintenance), a current market valuation or recent comparable sales evidence, the estimated equity position, and the current tax treatment of any rental loss.
Step 2: Test the Next Three to Five Years
Run at least three scenarios, not one forecast. Use cautious assumptions: rent flat for two years, interest rate 1% higher, vacancy at 6 to 8 weeks per year, a major repair in year two, and no capital growth. If the property remains serviceable and the equity position holds under all three scenarios, the risk profile may be acceptable. If the worst-case scenario produces an unsustainable cash drain, that is a material finding.
Step 3: Compare Hold, Refinance, Improve or Exit
Map the expected net contribution of the asset over the stress-test period against what the equity and capital could produce in an alternative use. Include CGT on accrued gains, agent and conveyancing fees, loan discharge costs, stamp duty on a replacement acquisition, and the time and cost of transition. An exit that looks attractive on gross proceeds often looks less compelling once those transaction costs are accounted for. Identify where to buy investment property if a replacement acquisition is part of the plan before committing to an exit.
Step 4: Obtain the Right Advice
The decision involves at minimum: a registered tax adviser for CGT, negative gearing treatment, ownership structure and the 2027 rule application; a licensed financial adviser if the decision affects retirement income or superannuation; a conveyancer or solicitor for sale documentation and property transfer; a lender or mortgage broker for refinancing options; a building inspector for structural or defect questions; and an insurer for cover confirmation. Property investment advisor support from a buyer-side property specialist can inform the asset selection, market research and portfolio sequencing elements, but does not replace any of the regulated advice categories above.
Data-led investment property support from Buyers Agency Australia focuses on the buyer-side strategy and acquisition planning components of this process.
Where Buyers Agency Australia Fits Into a Hold or Exit Review
Dragan Dimovski, a property expert with 20-plus years of experience, leads the Buyers Agency Australia team. The team works on buyer-side strategy, market research, off-market access, due diligence, and end-to-end acquisition support for Australian property investors. Where a hold or exit review identifies the need for a replacement acquisition or a portfolio resequencing, that is where the Buyers Agency Australia team provides most value: sourcing and securing the right asset rather than the convenient one.
One honest boundary: Buyers Agency Australia does not replace a registered tax adviser, licensed financial adviser, solicitor, conveyancer, lender, building inspector or insurer. Each of those roles requires its own qualified professional.
Disclosure: This article is published by Buyers Agency Australia, the service provider referenced in the text. Tax settings, market references and Buyers Agency Australia service references were checked in July 2026. Recheck them before publication and after any material change.
What Should I Check Before Selling an Investment Property in Australia?
Use this checklist before committing to a sale.
- Confirm the reason for selling and whether it is based on forward evidence or a reaction to a headline.
- Obtain an accountant's estimate of CGT payable, including the impact of purchase date, ownership structure, and any post-1 July 2027 gain accrual.
- Get a current independent market appraisal or formal valuation.
- Calculate all selling costs: agent commission, conveyancing, marketing, and any make-good or tenant relocation obligations under state tenancy law.
- Obtain the lender's payout figure and confirm whether break costs, discharge fees or clawback provisions apply.
- Confirm the tenancy arrangements and any required notice period under the relevant state or territory residential tenancy legislation.
- Identify what happens to the capital: debt reduction, portfolio reinvestment, or both, and model the after-tax outcome of each path.
- Document the decision with the evidence used so it can be reviewed if circumstances change.
Frequently Asked Questions
Does 2027 mean I should sell my Australian investment property?
No, 2027 does not create a universal sell requirement. The decision depends on the property's forward performance, its purchase date, the investor's tax position, risk exposure and how it fits within the portfolio.
What makes an investment property no longer worth holding?
A property may no longer be worth holding when its forward return and strategic role no longer justify its cash cost and risk. Persistent cash losses, structural location weakness, rising exposure costs and a better use for the capital are the main signals.
How do I calculate investment property cash flow?
Calculate annual rent less vacancy, interest, rates, insurance, management fees, maintenance, land tax, strata and other recurring costs. The result is pre-tax cash flow. After-tax position requires your marginal rate, ownership structure and current ATO guidance applied to your specific facts.
Is negative gearing enough reason to keep a property?
No, a tax deduction alone is not enough reason to keep a weak asset. A deduction reduces taxable income; it does not create economic profit or improve the property's fundamentals. Obtain ATO guidance and personal registered tax advice before making a holding decision based on tax alone.
How do the 2027 tax changes affect established investment properties?
The effect depends on when the property was acquired. Properties held at 7:30 pm AEST on 12 May 2026 are exempt from the negative gearing quarantine rules. Established properties acquired after that time are subject to loss quarantining from the 2027-28 income year. CGT changes apply to gains accruing after 1 July 2027 across both categories. Verify the exact treatment with a registered tax adviser using the enacted Treasury Laws Amendment (Tax Reform No. 1) Act 2026.
Should I sell a high-yield property with weak capital growth?
Not automatically. The answer depends on net cash flow after all costs, resale liquidity, the quality of rental demand, and how the asset fits the portfolio strategy. High gross yield can coexist with poor resale depth, structural demand weakness, or unacceptable risk exposure.
What property risks should I check before 2027?
Check building defects, strata liabilities and upcoming capital works, insurance availability and premium changes, flood and bushfire hazard overlays using official state planning maps, current planning or zoning changes, and the depth and consistency of tenant demand. Each requires address-specific evidence, not a general market assessment.
Should I use a buyer's agent to review my portfolio?
A buyer-side property adviser may help with asset selection, market research, off-market sourcing and the planning of a replacement acquisition. They cannot replace a registered tax adviser, financial adviser, solicitor or lender for decisions involving CGT, ownership structure or debt restructuring.
When should I speak with an accountant before selling?
Speak with a registered tax accountant before acting whenever CGT, ownership structures, negative gearing treatment, or large capital gains may affect the outcome. Acting before obtaining that advice can produce an avoidable and irreversible tax result.
What should I do if I am unsure whether to hold or sell?
Build a documented hold, review or exit model using actual figures and stress-tested assumptions, then obtain professional advice on the tax, finance and legal dimensions. Ambiguity about the right decision is usually a signal that the evidence base is incomplete rather than that the answer is obvious.
Final Takeaway: Review the Asset, Not Just the Market Forecast
No universal sell date exists. An investment property in Australia becomes unsuitable when its forward cash flow, asset fundamentals, risk profile and portfolio role no longer justify the capital tied up in it. A calendar date or tax change can prompt a useful review; it cannot substitute for one.
Before acting, apply three checks. Does the property work on realistic forward cash flow, including a stress scenario? Does it still have credible asset fundamentals: land value, tenant demand, location depth? Is it the best use of the capital it holds within your current portfolio and financial goals?
Where those checks produce clear answers, the path forward is usually straightforward. Where they produce uncertainty, that is when professional tax, financial, legal and property advice earns its cost many times over.
To map out your next property move with a strategy-focused session, book a conversation with the Buyers Agency Australia team. If you are ready to move forward, contact the team directly.
This article is general information only and does not constitute tax, financial, legal, lending, building or insurance advice. Obtain advice from qualified professionals before making any property investment decision.
 General
Learn why some Australian investment properties may not be worth holding after 2027, using a clear cash-flow, risk...
A property that may outperform is not one with a guaranteed return. It is an asset whose suburb and property fundamentals are stronger than comparable markets, with demand, supply constraints, employment, liveability, liquidity and manageable risks working together.
Start with suburb data, test the property against comparable sales and rental evidence, then complete planning, building, strata and holding-cost due diligence before making an offer. No property can be guaranteed to outperform its market.
You have seen the headline: a suburb described as the next growth area. The question that follows is harder to answer. Is the evidence real, or is it already priced into the market? That uncertainty is where most investors stall.
The practical question is not how to predict the future. It is how to improve the quality of the decision before money changes hands. A rigorous, repeatable process reduces the chance of buying the wrong suburb, overpaying for the wrong property, or missing a risk that later forces a sale at the wrong time.
This guide walks through a suburb-first, property-second, due-diligence-third framework rooted in a data-led property investment strategy. It covers the signals worth checking, the data worth sourcing, and the questions worth asking before you make an offer.
What does it mean for a property to outperform the market?
Outperformance is not a fixed outcome. It is a relative one, measured against a relevant benchmark over a defined holding period.
A property in a regional city that grows 6% per year while comparable dwellings in the same suburb average 3% has outperformed its local market. A property in a high-profile suburb that rises 12% but carries flood risk, insurance difficulty, low liquidity and a concentrated buyer pool may produce a worse risk-adjusted outcome than it appears.

The benchmark that matters is the one closest to your strategy: the suburb, the property type, the price range, and the holding period you are actually working with.
Outperformance is relative, not absolute
Four dimensions define genuine outperformance for an investment property:
| Dimension |
What it measures |
Why it matters |
| Capital growth |
Change in market value relative to comparable properties over the holding period |
Directly affects equity and future borrowing capacity |
| Rental performance |
Rent achieved relative to comparable dwellings in the same suburb |
Affects cash flow and holding-cost resilience |
| Liquidity |
Speed and ease of resale at a fair price |
Limits exit options and affects real returns |
| Risk-adjusted outcome |
Returns adjusted for known hazards, holding costs, and downside scenarios |
A higher nominal return is not automatically better |
Building a strong property investment research guide starts with being honest about which benchmark applies to your specific strategy, budget, and timeline.
Why risk and liquidity belong in the definition
A property can rise in price and still be a poor investment. If it is expensive to insure, subject to flood or bushfire constraints, in a suburb with thin buyer demand, or tied to a long-term lease at below-market rent, the headline capital growth figure overstates the real outcome.
Risk is not a reason to avoid investing. It is a reason to price it correctly and factor it into every comparison.
How can you tell whether a suburb has genuine growth potential?
The suburb decision comes before the property decision. Every metric, inspection, and comparable sale is only as useful as the location it sits in.

Start with strategy: what holding period are you working with, what is your borrowing capacity, what role does this property play in the portfolio, and what level of cash flow disruption can you absorb? Those inputs shape which suburbs are genuinely suitable and which ones are just interesting.
Demand drivers: employment, population and amenity
Suburbs with durable demand share common characteristics. Employment diversity matters because a suburb dependent on a single industry or employer is exposed to structural shocks in ways a suburb with diversified healthcare, education, government, and commercial employment is not.
According to the ABS regional population data for 2024-25, Australia's combined capital city population grew by 1.8% in the year to June 2025, adding around 325,000 people. That aggregate figure, however, conceals wide variation. Population is not distributed evenly, and growth in one city or region does not automatically translate to property demand in every suburb within it.

Checklist for demand drivers:
- Employment base: how many industries, employers and income brackets?
- Population change: is the suburb gaining or losing residents, and from where?
- Schools, health, transport and retail: do they attract families, professionals and downsizers?
- Affordability relative to adjacent suburbs: is this area still accessible to the likely buyer pool?
Population growth alone is not enough. The question is whether the incoming population can afford, or is likely to rent, the specific property type you are assessing.
Supply constraints and the development pipeline
Demand and supply must be assessed together. A suburb with strong population inflow but a large apartment pipeline may see rental yields compress rather than rise, and resale competition increase rather than decrease.

ABS building approvals data shows that dwelling approvals nationally remain below the level required to meet Australia's long-term housing needs, though the pipeline varies considerably by geography and dwelling type. For any suburb under consideration, the question is not what is happening nationally but what the local supply position looks like: how many dwellings are approved, under construction, and due for delivery in the next two to three years, and against what level of underlying demand?
Use state planning portals, council development registers, and official project documentation to identify the supply pipeline. Treat approvals and announcements as separate from completed dwellings.
Which property data matters most before you buy?
Research follows a sequence. Confirming market direction comes first, then demand, then supply, then liquidity, and finally property-specific evidence.
Price growth, comparable sales and transaction depth
Median price movement is a lagging indicator. It tells you where the market has been, not where it is heading. More useful signals are transaction volume, days on market, and the relationship between asking price and final sale price.
| Data point |
Signal type |
Research action |
| Median price change |
Lagging |
Compare against similar suburbs and property types over 1, 3 and 5 years |
| Days on market |
Current |
Shorter periods suggest stronger demand; spikes may reflect overpricing or weak interest |
| Transaction volume |
Current |
Thin markets restrict comparables and resale options |
| Comparable sales |
Current |
Require recent, same-property-type sales within the same suburb or immediate precinct |
| Vendor discounting |
Current |
The gap between list price and sale price reflects real buyer sentiment |
| Rental yield |
Current |
Compare gross yield against equivalent suburbs to assess relative income and value |
| Vacancy rate |
Current |
Use local, dated rental data rather than any universal percentage threshold |
| Dwelling approvals |
Leading |
Cross-reference with population growth to assess net supply pressure |
CoreLogic's home value index methodology and PropTrack's property reports both provide structured data on price trends and market depth. Use those sources with a specific geography, property type, and reference period recorded.
Rental demand, vacancy and tenant depth
Rental demand tests whether real tenants at realistic rents exist for the property type you are considering. Low vacancy may indicate strong rental conditions, but it must be paired with supply, employment, affordability, and price evidence before drawing any conclusions about capital growth.
A tightly held rental market with a small number of available dwellings can produce a low vacancy figure that disappears quickly if one developer completes a new building nearby. Check the pipeline alongside the vacancy figure.
Infrastructure and market-cycle signals
Funded and active projects carry more weight than announcements. A transport upgrade under construction differs materially from a proposal that has not cleared planning approval. Use official transport authority, state government, and council sources to verify project status. Record whether the project is proposed, funded, under construction, operating, or cancelled, and note the source and date of that assessment.
Infrastructure may improve amenity and access, but it does not guarantee that property prices will rise by any particular amount. Its value depends on whether demand and supply fundamentals support that outcome.
How should you assess the property itself?
A strong suburb does not make every property within it a sound purchase. Once the location passes your screening criteria, the property must be assessed on its own merits.
Land, layout and scarcity
For houses and townhouses, usable land, orientation, and the ability to add value over time are relevant. A dwelling on land that cannot be extended or improved has fewer future uses than one with genuine development or renovation potential.
For apartments and units, the relevant questions are floor plan functionality, natural light, parking, building age, and how many similar properties exist in the same precinct. A scarce product in a desirable location will attract more future buyers than a near-identical unit in a building with 200 comparable dwellings.
Blanket rules such as houses always outperform units do not hold across all markets or all holding periods. The relevant test is: is this property scarce within its suburb, and is the likely future buyer pool broad enough to support liquidity?
Comparable sales and realistic value
Comparable sales are the most reliable check on whether you are paying a fair price. They must be genuinely comparable: same property type, similar land area, similar condition and improvement level, within the same suburb or immediate precinct, and sold within a timeframe that reflects current market conditions.
Differences in land size, outlook, internal condition, and proximity to transport or noise sources all require explanation. An agent's price guide is not a comparable sale. A suburb median is not a comparable sale. You need the actual sale price of a specific, similar property.
Tenant appeal and exit-buyer depth
Tenant appeal and owner-occupier appeal often overlap. Properties that attract stable tenants tend to attract the broadest pool of future purchasers. Ask who the next buyer will be: a family, a downsizer, another investor, or a first home buyer? A narrow exit-buyer pool restricts liquidity and may limit the price you can achieve when selling.
How do you spot early signals without chasing property hype?
The difference between a credible early signal and speculative enthusiasm is the quality and convergence of the evidence behind it. One positive article, one infrastructure announcement, or one month of strong auction clearance rates is not a trend.
Funded, underway and delivered are different signals
Project status determines how much weight any infrastructure signal deserves. Use the following classification when assessing any reported project:
- Proposed: in planning or consultation only; no funding commitment
- Funded: government budget allocation confirmed; check for conditions
- Under construction: physical works underway; timeline may still shift
- Operating: completed and delivering amenity to the market
- Cancelled or deferred: previously announced but no longer active
Anything below funded should be treated as a prompt for further research, not evidence of coming growth. Check the relevant state government, transport authority, or council source. Record the status and the date you checked it.
For guidance on how to find property hotspots early, the same discipline applies: treat hype as a prompt for research, not as evidence of growth.
Catch-up potential versus an overheated market
A suburb that has not yet grown as fast as comparable areas may represent genuine catch-up potential, or it may reflect real structural weaknesses that informed buyers have already discounted. The distinction requires checking demand, employment, supply, and affordability together rather than assuming underperformance is temporary.
Recent rapid price growth can signal that the market has already repriced. Buying into a suburb after significant short-term gains without checking whether fundamentals still support further upside carries real risk of overpaying. Current Australian housing market data shows conditions vary sharply by city, price point, and property type, reinforcing why a generic national view is not a substitute for suburb-level research.
What property due diligence should happen before making an offer?
Due diligence is not optional. It is the process that separates a supported decision from a speculative one. The following checks should be completed before committing.

Physical condition and building risk
For houses, townhouses, and older units, an independent building and pest inspection is a standard part of the purchase process. Consumer Affairs Victoria recommends professional building and pest inspections and independent checks before purchase. Requirements and conventions vary by state and territory, so confirm the process in the relevant jurisdiction with a qualified conveyancer or solicitor.
A building report will not eliminate all risk, but it will identify significant defects, evidence of moisture or pest activity, and items that require immediate or future rectification. Do not rely on a vendor's disclosure statement alone.
Planning, flood, bushfire and development controls
Planning certificates, flood overlays, and bushfire risk maps are available through state planning portals and local councils. In NSW, for example, a Section 10.7 certificate can identify zoning, flood, bushfire, and contamination constraints on a specific property. This is a NSW-specific planning tool and is not a national requirement; equivalent checks in other states follow different processes and are governed by different authorities.
Planning controls directly affect what can be built on or near a property. A rezoning that permits higher-density development adjacent to your investment may affect amenity, outlook, and future demand.
Strata, leases, insurance and ongoing costs
For units and apartments, strata records matter. Review the owners corporation minutes, levies, sinking fund balance, any outstanding defects or special levies, and by-laws that affect use, rental, or renovation. A sinking fund that cannot cover known defects is a future liability for every owner.
For all property types, model the full holding cost: mortgage repayments at current and plausible higher rates, council rates, water, insurance, property management, maintenance, and a vacancy buffer. The RBA cash rate target currently sits at 4.35% as at June 2026, and its effect on mortgage rates directly influences what investors can sustainably hold. Borrowing and holding-cost assumptions should be stress-tested against a range of scenarios rather than based on a single rate expectation.
Finance, tax and professional advice
This article provides general educational information only. It is not personal financial, tax, legal, planning, or building advice. Before making any investment decision, obtain independent advice from a qualified broker, accountant, solicitor or conveyancer, and a building inspector where appropriate. Tax treatment, stamp duty, land tax, and planning requirements vary by state and territory and by individual circumstances.
For where to buy investment property and related location research, ensure any decision is supported by current, jurisdiction-specific professional advice.
A practical high-growth property assessment checklist
This is an editorial screening tool, not a valuation, financial plan or guarantee of future performance. Every score must be supported by a named source, a reference date, and a specific geography or property address.
Score the suburb before scoring the property
Score each criterion from 0 (absent or unacceptable) to 5 (strong and well-evidenced). Also rate evidence confidence: H (high: official, current, local, independently verified), M (medium: reputable but indirect or slightly dated), L (low: limited, dated, or not specific to this market).
| Criterion |
Score (0-5) |
Evidence confidence |
Notes |
| Employment diversity |
|
|
Number of industries, income levels, employer mix |
| Population growth and composition |
|
|
ABS regional data, net migration, age profile |
| Supply pipeline constraint |
|
|
Dwelling approvals vs underlying demand |
| Infrastructure status |
|
|
Project stage: proposed / funded / under construction / operating |
| Rental demand and vacancy |
|
|
Local rental data with reference date |
| Transaction volume and liquidity |
|
|
Days on market, sales depth in last 12 months |
| Comparable price performance |
|
|
Median movement vs similar suburbs over 1, 3, 5 years |
| Affordability relative to adjacent suburbs |
|
|
Price and income context |
Score strategy fit and downside risk
| Criterion |
Score (0-5) |
Evidence confidence |
Notes |
| Property scarcity within suburb |
|
|
How many comparable dwellings exist? |
| Physical condition and defect risk |
|
|
Building and pest report findings |
| Planning and zoning risk |
|
|
Council, state planning portal, flood and bushfire checks |
| Insurance availability and cost |
|
|
Obtain quotes; check flood and bushfire category |
| Comparable sales support value |
|
|
Minimum two recent, genuinely comparable sales |
| Exit-buyer depth |
|
|
Owner-occupier, investor, family, downsizer demand |
| Holding-cost resilience |
|
|
Can the position be held if rates rise or vacancy extends? |
| Strategy fit |
|
|
Does this property match the stated portfolio role and timeline? |
When should an investor walk away?
Stop criteria that warrant exiting the assessment:
- A material building defect that cannot be priced or remediated before settlement
- Flood, bushfire, or contamination risk that makes insurance unavailable or uneconomic
- Comparable sales evidence that does not support the asking price
- Strata records showing unresolved defects, an underfunded sinking fund, or significant pending levies
- Holding costs that cannot be sustained without assuming best-case rent, rates, and vacancy
- Infrastructure or demand assumptions that cannot be verified from an official source
- A property that does not fit the stated portfolio strategy, regardless of how compelling it appears
After completing the checklist, book a free strategy session to review your scores with a property investment professional before proceeding to offer.
When should an investor involve a buyers agent?
A strategy-led buyers agent can add value at several points in the process: refining the brief, conducting suburb and property research, accessing selected pre-market or off-market opportunities where they exist, assessing value against comparable sales, negotiating the purchase, and coordinating the steps through to settlement.
Understanding what a buyers agent does makes clear that the role is not simply finding a listing. It is reducing unstructured search, improving evidence quality, enforcing the buyer's strategy, and applying consistent walk-away discipline.
What a buyers agent can and cannot validate
What a buyers agent can support:
- Suburb and property research grounded in current data
- Shortlisting against a defined strategy and budget
- Access to selected pre-market and off-market opportunities where available
- Independent assessment of value against comparable sales
- Negotiation and transaction coordination through to settlement
- Enforcing the buyer's walk-away criteria when emotion rises
What a buyers agent cannot guarantee:
- Future capital growth on any property
- Rental income or occupancy levels
- Finance approval or borrowing capacity
- That any property will outperform its market
- Legal, tax, building, or planning outcomes outside the scope of their licence
A buyers agent improves decision quality. It does not remove market uncertainty.
How Buyers Agency Australia can support the assessment
Buyers Agency Australia is included here because this article explains its own buyer-side assessment approach, not because the page ranks or compares providers.
Buyers Agency Australia is a Sydney-based property advisory firm operating nationally. Its approach to investment property acquisition is built on strategy before property selection, data-led suburb analysis, and end-to-end support from planning through to settlement.
Dragan Dimovski, the firm's founder, brings over 20 years of personal property investment experience to the advisory process. The team uses a structured research approach that covers market data, supply and demand fundamentals, comparable sales, and property-level assessment before a shortlist is presented to a client.
For investors working through the two-stage suburb-to-property framework described in this guide, the property investment strategy support offered by the team can help translate a research process into a specific, actionable acquisition plan.
When this may not be the right fit. A buyers agent service may not be suitable for someone who has not yet defined a clear investment strategy, is not financially ready to proceed, needs regulated financial, tax, legal, or building advice (which falls outside the scope of a buyers agency licence), or wants to make every research and negotiation decision independently.
Property markets are uncertain. Past performance does not guarantee future results. Readers should obtain individual financial, tax, legal, building, and planning advice from qualified professionals before making any property investment decision.
Frequently asked questions about high-growth property
What makes a property high growth?
Several verified signals align: suburb-level demand outpaces supply, employment is diverse, rental evidence is strong, the property is scarce within its category, and known risks are manageable. No outcome is guaranteed.
How can I tell if a suburb has genuine growth potential?
Test demand, employment diversity, population composition, supply pipeline, infrastructure project status, and affordability together. One positive signal is not sufficient on its own.
Is a low vacancy rate enough to predict capital growth?
No. Vacancy indicates rental demand conditions and must be paired with supply evidence, employment data, affordability, and price trend data before drawing any conclusions about capital growth.
Should I buy the suburb with the highest recent price growth?
Not automatically. Recent strong growth may mean the market has already repriced, reducing the margin available to the next buyer. Assess whether fundamentals support further upside at the current asking price.
How important is infrastructure to property growth?
Infrastructure matters when the project is funded, credible, relevant to the suburb, and matched by underlying demand. An announcement is not a proof of future price movement.
What should I check before making an offer?
Building and pest condition, planning controls, flood and bushfire risk, strata records (for units), insurance availability, lease terms if tenanted, comparable sales, holding costs, and finance pre-approval. State-specific requirements vary.
Can a buyers agent guarantee a property will outperform?
No. A buyers agent can improve research quality, shortlisting, negotiation, and process discipline, but cannot guarantee capital growth, rental income, or any future performance outcome.
How should I score a property against my strategy?
Use the editorial scoring table in this guide. Attach a named evidence source and date to each criterion. Apply the walk-away rules to any amber or red items before proceeding.
When should I walk away from a property that looks promising?
Walk away when important risks are unresolved, comparable sales do not support the asking price, evidence is weak, or the purchase does not align with the stated financial and portfolio plan.
Is this property investment advice?
No. This is general educational information for awareness purposes. It is not personal financial, tax, legal, planning, or building advice. Obtain professional advice specific to your circumstances before making any investment decision.
Evidence over certainty: the final property decision framework
No framework removes uncertainty from property investment. What a rigorous process does is reduce the chance of acting on weak evidence, misidentifying hype as fundamentals, or overlooking a risk that changes the outcome.
The decision sequence this guide recommends:
- Define the strategy: portfolio role, holding period, budget, borrowing capacity, cash flow tolerance
- Screen the suburb: demand drivers, supply pipeline, employment, population, infrastructure status
- Test demand and supply together: rental evidence, vacancy, transaction depth, comparable price data
- Assess the property: scarcity, condition, comparable sales, tenant appeal, exit-buyer depth
- Complete due diligence: building, planning, flood, bushfire, strata, insurance, holding costs
- Score evidence quality: rate the confidence behind each criterion, not just the criterion itself
- Apply walk-away rules: stop when any hard-stop signal is unresolved
If you are ready to apply this framework to a specific market and property type, map out your next property move with the Buyers Agency Australia team before committing to an offer.
For any questions about how the assessment process works, contact the Buyers Agency Australia team directly.
 General
Learn how Australian investors can assess high-growth property using suburb data, supply, demand, due diligence and a repeatable...